


Enhanced Composition Scheme Turnover Limit Applicable Only From April 1, 2019, Disallowing Retrospective FY 2018-19 Claim
Issue
Whether a registered dealer under GST can claim the benefit of the enhanced composition levy turnover limit for FY 2018-19 with effect from February 1, 2019 under Notification 02/2019-CT, or if the enhanced threshold operates only from April 1, 2019 pursuant to Notification 14/2019-CT.
Facts
-
The petitioner, a registered dealer under GST, challenged the assessment order and consequential DRC-07 summary order for the period 2018-19.
-
A show-cause notice (SCN) in Form DRC-01 was issued offering a personal hearing, which the petitioner failed to attend.
-
The petitioner claimed entitlement to the composition scheme under Section 10 of the CGST/TNGST Act at an enhanced turnover threshold (above Rs. 50 lakhs up to Rs. 1.50 crores) mid-year for FY 2018-19.
-
The petitioner asserted that Notification 02/2019-CT made the enhanced turnover threshold effective from February 1, 2019.
-
The adjudicating authority rejected the claim and confirmed the SCN proposals along with interest and penalty.
Decision
-
The High Court held that Notification 02/2019-CT merely notified the effective date of the statutory amendment to the proviso to Section 10(1) of the CGST/TNGST Act.
-
The Court noted that for actually implementing the enhanced threshold, the Government issued Notification 14/2019-CT dated March 7, 2019, which explicitly came into effect from April 1, 2019.
-
Since the enhanced turnover limit operated prospectively from April 1, 2019, the petitioner’s claim to opt for the enhanced composition scheme for FY 2018-19 with effect from February 1, 2019 was held legally untenable.
-
The Court ruled that the petitioner could opt for the enhanced limit only for the succeeding tax period commencing April 1, 2019, and accordingly dismissed the writ petition in favor of the Revenue.
Key Takeaways
-
Prospective Implementation of Thresholds: Amendments enhancing composition scheme turnover limits apply prospectively from the date specified in the implementing notification (April 1, 2019), preventing retrospective or mid-year claims for prior financial years.
-
Notification Distinction: A notification bringing a statutory amendment into force (Notification 02/2019-CT) must be read alongside the specific operational notification (Notification 14/2019-CT) that prescribes the effective implementation date for tax benefits.
-
Compliance with SCN Opportunities: Failure to attend personal hearings provided under DRC-01 limits the scope to challenge factual findings when statutory notification dates clearly disentitle the relief sought
HIGH COURT OF MADRAS
Tvl. Sahayarani Medicals
v.
Assistant Commissioner (ST)
C. Saravanan, J.
WP (MD) No. 24239 of 2026
WMP (MD) No. 18049 of 2026
WMP (MD) No. 18049 of 2026
AUGUST 24, 2026
Raja. Karthikeyan for the Petitioner. R. Parthiban, Special Govt. Pleader for the Respondent.
ORDER
1. Mr. R. Parthiban, learned Special Government Pleader takes notice for the respondent.
2. This Writ Petition is taken up for final hearing at the time of admission with the consent of the learned counsel for the petitioner and the learned Special Government Pleader for the respondent.
3. In this Writ Petition, the petitioner has challenged the impugned assessment order in GSTIN. 33ABVPL8383P1ZJ/2018-19 and the summary order bearing Reference No. ZD331225442081X dated 30.12.2025 passed by the respondent, which was preceded by a Show Cause Notice in DRC-01 dated 17.06.2025, wherein the petitioner was also called upon to appear for personal hearing. However, the petitioner had not taken advantage of the same and thus, suffered the Impugned Order dated 30.12.2025.
4. The petitioner is before this Court against the impugned order dated 30.12.2025, whereby the proposal contained in the Show Cause Notice in DRC-01 dared 17.06.2025 has bee confirmed, together with interest and penalty. The specific case of the petitioner is that the petitioner was, all along, under the composition scheme and was, therefore, eligible to pay tax at the compounded rate in terms of the notifications issued under Section 10 of the respective GST enactments, 2017.
5. The learned counsel for the petitioner drew attention of this Court to Notification No.02/2019-Central Tax, dated 29.01.2019. The text of the said notification is reproduced below:
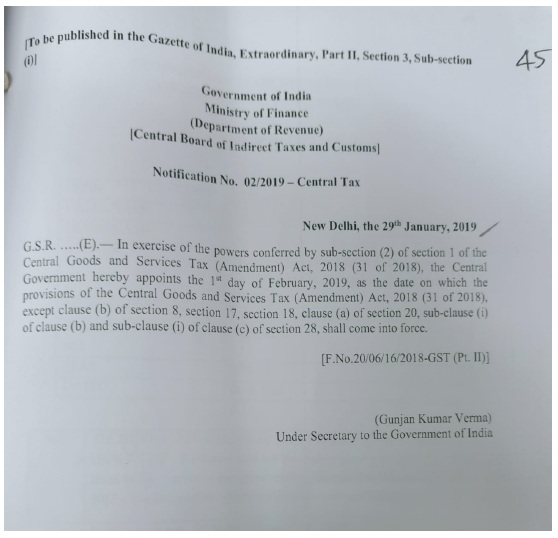
6. The said notification merely gives effect to the amendment to the proviso to Section 10(1) of the CGST Act. A similar notification has been issued to given effect to the corresponding amendment to the provisions of the TNGST Act, 2017. To give effect to the above notification, the Central Government also issued Notification No. 14/2019-Central Tax, dated 07.03.2019, with effect from 01.04.2019.
7. Thus, the contention of the petitioner that the benefit of composition levy was available where the turnover exceeded Rs.50,00,000/-, but was below Rs.1.50 crores, in terms of notification No.02/2019- Central Tax, dated 29.01.2019 with effect from 01.02.2019, is of no relevance, as the above notification was issued for implementing the above amendment was Notification No.14/2019-Central Tax, dated 07.03.2019 with effect from 01.04.2019. Therefore, the petitioner would be eligible for the composition levy in terms of the amendment only for the succeeding tax period commencing from 01.04.2019. Therefore, this writ petition is devoid of merits and is liable to be dismissed.
8. At this stage, the learned counsel for the petitioner submits that the petitioner is willing to pre-deposit 25% of the disputed tax as a condition for de novo adjudication.
9. The learned counsel for the petitioner has also made an endorsement to that effect in the Court Bundle, which is extracted hereunder:-
“The petitioner undertakes to pay 25% of the demand.”
10. Since the petitioner may have a case on merits insofar as the ultimate tax liability imposed is concerned, I am inclined to grant liberty to the petitioner to file an appeal before the Appellate Authority against impugned order, subject to the petitioner depositing 25% of the disputed tax in cash from the petitioner’s Electronic Cash Register within a period of thirty (30) days from the date of receipt of a copy of this order.
11. Subject to such compliance, the petitioner’s appeal shall be entertained by the Appellate Authority under Section 107 of the CGST Act, 2017 and disposed of on merits and in accordance with law, within a period of three motaxmnths thereafter. Needless to state, the petitioner shall also be heard.
12 .This Writ Petition is dismissed, with above directions. No costs.
Consequently, connected miscellaneous petition is closed.