


Assistant Commissioner Can Re-Examine Refund Claim on New Permissible Grounds When Appellate Authority Sets Aside Initial Rejection Order
Issue
Whether an Assistant Commissioner is precluded from re-examining a GST refund claim on fresh, legally permissible grounds when an Appellate Order sets aside an initial partial rejection without explicitly directing an unconditional refund release.
Facts
-
Refund Application: The petitioner, a registered taxpayer under GST, applied for a refund of unutilized input tax credit for the period July 2019 to September 2019.
-
Initial Rejection: The Assistant Commissioner issued a Show Cause Notice proposing partial rejection and subsequently passed an Order-in-Original (OIO) partially sanctioning the refund and rejecting the remaining balance.
-
Appellate Order: On appeal, the Appellate Authority passed an Order-in-Appeal (OIA) setting aside the OIO to the extent of the wrongful rejection, but without ordering an unconditional release or foreclosing further examination.
-
Fresh Assessment Order: Following the OIA, the Assistant Commissioner issued a fresh Impugned Order rejecting the refund again, providing detailed reasons.
-
Writ Challenge: The petitioner challenged the fresh rejection order via a writ petition, arguing it was non est and passed without jurisdiction in light of the earlier OIA.
Decision
-
No Mandatory Grant Ordered: The court held that the OIA had merely negated the specific grounds adopted in the original OIO and did not mandate an unconditional grant of the refund.
-
Jurisdiction Retained: The Assistant Commissioner was not precluded from conducting a fresh examination of the refund claim on other legally permissible grounds.
-
Impugned Order Validly Issued: The fresh rejection order was held to be neither non est nor passed without jurisdiction.
-
Statutory Remedy Directives: The court held that the proper recourse for the petitioner was to file a statutory appeal to challenge the validity, scope, and effect of the fresh grounds raised in the Impugned Order, ruling in favor of the Revenue.
Key Takeaways
-
Setting Aside Is Not Automatic Approval: An appellate order setting aside a refund rejection does not automatically translate to an unconditional refund grant unless specifically directed.
-
Scope for Fresh Scrutiny: Adjudicating authorities retain the jurisdiction to evaluate refund claims under alternative, legally permissible grounds when higher appellate forums do not foreclose further examination.
-
Exhaustion of Statutory Remedies: Writ courts will generally not bypass statutory appeal mechanisms to adjudicate the merits of a re-examined refund order when administrative jurisdiction exists.
HIGH COURT OF DELHI
Karamsar Poultry Appliances
v.
Assistant Commissioner, Janakpuri Division, CGST Delhi West
ANIL KSHETRAPAL and SHAIL JAIN, JJ.
W.P.(C) 9189 of 2026
CM APPL. 43124 of 2026
CM APPL. 43124 of 2026
JULY 13, 2026
Antik Majumder, Adv. for the Petitioner. Akash Panwar, JSC, Abhimanyu Kapoor, Adv., Kshitij Chhabra, SPC and Rahul Morya, GP for the Respondent.
ORDER
Anil Kshetarpal, J.- The present Petition has been filed seeking issuance of an appropriate writ setting aside the Rejection Order dated 20.02.2026 [hereinafter referred to as ‘Impugned Order’], passed by the Assistant Commissioner, CGST Delhi (West), vide which the Petitioner was denied the consequential refund of an amount of Rs. 3,44,469/- arising pursuant to the Order-in-Appeal (OIA) dated 27.09.2025 passed by the Joint Commissioner, CGST Appeals-II, Delhi.
2. Pithily put, the Petitioner filed an application seeking refund of unutilized Input Tax credit for the tax period from July 2019 to September 2019, claiming a refund of Rs. 6,49,667/-. Pursuant thereto, the Assistant Commissioner, Janakpur Division, issued a Show Cause Notice proposing rejection of the refund claim to the extent of Rs. 3,44,469/-, to which the Petitioner submitted a detailed reply.
3. Upon consideration thereof, the Assistant Commissioner, Janakpuri, vide Order-in-Original (OIO) dated 08.10.2021, partially sanctioned the refund to the extent of Rs. 3,05,198/- and rejected the balance amount of Rs. 3,44,469/-. Aggrieved thereby, the Petitioner preferred an appeal before the Appellate Authority, which, vide OIA dated 27.09.2025, set aside the OIO. Thereafter, the Petitioner’s refund application in respect of the aforesaid amount was once again rejected by way of the Impugned Order. Aggrieved thereby, the Petitioner has approached this Court.
4. Learned counsel representing the Petitioner claims that the OIA dated 27.09.2025 finalized the issue pertaining to refund and as such the Petitioner is required to be refunded an amount of Rs.3,44,469/-along with the statutory interest thereon. He submits that the Petitioner cannot be relegated to the statutory remedy of Appeal, particularly when the OIA dated 27.09.2025 has attained finality.
5. Per contra, learned counsel representing the Respondent, while referring to the observations made under Paragraph No.9.2 onwards of the Impugned Order, submits that the Assistant Commissioner while adjudicating the Petitioners request for refund, has provided detailed reasons for refusing the refund and therefore, the appropriate alternative remedy available to the Petitioner is to file an Appeal against the Impugned Order.
6. This Court has considered the submissions made by the Parties. Undisputedly the Appeal filed by the Petitioner came to be allowed by way of the OIA dated 27.09.2025, wherein the Joint Commissioner, in the concluding paragraph recorded as under:
“6. The appeal filed by M/sKARAMSAR POULTRY APPLIANCES. GSTIN: 07AAAFK2704M1ZG, BASEMENT, GF, 1ST FLOOR, HOUSE NO 3, BLOCK I SECTOR 3 BAWANA DSIDC. Bawana. New Delhi, North Delhi. Delhi. 110039against Order-In-Original No. ZD070125032348Ldated 08.10.2021is hereby allowed. The impugned order dated 08.10.2021is set aside to the extent of the refund amount wrongly rejected on ground discussed supra. The instant appeal is disposed of in terms of Section 107(11) of CGST Act, 2017.”
7. Thereafter, the Petitioner’s application seeking refund was considered by the Assistant Commissioner, who passed the Impugned Order undertaking a detailed examination of the matter and recording reasons in support of the decision in the following manner:
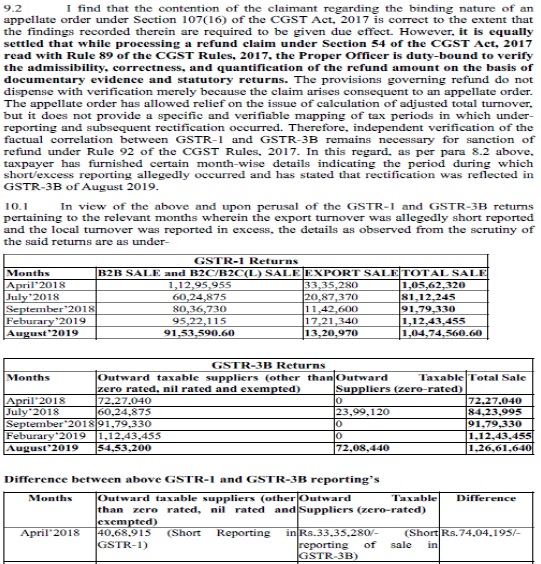
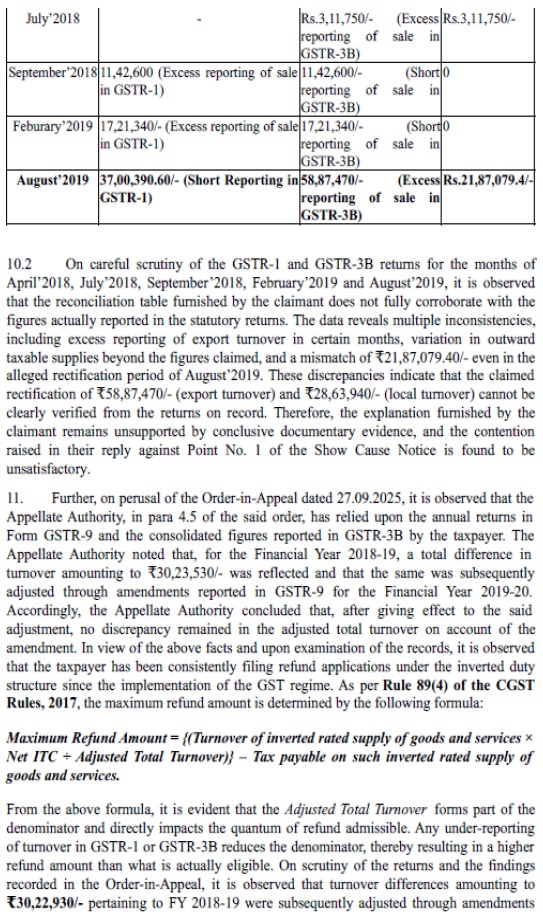
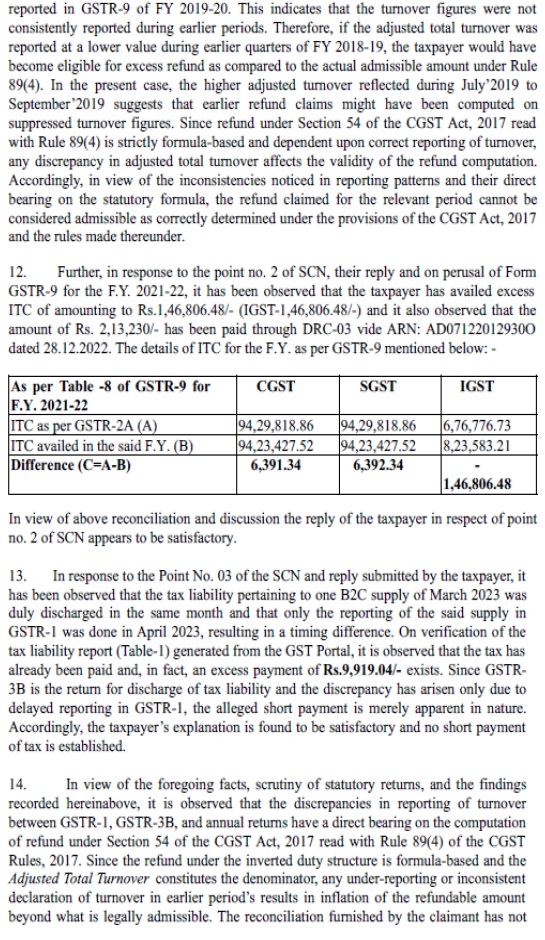
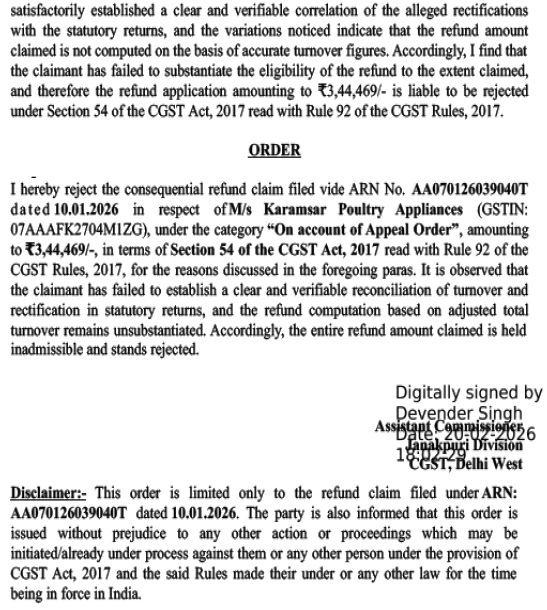
8. Upon perusal of the Impugned Order, it is evident that the Assistant Commissioner has independently examined the Petitioner’s claim for refund and recorded detailed reasons in support of the conclusions arrived at therein.
9. Similarly, a reading of the OIA dated 27.09.2025 reveals that the Appellate Authority merely set aside the rejection of the Petitioner’s refund claim on the grounds which formed the basis of the OIO dated 08.10.2021. Notably, the OIA neither directed unconditional release of the refund amount nor foreclosed examination of the Petitioner’s entitlement on any other legally permissible ground.
10. Consequently, the Assistant Commissioner cannot be said to have been precluded from examining the refund claim afresh on grounds distinct from those which stood negated by the Appellate Authority. Whether such exercise has been validly undertaken or otherwise would necessarily require an examination of the merits of the reasons recorded in the Impugned Order.
11. In the aforesaid backdrop, this Court is prima facie unable to accept that the Impugned Order is non est or wholly without jurisdiction so as to warrant interference in exercise of writ jurisdiction. Admittedly, an Appeal under Section 107 of the Central Goods and Services Tax Act, 2017 lies against the Impugned Order, wherein the legality and correctness of the reasons recorded by the Assistant Commissioner, as also the scope and effect of the OIA dated 27.09.2025, can be comprehensively examined.
12. In such circumstances and having regard to the peculiar facts of the present case, this Court is not inclined to interfere in exercise of its writ jurisdiction. Accordingly, the Petitioner, if so advised, may avail the statutory remedy of Appeal, wherein the Appellate Authority can examine the issues raised before this Court in a comprehensive manner.
13. In view of the aforesaid, the present Writ Petition, along with pending application, is dismissed.
14. Needless to observe that the Petitioner shall be entitled to file an application for exclusion of the time spent prosecuting the present Petition for the purpose of computing the period of limitation.