


Ex-Parte Reassessment and Penalty Orders Remanded to Assessing Officer for De Novo Decision on Merits
Issue
Whether delay in filing the first appeal before the CIT(A) against an ex-parte best-judgment assessment order under Section 144 should be condoned and the quantum and penalty proceedings remanded back to the Assessing Officer for a de novo determination on merits.
Facts
-
Reassessment & Non-Filing: The assessee was a non-filer for AY 2015-16. Reassessment proceedings were initiated under Section 147.
-
Ex-Parte Assessment: Due to non-compliance with statutory notices, the Assessing Officer (AO) completed a best-judgment assessment under Section 144 read with Section 147, making an addition under Section 69A for unexplained money.
-
Penalty Orders: Consequent to the reassessment, the AO levied penalties under Section 271(1)(b) for non-compliance with notices and Section 271(1)(c) for concealment/inaccurate particulars of income.
-
First Appeal Delay: The assessee filed a first appeal under Section 246A against the assessment order with a delay of 163 days.
-
CIT(A) Dismissal: The CIT(A) refused to condone the 163-day delay and dismissed the appeal under Section 250 without adjudicating the dispute on merits.
Decision
-
Condonation of Delay: The 163-day delay in filing the first appeal before the CIT(A) was condoned in the interest of justice, as the ex-parte assessment had not been adjudicated on merits.
-
Remand of Quantum Proceedings: The ex-parte reassessment order under Section 144/147 was set aside, and the quantum matter was remanded back to the file of the Assessing Officer to pass a fresh order on merits after providing a reasonable opportunity to the assessee.
-
Remand of Penalty Proceedings: Since the underlying quantum assessment was restored to the AO for de novo consideration, the penalty orders under Sections 271(1)(b) and 271(1)(c) were also set aside and remanded back to the AO for fresh determination. (Matter remanded)
Key Takeaways
-
Merit-Based Adjudication Preferred: Technical delays in filing appeals against ex-parte best-judgment assessments should be condoned to allow substantive adjudication on merits rather than summary dismissal.
-
Automatic Impact on Consequential Penalties: When a quantum assessment order is set aside and restored for de novo evaluation, linked penalty proceedings under Sections 271(1)(b) and 271(1)(c) must also be set aside and re-evaluated alongside the fresh assessment.
-
Opportunity of Hearing: Reassessment additions made under Section 69A without the assessee’s participation require restoration to the Assessing Officer to enforce principles of natural justice.
IN THE ITAT INDORE BENCH
Dhiraj Singh
v.
Income-tax Officer
PARESH M JOSHI, JUDICIAL MEMBER
and Arvind Soni, ACCOUNTANT MEMBER
and Arvind Soni, ACCOUNTANT MEMBER
IT Appeal No. 816 to 818 (Ind) OF 2025
[Assessment year 2015-16]
[Assessment year 2015-16]
SEPTEMBER 9, 2026
Milind Wadhwani, CA and Ms. Shradha Piplodia, Adv. for the Appellant. Binay Kumar Rai, Sr. DR for the Respondent.
ORDER
Paresh M Joshi, Judicial Member. –
(I) ITA No:- 816/Ind/2025 (Assessment Year:2015-16)
1. This is an Appeal filed by the Assessee under section 253 of the income tax Act 1961,| herein after referred to as the Act for sake of brevity] before this tribunal as and by way of a second appeal. The Assessee is aggrieved by the order bearing no: – ITBA/NFAC/S/250/2025-26/1080777118(1) dated 16.09.2025 passed by the Ld. CIT (A) u/s 250 of the Act, which is herein after referred to as the “Impugned order”. The Relevant Assessment year is 2015-16 and the corresponding previous year period is from 01.04.2014 to 31.03.2015.
2. Factual Matrix
2.1 That as and by way of an Assessment order made u/s 147 rws 144/144B of the Act, the total income of the Assessee was computed & assessed at Rs. 1,31,22,400/-. The Assessee was a non-filer. An addition of Rs. 1,31,22,400/- was made u/s 69A of the Act. That the aforesaid assessment order bears number:-
ITBA/AST/S/147/2022-23/1050223302(1) is dated 28.02.2023 which is hereinafter referred to as the “Impugned Assessment Order” for sake of brevity.
2.2 That the assessee being aggrieved by the aforesaid “Impugned Assessment Order” prefers the first appeal u/s 246A of the Act before the Ld. CIT (A) who by the “Impugned Order” has dismissed the first appeal of the assessee on the grounds and the reasons stated therein. The core grounds and reasons for the dismissal of the first appeal were as under:-
“6. OBSERVATIONS, FINDINGS AND DECISIONS
I have examined the assessment record, the grounds of appeal and the evidence tendered before the AO. It is seen from the records that the appellant has not filed its return of income for Assessment Year 2015-16. The case of the appellant was re- opened u/s. 147 of the I.T.Act, 1961and notice u/s. 148 was issued on 31.03.2022 but the appellant did not file his return of income. The notices u/s. 142(1) of the act was issued number of times but no reply was received. The Assessing Officer proceeded ex-parte and on 28.02.2023, the AO completed a best-judgment assessment under section 144, making an addition of Rs. 1,31,22,400/- on account of unexplained money u/s 69A.
No plausible reason has been given by the appellant for this inordinate delay of 163 days in filing of appeal. Considering the facts of the case, the delay in filing appeal is not condoned. Even on merit also, it is also seen from records that the appellant did not file any reply in response to the various notices issued by the AO. Even during appellate proceedings, the appellant has not furnished any satisfactory reply/documents/evidences to substantiate its claim. In view of the above, / am inclined to agree with the views of the AO and dismiss the appeal.
Conclusion: In the result, the appeal of the appellant is dismissed.”
2.3 That the assessee being aggrieved by the “Impugned Order” has preferred the instant second appeal before this tribunal and has raised the following grounds of appeal in the form no. 36 against the “Impugned Order” which are as under:-
“1. On the facts and circumstances of the case and in law, the reassessment order dated 28.02.2023 is bad in law, without jurisdiction, and liable to be quashed.
2. On the facts and circumstances of the case and in law, the additions were made on mere conjectures, surmises and suspicions.
3. On the facts and circumstances of the case and in law, the reassessment was completed without complying with the statutory requirements of law.
4. On the facts and circumstances of the case and in law, the reassessment order dated 28.02.2023 is contrary to law, facts and circumstances of the case and in any case is opposed to the principles of equity, natural justice and fair play.
5. On the facts and circumstances of the case and in law, the notice under section 148 dated 31.03.2022 is void and illegal hence liable to quashed.
6. On the facts and circumstances of the case and in law, the Hon. NFAC has erred in not issuing the Notice under section 143(2) of the act.
7. On the facts and circumstances of the case and in law, the Ld. AO could not have information suggesting that the income had chargeable to tax escaped assessment in the hands of the appellant.
8. On the facts and circumstances of the case and in law, the Assessment order dated 28.02.2023 is time barred and liable to be quashed.
9. On the facts and circumstances of the case and in law, the Ld. NFAC erred in upholding an addition of Rs. 1,31,22,400/- as a unexplained money u/s. 69A.
10. On the facts and circumstances of the case and in law, the provisions of Section 69A cannot be invoked.
11. On the facts and circumstances of the case and in law, the initiation of penalty proceedings under Sections 271F, 271(1)(C) and 271(1)(b) is bad in law.
12. For that the appellant craves leave to add, amend, alter vary and or withdraw any or all the above grounds of appeal. All the aforesaid grounds are without prejudice to each other.”
3. Record of Hearing
3.1 The hearing in the matter took place before this Tribunal on 17.08.2026 when the Ld. AR for & on behalf of the Assessee appeared before us & interalia contended that the “Impugned Order” is bad in law, illegal & not Proper. It therefore deserves to be set aside.
3.2 The Ld. AR contended that “Impugned Assessment Order” of the Ld. Assessing Officer was ex-parte one and so also the “Impugned Order” of the Ld. CIT (A) is ex-parte in nature. An affidavit dated 29.06.2026 is placed on the record of the assessee which is reproduced by us as below:-
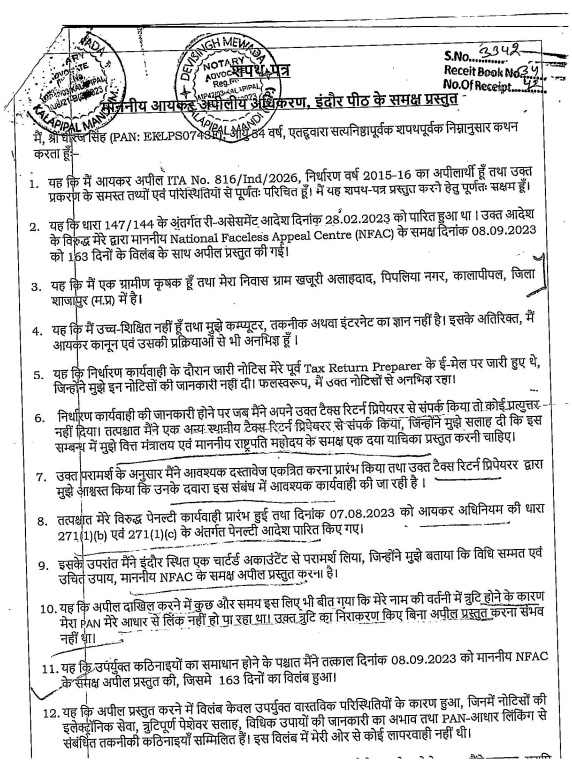
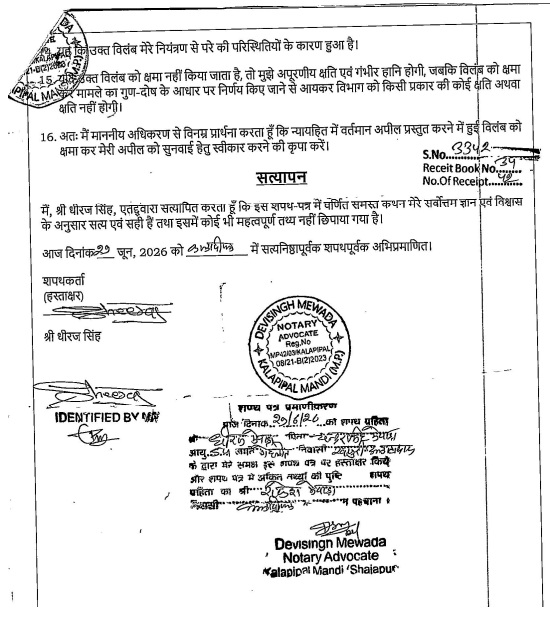
Basis which it was contended that the assessee is a rural farmer in District: – Shajapur of M.P. He is illiterate and does not know computer and has no knowledge of technology and internet. The assessee is not familiar with the Income tax laws. That during the course of the assessment proceedings my “Tax Return preparer” was issued notice(s) on e-mail Id and that he did not inform the assessee about any notice(s) and consequently the assessee was unaware about the notice(s). That after the “Impugned Assessment Order” was passed the assesse “contacted one local tax return preparer” and he advised that the assessee should approach the finance ministry and the President of India for mercy petition. Thereafter basis advise of the “tax return preparer” the assessee collected/ collated the necessary documents and he once again contacted the “tax return preparer” who assured the assessee that suitable steps in this regard is being taken. The assessee thereafter received the Penalty Notice u/s 271(1) (b) and 271 (1)(c) of the Act. Then he contacted a CA at Indore MP who advised basis law the correct remedy is before NFAC [Ld. CIT (A)] by filing an appeal. Thereafter some time elapsed and on account of name spelling defect the assessee’s PAN could not be linked with Aadhar Card and without remedying the said defect it was not possible to prefer appeal. Hence due to above circumstances and facts there was a delay of 163 days in filing the first appeal. After explaining the aforesaid, the Ld. AR contended that due to genuine difficulties and challenges which are narrated by him it would be just, fair, equitable and so also in the interest of the ends of justice that the “Impugned Order” be set aside as sufficient and bonafide cause and reasons are stated on oath in the form of affidavit dated 29.06.2026. The Ld. AR emphasised that the assessee is a farmer, illiterate and little leeway be given in the interest of the ends of justice. The Ld. AR also prayed that liberty be given to him raise all contentions basis law. Per contra the Ld. DR submitted that the assessee though is a farmer ought to have been compliant and vigilant and finally left the issue to the wisdom of this tribunal to take call basis law.
4. Observations Findings & conclusions
4.1 We have to decide the legality, validity and proprietary of the “Impugned Order” basis records of the case & the rival submission canvassed before us.
4.2 We have carefully perused the records of the case and have heard the submissions.
4.3 We basis records of the case & after hearing & further upon examining the rival contentions of the Ld. AR & the Ld. DR canvassed before us are of the considered opinion that the “Impugned Assessment Order” is under section 144 of the Act and that the matter has not been adjudicated and adjudged basis merits. Even the “Impugned Order” is not on merits. This tribunal desires that the total income of the assessee should be computed and assessed on real time basis exigible to tax in accordance with law by following the due process of law under the Act. This tribunal simultaneously expects the assesse to be compliant and that he should cooperate with the department of tax as and when the notice(s) etc. are issued. In brief this tribunal desires the meritorious disposal of both the “Impugned Assessment Order” and “Impugned Order”. The assessee cooperation in this regard assumes importance. The Assessee cannot go in slumber mode. In the result we are of the considered view that the delay before the Ld. CIT (A) be condoned and is accordingly condoned. The “Impugned Order” is set aside and matter is remanded back to the file of the Ld. Assessing Officer for passing a fresh order on merits of the case. It is the expectation of this tribunal that the assessee would give his full and complete details including latest e-mails of his and his counsel/CA where the notice(s) could be served effectively by the department. The assessee is directed to attend hearings as and when fixed and to file the reply’s and other details as sought by the Ld. Assessing Officer.
4.4 In view of the above, we set aside the “Impugned Order” and remand the case back to the file of the Ld. Assessing Officer on de novo basis.
5. Order
5.1 In the result Impugned Order is set aside as and by way of remand back to the file of the Ld. AO on de novo basis.
5.2 The appeal of the Assessee is allowed for statistical purpose.
5.3 (II) ITA No:- 817/Ind/2025 (AY: 2015-16)= Penalty u/s 271 (1) (b) of the Act
The facts and circumstances flows from the Impugned Assessment Order in ITA No:- 816/Ind/2025 , AY : 2015-16, a penalty for non-compliances of notice(s) issued on 29.09.2022, 18.10.2022 and 05.12.2022 of Rs. 30,000/- [143(2)/142(1)] is imposed on the assessee for each default. Since we have set aside the Impugned Order in the ITA No:– 816/Ind/2025 (Supra) our findings therein too would apply mutatis mutandis to this appeal too. Accordingly Impugned Order [Order No: – ITBA/NFAC/S/250/2025-26/1080778311(1) therein dated 16.09.2025 is set aside as and by way of remand to the file of the Ld. Assessing Officer on De novo basis.
5.4 (III) ITA No:- 818/Ind/2025 (AY : 2015-16)= Penalty u/s 271(1)(c) of the Act
In this case too facts and circumstances flows from the Impugned Assessment Order in ITA No:- 816/Ind/2025 , AY : 2015-16 and a penalty of Rs. 44,60,304/- is imposed on the assessee for concealment of income u/s 271(1)(c) of the Act. Since we have set aside the Impugned Order in ITA No: – 816/Ind/2025 (Supra). Our findings therein too would apply mutatis mutandis to this appeal too. Accordingly the Impugned Order [Order No:- ITBA/NFAC/ S/ 250/2025- 26/1080777851(1)] therein dated 16.09.2025 is set aside as and by way of remand back to the file of the Ld. Assessing Officer on De novo basis.
5.5 In the result all the above appeals are allowed for statistical purpose back to the file of the Ld. AO as aforesaid.
5.6 The appeals are allowed for statistical purpose. .
Milind Wadhwani, CA and Ms. Shradha Piplodia, Adv. for the Appellant. Binay Kumar Rai, Sr. DR for the Respondent.
ORDER
Paresh M Joshi, Judicial Member. –
(I) ITA No:- 816/Ind/2025 (Assessment Year:2015-16)
1. This is an Appeal filed by the Assessee under section 253 of the income tax Act 1961,| herein after referred to as the Act for sake of brevity] before this tribunal as and by way of a second appeal. The Assessee is aggrieved by the order bearing no: – ITBA/NFAC/S/250/2025-26/1080777118(1) dated 16.09.2025 passed by the Ld. CIT (A) u/s 250 of the Act, which is herein after referred to as the “Impugned order”. The Relevant Assessment year is 2015-16 and the corresponding previous year period is from 01.04.2014 to 31.03.2015.
2. Factual Matrix
2.1 That as and by way of an Assessment order made u/s 147 rws 144/144B of the Act, the total income of the Assessee was computed & assessed at Rs. 1,31,22,400/-. The Assessee was a non-filer. An addition of Rs. 1,31,22,400/- was made u/s 69A of the Act. That the aforesaid assessment order bears number:-
ITBA/AST/S/147/2022-23/1050223302(1) is dated 28.02.2023 which is hereinafter referred to as the “Impugned Assessment Order” for sake of brevity.
2.2 That the assessee being aggrieved by the aforesaid “Impugned Assessment Order” prefers the first appeal u/s 246A of the Act before the Ld. CIT (A) who by the “Impugned Order” has dismissed the first appeal of the assessee on the grounds and the reasons stated therein. The core grounds and reasons for the dismissal of the first appeal were as under:-
“6. OBSERVATIONS, FINDINGS AND DECISIONS
I have examined the assessment record, the grounds of appeal and the evidence tendered before the AO. It is seen from the records that the appellant has not filed its return of income for Assessment Year 2015-16. The case of the appellant was re- opened u/s. 147 of the I.T.Act, 1961and notice u/s. 148 was issued on 31.03.2022 but the appellant did not file his return of income. The notices u/s. 142(1) of the act was issued number of times but no reply was received. The Assessing Officer proceeded ex-parte and on 28.02.2023, the AO completed a best-judgment assessment under section 144, making an addition of Rs. 1,31,22,400/- on account of unexplained money u/s 69A.
No plausible reason has been given by the appellant for this inordinate delay of 163 days in filing of appeal. Considering the facts of the case, the delay in filing appeal is not condoned. Even on merit also, it is also seen from records that the appellant did not file any reply in response to the various notices issued by the AO. Even during appellate proceedings, the appellant has not furnished any satisfactory reply/documents/evidences to substantiate its claim. In view of the above, / am inclined to agree with the views of the AO and dismiss the appeal.
Conclusion: In the result, the appeal of the appellant is dismissed.”
2.3 That the assessee being aggrieved by the “Impugned Order” has preferred the instant second appeal before this tribunal and has raised the following grounds of appeal in the form no. 36 against the “Impugned Order” which are as under:-
“1. On the facts and circumstances of the case and in law, the reassessment order dated 28.02.2023 is bad in law, without jurisdiction, and liable to be quashed.
2. On the facts and circumstances of the case and in law, the additions were made on mere conjectures, surmises and suspicions.
3. On the facts and circumstances of the case and in law, the reassessment was completed without complying with the statutory requirements of law.
4. On the facts and circumstances of the case and in law, the reassessment order dated 28.02.2023 is contrary to law, facts and circumstances of the case and in any case is opposed to the principles of equity, natural justice and fair play.
5. On the facts and circumstances of the case and in law, the notice under section 148 dated 31.03.2022 is void and illegal hence liable to quashed.
6. On the facts and circumstances of the case and in law, the Hon. NFAC has erred in not issuing the Notice under section 143(2) of the act.
7. On the facts and circumstances of the case and in law, the Ld. AO could not have information suggesting that the income had chargeable to tax escaped assessment in the hands of the appellant.
8. On the facts and circumstances of the case and in law, the Assessment order dated 28.02.2023 is time barred and liable to be quashed.
9. On the facts and circumstances of the case and in law, the Ld. NFAC erred in upholding an addition of Rs. 1,31,22,400/- as a unexplained money u/s. 69A.
10. On the facts and circumstances of the case and in law, the provisions of Section 69A cannot be invoked.
11. On the facts and circumstances of the case and in law, the initiation of penalty proceedings under Sections 271F, 271(1)(C) and 271(1)(b) is bad in law.
12. For that the appellant craves leave to add, amend, alter vary and or withdraw any or all the above grounds of appeal. All the aforesaid grounds are without prejudice to each other.”
3. Record of Hearing
3.1 The hearing in the matter took place before this Tribunal on 17.08.2026 when the Ld. AR for & on behalf of the Assessee appeared before us & interalia contended that the “Impugned Order” is bad in law, illegal & not Proper. It therefore deserves to be set aside.
3.2 The Ld. AR contended that “Impugned Assessment Order” of the Ld. Assessing Officer was ex-parte one and so also the “Impugned Order” of the Ld. CIT (A) is ex-parte in nature. An affidavit dated 29.06.2026 is placed on the record of the assessee which is reproduced by us as below:-
Basis which it was contended that the assessee is a rural farmer in District: – Shajapur of M.P. He is illiterate and does not know computer and has no knowledge of technology and internet. The assessee is not familiar with the Income tax laws. That during the course of the assessment proceedings my “Tax Return preparer” was issued notice(s) on e-mail Id and that he did not inform the assessee about any notice(s) and consequently the assessee was unaware about the notice(s). That after the “Impugned Assessment Order” was passed the assesse “contacted one local tax return preparer” and he advised that the assessee should approach the finance ministry and the President of India for mercy petition. Thereafter basis advise of the “tax return preparer” the assessee collected/ collated the necessary documents and he once again contacted the “tax return preparer” who assured the assessee that suitable steps in this regard is being taken. The assessee thereafter received the Penalty Notice u/s 271(1) (b) and 271 (1)(c) of the Act. Then he contacted a CA at Indore MP who advised basis law the correct remedy is before NFAC [Ld. CIT (A)] by filing an appeal. Thereafter some time elapsed and on account of name spelling defect the assessee’s PAN could not be linked with Aadhar Card and without remedying the said defect it was not possible to prefer appeal. Hence due to above circumstances and facts there was a delay of 163 days in filing the first appeal. After explaining the aforesaid, the Ld. AR contended that due to genuine difficulties and challenges which are narrated by him it would be just, fair, equitable and so also in the interest of the ends of justice that the “Impugned Order” be set aside as sufficient and bonafide cause and reasons are stated on oath in the form of affidavit dated 29.06.2026. The Ld. AR emphasised that the assessee is a farmer, illiterate and little leeway be given in the interest of the ends of justice. The Ld. AR also prayed that liberty be given to him raise all contentions basis law. Per contra the Ld. DR submitted that the assessee though is a farmer ought to have been compliant and vigilant and finally left the issue to the wisdom of this tribunal to take call basis law.
4. Observations Findings & conclusions
4.1 We have to decide the legality, validity and proprietary of the “Impugned Order” basis records of the case & the rival submission canvassed before us.
4.2 We have carefully perused the records of the case and have heard the submissions.
4.3 We basis records of the case & after hearing & further upon examining the rival contentions of the Ld. AR & the Ld. DR canvassed before us are of the considered opinion that the “Impugned Assessment Order” is under section 144 of the Act and that the matter has not been adjudicated and adjudged basis merits. Even the “Impugned Order” is not on merits. This tribunal desires that the total income of the assessee should be computed and assessed on real time basis exigible to tax in accordance with law by following the due process of law under the Act. This tribunal simultaneously expects the assesse to be compliant and that he should cooperate with the department of tax as and when the notice(s) etc. are issued. In brief this tribunal desires the meritorious disposal of both the “Impugned Assessment Order” and “Impugned Order”. The assessee cooperation in this regard assumes importance. The Assessee cannot go in slumber mode. In the result we are of the considered view that the delay before the Ld. CIT (A) be condoned and is accordingly condoned. The “Impugned Order” is set aside and matter is remanded back to the file of the Ld. Assessing Officer for passing a fresh order on merits of the case. It is the expectation of this tribunal that the assessee would give his full and complete details including latest e-mails of his and his counsel/CA where the notice(s) could be served effectively by the department. The assessee is directed to attend hearings as and when fixed and to file the reply’s and other details as sought by the Ld. Assessing Officer.
4.4 In view of the above, we set aside the “Impugned Order” and remand the case back to the file of the Ld. Assessing Officer on de novo basis.
5. Order
5.1 In the result Impugned Order is set aside as and by way of remand back to the file of the Ld. AO on de novo basis.
5.2 The appeal of the Assessee is allowed for statistical purpose.
5.3 (II) ITA No:- 817/Ind/2025 (AY: 2015-16)= Penalty u/s 271 (1) (b) of the Act
The facts and circumstances flows from the Impugned Assessment Order in ITA No:- 816/Ind/2025 , AY : 2015-16, a penalty for non-compliances of notice(s) issued on 29.09.2022, 18.10.2022 and 05.12.2022 of Rs. 30,000/- [143(2)/142(1)] is imposed on the assessee for each default. Since we have set aside the Impugned Order in the ITA No:– 816/Ind/2025 (Supra) our findings therein too would apply mutatis mutandis to this appeal too. Accordingly Impugned Order [Order No: – ITBA/NFAC/S/250/2025-26/1080778311(1) therein dated 16.09.2025 is set aside as and by way of remand to the file of the Ld. Assessing Officer on De novo basis.
5.4 (III) ITA No:- 818/Ind/2025 (AY : 2015-16)= Penalty u/s 271(1)(c) of the Act
In this case too facts and circumstances flows from the Impugned Assessment Order in ITA No:- 816/Ind/2025 , AY : 2015-16 and a penalty of Rs. 44,60,304/- is imposed on the assessee for concealment of income u/s 271(1)(c) of the Act. Since we have set aside the Impugned Order in ITA No: – 816/Ind/2025 (Supra). Our findings therein too would apply mutatis mutandis to this appeal too. Accordingly the Impugned Order [Order No:- ITBA/NFAC/ S/ 250/2025- 26/1080777851(1)] therein dated 16.09.2025 is set aside as and by way of remand back to the file of the Ld. Assessing Officer on De novo basis.
5.5 In the result all the above appeals are allowed for statistical purpose back to the file of the Ld. AO as aforesaid.
5.6 The appeals are allowed for statistical purpose. .