


Unrelated Parties’ Royalty Agreement Cannot Be Subjected to Transfer Pricing Adjustments or Section 37(1) Benchmarking
Issue
Whether royalty paid by a resident assessee to an unrelated foreign entity under an arms-length trademark license agreement can be subjected to transfer pricing adjustments under Section 92A or disallowed as excessive under Section 37(1).
Facts
-
Agreement & Transaction: The assessee entered into a trademark license agreement with One Plus Technology (Shenzhen) Co. Ltd. (OPT) to use its trademarks for promoting, advertising, and selling TVs/accessories in exchange for a 7% royalty on sales.
-
Absence of Related-Party Status: OPT was not declared or established as a related party or Associated Enterprise (AE) in the financial statements or in filings before tax authorities.
-
AO’s Transfer Pricing Invocations: The Assessing Officer (AO) invoked Section 92A(1)(g), alleging that the assessee’s business was dependent on OPT’s intangibles, thereby treating it as a deemed international transaction between AEs.
-
AO’s Section 37(1) Disallowance: The AO separately benchmarked the royalty rate at 5% using external databases and disallowed the 2% excess under Section 37(1) as excessive expenditure.
-
Lack of Independent Evidence: Revenue authorities brought no evidence or prior third-party arrangement on record to establish that the transaction was structured to bypass transfer pricing rules under deemed AE provisions.
Decision
-
Transfer Pricing Adjustments Impermissible [Section 92A]: Held in favour of the assessee. In the absence of proof establishing an Associated Enterprise relationship under Section 92A, transfer pricing provisions cannot be invoked; the transaction must be treated as an independent third-party transaction [Paras 12 and 13].
-
No Benchmarking of Independent Contracts under Section 37(1): Held in favour of the assessee. The AO cannot use Section 37(1) to benchmark or rewrite commercial royalty rates agreed upon between independent contracting parties in a bona fide agreement [Para 14].
Key Takeaways
-
AE Relationship Is a Mandatory Prerequisite: Transfer pricing rules under Section 92A/92C apply strictly to Associated Enterprises; tax authorities cannot reclassify independent third-party contracts without establishing an explicit statutory AE connection.
-
Evidentiary Burden for Deemed AEs: To invoke deemed AE provisions, the Revenue must provide concrete evidence showing a prior agreement or specific triangular arrangement involving an independent party to circumvent transfer pricing provisions.
-
No Commercial Expediency Benchmarking under Section 37(1): Tax authorities cannot evaluate the reasonableness or excessiveness of payments made between unrelated, independent entities under Section 37(1).
IN THE ITAT DELHI BENCH ‘H’
Mobitech Creations (P.) Ltd.
v.
DCIT
Vimal Kumar, Judicial Member
and S. Rifaur Rahman, Accountant Member
and S. Rifaur Rahman, Accountant Member
IT Appeal No.1005 (DEL) of 2025
[Assessment year 2021-22]
[Assessment year 2021-22]
AUGUST 21, 2026
Aseem Chawla, Sr. Adv., Jasmeet Singh, Pranav Menon and Ms. Pratishtha Chaudhary, Advs. for the Appellant. Bhopal Singh, CIT DR for the Respondent.
ORDER
S. Rifaurrahman, Accountant Member.- This appeal filed by the assessee is directed against the order of ld. Commissioner of Income-tax (Appeals)-30, New Delhi [for short ‘ld. CIT (A)’] dated 27.12.2024for the Assessment Year 2021-22. The assessee has filed grounds of appeal and also filed additional grounds of appeal before us, the additional grounds raised by the assessee are reproduced below:-
| i. | That on the facts and circumstances of the case and in law, the Ld. CIT(A) erred in sustaining the Assessment Order and has disregarded the fact that the Appellant does not qualify the criteria of “Associated Enterprise” as prescribed under Section 92A of the Act. |
| ii. | That on the facts and circumstances of the case and in law, the Ld. CIT(A) has erred in sustaining the Assessment Order without considering that the alleged underlying transaction of payment made towards royalty amounting to Rs.36,35,75,663/-, does not qualify as “International Transaction” under Section 92B of the Act. |
| iii. | That, on the facts and circumstances of the case and in law, the Ld. CIT(A) has erred in sustaining the Impugned Assessment Order, passed without adhering the due compliance of making mandatory reference to the Transfer Pricing Officer (TPO) in terms of section 92CA of the Act. |
| iv. | That, without prejudice to the above, on the facts of the case and in law, the Ld. CIT(A) has erred in upholding the Assessment Order without appreciating the provisions of section 92C of the Act, providing for a tolerance limit on ± % to’ any variation between Arm’s Length Price (ALP) so determined and price at which international transaction was undertaken. |
| v. | Without prejudice to the above, that on the facts of the case and in law, the Ld. CIT(A) erred in sustaining the Assessment Order by not considering the settled position oflaw that payment made towards Royalty by the Appellant to One Plus Technologies (Shenzhen) Co. Ltd. does not constitute as “Capital Expenditure” & thereby ought to be allowed as Business Expenditure under section 37(1) of the Act, for the purpose of computing Total Income chargeable to tax. |
| vi. | That as per the facts and circumstances of the case and in law, the Ld. CIT(A) has grossly erred in passing the Impugned Order ex-parte without providing reasonable opportunity of being heard and the same is in violation of mandatory principles of natural justice requiring adherence. |
| vii. | That as per the facts and circumstances of the case and in law, the Assessment Order & the Impugned Order passed by the Ld. CIT(A), are laconic, cryptic and passed without independent application of mind, and ex-facie bad in law and thus liable to be quashed. |
2. After considering the rival submissions and material placed on record by both the parties. We observed that the issues raised by the assessee in the above additional grounds go to the root of the matter challenging the jurisdictional issue. In the light of Hon’ble Supreme Court in the case of NTPC Limited v. CIT229 ITR 383 (SC), we are inclined to admit the additional grounds and take up the same for adjudication herein below and adjudicate the same as under.
3. We proceeded to adjudicate additional grounds no.1 to 5 only based on the detailed submissions made before us, the relevant facts are, the assessee filed its original return of income on 28.12.2020 declaring income of Rs.62,00,72,894/-. A search and seizure operation under section 132 of the Income-tax Act, 1961 (for short ‘the Act’) was conducted on 21.12.2021 in the case of the assessee along with the other cases of Oppo Mobile India Group at various residential and business premises. Accordingly, notices u/s 143(2) was issued and in response, assessee filed return of income dated 15.02.2022. Further notices were issued to the assessee u/s 142(1). Assessee has responded to various notices except notices issued on 30.01.2023 and 31.01.2023.
4. During the assessment proceedings, assessee was asked to produce details of transaction with One Plus Technology (Shenzhen) Co. Ltd. (OPT) amounting to Rs.36,35,75,663/- which was debited in the Profit & Loss account along with relevant documents. In response, assessee submitted that assessee has entered into agreement with OPT for the use of trade marks for promotion, advertisement and sale of TV in consideration of royalty payment. Assessee also enclosed an invoice dated 26.03.2021 and also enclosed copy of the relevant agreement. After considering agreements submitted by the assessee and by relying on the statement of Vikram Jain who stated that the assessee is the sole distributor of the One Plus TV and accessories. Further, it was stated that assessee is also distributor of One Plus Handsets and other accessories in India, the royalty payments are made solely on the sale of One Plus TV and other accessories. Assessee being sole distributor and also one of the main distributors, the royalty has been paid on account of use of design, software and produce know-how. Based on the above statement, the Assessing Officer observed that as per section 92A(1)(g) defines the ‘Associated Enterprises’ in relation to other enterprises means whether “as the manufacture or processing of goods or articles or business carried out by one enterprise is wholly dependent on the use of know-how, patents, copyrights, trade-marks, licences, franchises or any other business or commercial rights of similar nature, or any data, documentation, drawing or specification relating to any patent, invention, model, design, secret formula or process, of which the other enterprise is the owner or in respect of which the other enterprises has exclusive rights.” He observed that in the present case, the sales of TV segment of the assessee are based on drawing or specifications relating to any patent, invention, model, design, secret formula or process of OPT. The same was confronted with Mr. Vikram Jain and AO has reproduced the extract of the statement in the assessment order. The Assessing Officer observed from the above statement that as stated by Vikram Jain himself, royalty payments were made by the assessee inspite of being a distributor and not a manufacturer (instead of M/s. Skyworth India Electronics Pvt. Ltd.) on account of the former being ‘Exclusive Seller and Distributor” of OPT in the territory of India in the year under consideration. Further, the same exclusive distributorship transferred to M/s. OMIPL. In light of the above, the royalty payments made on sale of TV and other accessories belong to One Plus brand in India constitutes international transaction.
5. The Assessing Officer proceeded to benchmark the transaction of royalty payment and observed that it is excessive or unreasonable compared to the ALP of the royalty payments made by the comparables. He proceeded to make independent verification on royalty stat database to compare the comparables made by other business entities and the results, gathered of the information are as under :-
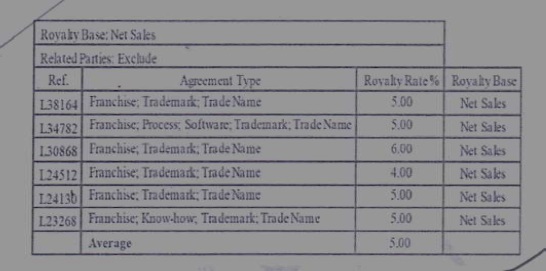
6. Since assessee has paid royalty payment which is equivalent to 7% of its sales during the year, as the comparable figures of royalty rate are found to be 5%, he found that the payment of royalty is excessive. Accordingly, he proceeded to disallow the difference as unexplained bogus expense on account of royalty payment to the extent of Rs.10,38,78,761/-.
7. Aggrieved with the above order, assessee preferred an appeal before the ld. CIT (A)-30, New Delhi. During appellate proceedings, several notices were issued to the assessee and since no compliance from the assessee, he proceeded to dispose off the appeal on the basis of material already available on record. Based on the material available on record, ld. CIT(A) dismissed the appeal filed by the assessee by sustaining the additions made in the assessment order.
8. Aggrieved against the aforesaid order, assessee is in appeal before us.
9. At the time of hearing, ld. AR of the assessee brought to our notice the findings of the AO in the assessment order and the facts from the details submitted during the assessment proceedings. He brought to our notice page 42 to 48 of the assessment order and submitted that the AO himself proceeded to bench the mark the international transaction with the wrong understanding of facts. He further brought to our notice page 291 of the paper book and submitted that the assessee had clearly explained to the AO that the assessee is exclusive authorised distributor of one plus TV and other accessories, the OPT is not the related or associated enterprise. Further he brought to our attention page 246 of the paper book, which is the notes to account for disclosure of related party transactions, in which there is no reference to the OPT as related party transactions. Further he also brought to our attention page 167 of the paper book, which the relevant agreement with the OPT, it is license agreement between the assessee and OPT for use the mark(s) in connection with promotion, advertisement and sale of TV in India. The assessee had very categorically stated to the AO that it is not falling under the TP provisions for the reason that it is not with the associated enterprise. Accordingly, he submitted that the additions proposed by the AO are not proper and justified.
10. On the other hand, ld. DR of the Revenue brought to our notice relevant facts on record and submitted that since no compliance made by the assessee before the ld. CIT (A). He relied on the findings of the lower authorities. Further ld. DR of the Revenue submitted the written submissions which are placed on record and the same is reproduced below :-
“1. Background of the Case:
The assessee filed its return of income u/s 139(1) on 28.12.2020 declaring total income of Rs.62,00,72,894/-. A search and seizure operation u/s 132 of the Income-tax Act, 1961 was conducted on 21.12.2021 in the group cases, including that of the assessee. Subsequently, the case was centralized to Central Circle-30, Delhi, and selected for scrutiny assessment. Statutory notices u/s 143(2) and 142(1) were issued from time to time. The details of compliance clearly indicate that though partial responses were filed initially, the assessee failed to furnish complete details, particularly in respect of the issue of royalty payment. Further, no response was filed to the final show cause notice dated 31.01.2023.
2. Issue under Consideration:
The primary issue involved in the present appeal relates to disallowance of Rs.10,38,78,761/- out of royalty expenditure claimed by the assessee u/s 37 of the Act.
3. Facts and Examination by AO:
The assessee debited royalty expenditure of Rs.36,35,75,663/- in its Profit & Loss Account. The royalty was paid to M/ s One Plus Technology (Shenzhen) Co. Ltd. @ 7% of net sales for use of trademarks and related rights in respect of TV and related accessories. As stated by Sh. Vikram Jain, M/s Mobitech Creations Pvt Ltd was the sole distributor of the Oneplus TV, TV walmounts, TV stands and related TV accessories. Further, though M/s Mobitech Creations Pvt Ltd was also the distributor of Oneplus handsets, spare parts and accessories in India, the royalty payments were made solely on the sales of Oneplus TV, TV wall-mounts, TV stands and related tv accessories to M/s One Plus Technology (Shenzhen) Co Ltd which showed that the treatment of the transactions of M/s Mobitech Creations Pvt Ltd with M/s OnePlus Technology (Shenzhen) Co Ltd concerning the sales of Oneplus TV was different, the Company being the sole distributor of this segment of electronics, as compared to Oneplus handsets, spare parts and accessories wherein M/s Mobitech Creations Pvt Ltd was one of the many distributors. Royalty was paid on account of use of “design, software and product know how” as submitted by Sh. Vikram Jain. During assessment proceedings, the assessee was specifically required to furnish:
| • | Copy of agreement along with annexures |
| • | Basis of royalty computation |
| • | Comparable uncontrolled transactions |
| • | Evidence of services/benefits received |
| • | Justification of royalty rate |
However, the assessee failed to furnish complete documentary evidence to substantiate:
| • | Arm’s length nature of royalty payment |
| • | Basis for adopting 7% rate |
| • | Functional comparability |
4. Determination of Arm’s Length Price:
As stated by Sh. Vikram Jain himself royalty payments were made by M/s Mobitech Creations Pvt Ltd inspite of being a distributor and not a manufacturer (instead of M/s Skyworth India Electronics Pvt Ltd) on account of the former being “Exclusive Seller and Distributer” of Oneplus TV, TV wall-mounts, TV stands and related tv accessories in the territory of India in FY 2020-21. After the same the exclusive distributorship was transferred to M/s OMIPL. In light of the above the royalty payments made on sales of TV, TV mounts and accessories belonging to Oneplus Brand in India amounting to a total of Rs.36,35,75,663/- constitutes international transaction. Expenditure made in the nature of royalty payments for FY 2020-21 by M/s Mobitech Creations Pvt Ltd towards M/s OnePlus Technology (Shenzhen) Co Ltd is excessive or unreasonable compared to the Arm’s length pricing of the royalty payments made by the Comparables. For this, an independent verification was conducted on Royalty Stat database to cull out the comparables transactions made by other business entities and the results gathered therefrom have been tabulated hereunder. It being seen that there are various comparable to M/s Mobitech Creations Pvt Ltd wherein Royalty or similar amounts have been paid. It is on record that during the year FY 2020-21, M/s Mobitech Creations Pvt Ltd has debited an amount of Rs.36,35,75,663/- as Royalty in its books of accounts which is equivalent to 7% of its sales (on which royalty has been paid) during the year. However as per comparable search process the comparable figures of Royalty Rate are found to be 5% only. M/s MobitechCreations Pvt Ltd has definitely debited an exorbitant amount in the name of Royalty. Independent benchmarking was conducted using RoyaltyStat database. Comparable agreements of similar nature indicated an average royalty rate of 5%. The assessee did not submit any contrary benchmarking analysis or justification for higher rate of 7%. Thus, the excess royalty payment of 2% of net sales was considered excessive and unreasonable.
5. Legal Position:
| • | As per Section 37(1), only those expenses which are wholly and exclusively incurred for business purposes and are reasonable are allowable. |
| • | Further, in case of international transactions involving associated enterprises, the arm’s length principle is applicable. |
| • | The assessee failed to demonstrate that payment beyond 5% was justified or at arm’s length. |
6. Opportunity of Being Heard:
Multiple opportunities were provided through notices u/s 142(1). A specific show cause notice dated 31.01.2023 was issued clearly confronting the proposed disallowance. Despite this, the assessee:
| • | Did not file complete reply |
| • | Did not furnish supporting evidence |
| • | Only submitted general explanation without substantiation |
Hence, adequate opportunity was duly provided in line with principles of natural justice.
7. Findings of CIT(A):
Aggrieved by the assessment order passed by the AO, the assessee filed by appeal before the Ld. CIT(A) wherein the appeal of assessee has been dismissed by the Ld. CIT(A) by holding that the assessee’s responses were incomplete and failed to provide substantive evidence or alternate computations. The Ld. CIT(A) also held that the assessee sought several adjournments and did not file any substantial submissions during the appellate stage, demonstrating a lack of cooperation. The Ld. CIT(A), after considering the facts, upheld the addition on the following grounds:
| • | Failure of the assessee to provide substantive evidence. |
| • | Lack of cooperation during appellate proceedings. |
| • | No alternate benchmarking or computation submitted. |
8. Comments on Grounds Raised by assessee before Hon’ble ITAT:
Aggrieved by the order of Ld. CIT(A), the assessee filed further appeal before the Hon’ble ITAT. The grounds of appeal raised by the assessee and the comments of AO are as under:
Ground No.1:
That the assessment order passed by Ld. AO u/s 143(3) is bad in law.
Comments of the AO:
The contention of the assessee is incorrect and denied. The assessment order has been passed strictly in accordance with the provisions of the Income-tax Act, 1961. The case was selected for scrutiny following a search and seizure operation u/s 132, and thereafter centralized as per due procedure. Statutory notices u/s 143 (2) and 142 (1) were duly issued and served upon the assessee. Adequate opportunities were provided during the course of assessment proceedings. Therefore, the assessment order passed u/s 143(3) is legally valid and not bad in law.
Ground No.2:
That the Ld. AO arbitrarily computed the arm length price @ 5% of net sales of TV, TV Stands, TV Walls-Mount and related TV Accessories as compared to actual royalty paid @ 7% of net sales. And thus, without application of mind disallowed differential amount of Rs.10,38,78,761/-.
Comments of AO:
The allegation that the arm’s length price (ALP) was computed arbitrarily is factually incorrect. The ALP was determined based on independent benchmarking analysis using reliable external data sources (RoyaltyStat database). Comparable uncontrolled transactions of similar nature were identified and analyzed, which reflected an average royalty rate of 5%.
The assessee, despite being given multiple opportunities, failed to furnish:
| • | Any Transfer Pricing study or benchmarking analysis. |
| • | Justification for charging royalty @ 7%. |
| • | Comparable agreements supporting higher rate. |
In absence of any contrary evidence, the determination of ALP @ 5% is reasonable, scientific, and in accordance with accepted transfer pricing principles. Hence, the disallowance of excess royalty of Rs.10,38,78,761/- is justified.
Ground No.3:
That the Ld. AO did not consider the fact that the royalty paid for the trademark of M/s One Plus Technology (Shenzhen) company limited is incomparable.
Comments of AO:
This ground is not tenable. The assessee has merely made a general claim that its royalty transaction is incomparable without providing any supporting documentation or analysis. No evidence was submitted to demonstrate:
| • | Unique nature of transaction. |
| • | Exclusive rights justifying higher royalty. |
| • | Functional differences warranting deviation from comparables. |
On the contrary, the AO conducted a detailed comparability analysis based on available data. In absence of any substantiated claim from the assessee, the benchmarking carried out by the AO remains valid. Mere assertion without evidence cannot be accepted.
Ground No.4:
That the show cause notice dated 31.01.2023 was issued with the compliance due date 03.02.2023. In response of which the appellant submitted its reply and requested additional time for submission of remaining point. However, the Ld. AO did not provide adequate opportunity to the appellant to provide the justification against proposed disallowance.
Comments of AO:
The contention of the assessee is strongly denied. The records clearly indicate that:
| • | Multiple notices u/s 142(1) were issued on various dates. |
| • | The assessee complied partially on several occasions. |
| • | A specific show cause notice dated 31.01.2023 was issued clearly outlining the proposed disallowance. |
Despite this, the assessee:
| • | Failed to submit complete details. |
| • | Did not furnish required supporting evidence. |
| • | Did not file any substantive reply to the show cause notice. |
It is pertinent to note that sufficient and reasonable opportunities were provided throughout the assessment proceedings. The assessee’s failure to utilize these opportunities cannot be attributed to the Assessing Officer. Therefore, principles of natural justice have been duly complied with.
Ground No.5:
That the Appellant craves leave to add amend alter withdraw any ground of appeal anytime up to the hearing of this appeal.
Comments of AO:
This ground is general in nature and does not call for any specific comments at this stage.
9. Conclusion:
| ■ | The assessee failed to discharge its onus of substantiating the royalty expenditure. |
| ■ | The disallowance was made based on reasonable benchmarking and available material. |
| ■ | The order of the Ld. CIT(A) is well reasoned and requires no interference. |
In view of the above facts and circumstances, it is humbly submitted that the addition of Rs.10,38,78,761/- made by the Assessing Officer and upheld by the Ld. CIT(A) may kindly be sustained.
11. Considered the rival submissions and material placed on record. We observed that the AO noticed that the assessee had paid royalty payments to OPT during the year and claimed the expenditure in its profit and loss account. He observed that the assessee has obtained exclusive right to sell the OPPO TV and other accessories and came to the conclusion that the assessee being distributor, instead of manufacturer, paid the royalty, which falls under the international transaction, hence he proceeded to bench the mark the same. We noticed that the AO had not invoked any of the transfer pricing provisions to bench mark the transaction rather he proceeded to bench mark the transaction u/s 37 of the Act. He proceeded with the wrong assumption that the above transaction falls under deemed associated concern considering the transactions with the assessee and OPT. The AO was of the view that the payment of royalty is in higher side and proceeded to compare the same utilising the royalty stat database.
12. After considering the facts on record, we are of the view that the licensor OPT is not the related concern, as we noticed that the licensor was never declared as related party anywhere in the financial statement or in any of the communication submitted before the tax authorities. Once the parties are not related, there is no scope for invoking the transfer pricing provisions in the case, the relevant transaction can only be considered as independent third-party transaction, hence no transfer pricing adjustments can be made. The transfer pricing laws test whether transactions between related parties match with the market rate i.e., uncontrolled prices. The independent transactions do not carry the presumption of profit shifting or tax evasion. This can only be treated as independent business transactions which will be independently assessed to tax in the other country, the TP provisions have no application.
13. Unless the tax authorities prove that the transaction falls under deemed associated enterprises by bringing on record a transaction through an independent third party via a prior agreement or specific arrangement to bypass transfer pricing rules. In the given case, no such independent material was brought on record to make this transaction fall under the deemed associated enterprise.
14. Since the AO had only invoked the provisions of the section 37 to make the adjustment that the rate of payment of royalty is excessive, there are no provisions in the Act to justify the transaction entered by the two independent parties, whether they are resident or non-residents. We noticed that the transaction entered by the assessee with the OPT is independent and two contracting parties agreed under the Bonafide license agreement to collect/pay royalty between them, the revenue has no role to play or disturb the above transactions. Therefore, we are inclined to allow the additional grounds raised by the assessee.
15. The other issues raised in the additional grounds and other grounds of appeal are not adjudicated at this stage and the same are kept open.
16. In the result, the appeal filed by the assessee is allowed in above terms.