


Failure to Issue Section 143 Notice and Unsubstantiated Section 68 Addition Invalidates Reassessment Order
Issue
-
Whether a reassessment completed under Section 147 without issuing a mandatory notice under Section 143(2), after the assessee filed a return in response to a Section 148 notice, is bad in law and liable to be quashed ab initio.
-
Whether an addition made under Section 68 for alleged accommodation entries can be sustained solely on Investigation Wing information and third-party search statements, without providing cross-examination, conducting independent inquiry, or rebutting documentary evidence of genuine loan repayment.
Facts
-
Reassessment Issue (Section 143/147):
-
For Assessment Year 2010-11, the Assessing Officer (AO) issued a notice under Section 148 reopening the assessment.
-
The assessee filed its return of income in response to the Section 148 notice.
-
The AO proceeded to complete the reassessment without issuing any notice under Section 143(2).
-
-
Unsecured Loans Issue (Section 68):
-
Based on search information from the Investigation Wing alleging that the assessee received accommodation entries of Rs. 2 crores from two parties (Rs. 1 crore each), the AO reopened the assessment.
-
The assessee requested copies of the underlying material relied upon and an opportunity to cross-examine the third parties whose statements were used against it.
-
The AO did not provide the requested material, denied cross-examination, and failed to issue summons or notices under Section 131 or Section 133(6) to the lenders.
-
The assessee furnished loan confirmations, bank statements, ITRs of lenders, and proved all transactions were via account payee cheques.
-
Confirmation letters and bank records established that the unsecured loans were fully repaid within 6 to 7 months in the year 2010 itself—well before the search took place.
-
The AO treated the aggregate amount of Rs. 2 crores as unexplained cash credit under Section 68.
-
Decision
-
On Reassessment: The Tribunal held that non-issuance of a notice under Section 143(2) after the return is filed in response to a Section 148 notice is a fatal jurisdictional defect, rendering the reassessment order bad in law and liable to be quashed ab initio.
-
On Section 68 Addition: The Tribunal held that additions cannot be sustained solely on third-party statements or Investigation Wing reports without independent verification or corroborative evidence. Since the assessee discharged its initial burden of proof and demonstrated prompt loan repayment, the addition of Rs. 2 crores under Section 68 was deleted in favor of the assessee.
Key Takeaways
-
Jurisdictional Mandate of Section 143(2): Issuance of a notice under Section 143(2) is a mandatory statutory precondition for completing a valid assessment or reassessment after a return of income is filed.
-
Principles of Natural Justice: Making an addition based on third-party search statements without providing copies of adverse material or allowing cross-examination violates natural justice and invalidates the addition.
-
Genuineness of Unsecured Loans: Where an assessee proves identity, creditworthiness, and genuine movement of funds—corroborated by full repayment prior to search proceedings—additions under Section 68 cannot be made without concrete, independent evidence of recycled cash.
IN THE ITAT MUMBAI BENCH ‘D’
R.A Shah and Co.
v.
Deputy Commissioner of Income-tax
MS. DEBJANI MITRA NEOGY, Judicial Member
and Girish Agrawal, Accountant Member
and Girish Agrawal, Accountant Member
IT APPEAL NO. 553 (MUM) OF 2026
[Assessment year 2010-11]
[Assessment year 2010-11]
SEPTEMBER 9, 2026
Dhaval Shah and Ms. Isha Shah, Advs. for the Appellant. Sandeep Lakra, CIT DR for the Respondent.
ORDER
Girish Agrawal, Accountant Member.- This appeal filed by assessee is against the order of ld. Commissioner of Income Tax (Appeals)/National Faceless Appeal Centre [‘NFAC’], Delhi, Order No. ITBA/NFAC/S/250/2025-26/1083879582(1) dated 19.12.2025 passed against the reassessment order by Assistant Commissioner of Income Tax, Circle-19(3), Mumbai u/s 143(3) r.w.s. 147 of the Income-tax Act, 1961 (‘the Act’) dated 16.03.2016, for Assessment Year 2010-11.
2. Assessee has raised the following grounds of appeal:
1. Reopening of Assessment bad in law :
a. The learned CIT(A) has erred in confirming reopening the assessment by assessing officer u/s. 147 and issuing notice u/s. 148 of the Income Tax Act, 1961.
b. The learned CIT(A) erred in upholding the reopening of assessment merely based on information received from DGIT(Investigation), without forming independent belief with regard to escapement of income.
2. Addition of Cash credit u/s. 68
a. The learned CIT(A) erred in in confirming the addition of 2,00,00,000/- made by the Assessing Officer under section 68 of the Income Tax Act, 1961, without properly appreciating the facts, evidences and submissions of the appellant
b. The learned CIT(A) erred in upholding the action of the Assessing Officer in treating loans received from M/s Daksh Diamonds and M/s Rahul Exports as unexplained cash credits, ignoring the documentary evidences such as confirmations, PAN, ITR copies, bank statements and repayment of loans through banking channels.
c. The learned CIT(A) erred in confirming the addition merely on the basis of third-party statements and investigation reports, without establishing any direct nexus between the appellant and the alleged accommodation entry operators.
d. The learned CIT(A) erred in law in not providing the appellant copies of statements and materials relied upon by the Assessing Officer and in not granting opportunity of crossexamination, thereby violating principles of natural justice.
e. The learned CIT(A) failed to appreciate that the appellant had discharged the primary onus by proving identity, creditworthiness and genuineness of the lenders.
The appellant craves, leave to add to, amend, alter or withdraw any of the above grounds of appeal before or at the time of hearing of the appeal, if necessary.
3. Brief facts as culled out from records are that assessee filed its return of income on 08.09.2010, reporting total income at Rs.91,99,430/-. Subsequently, reopening proceedings were initiated by issuing a notice under Section 148 dated 13.02.2015, by recording the reasons to believe. In the reasons to believe recorded by the ld. AO, it is noted that a search and survey action was carried out by the DGIT (Investigation), Mumbai in the case of Shri Bhavarlal Jain Group on 03.10.2013 which resulted into collection of evidence and other findings based on which a conclusion was drawn that assessee has obtained accommodation entry, being one of the beneficiaries. Ld. AO gave details of parties who had issued accommodation bills to the assessee which included (i) Daksh Diamonds for an amount of Rs.1,00,00,000/- and (ii) Rahul Export for an amount of Rs.1,00,00,000/- (Totaling to Rs.2,00,00,000/-). Based on this information available with the ld. AO, he arrived at the reasons to believe that income of Rs.2,00,00,000/- chargeable to tax under the Act has escaped from assessment.
3.1. In para 4 of the impugned reassessment order, ld. A.O. records that notices u/s 143(2) and 142(1) dated 07.02.2016 were issued and served on the assessee asking to furnish various details in connection with the proceedings so initiated. In the course of reassessment proceedings, all the requisite details as called for were furnished and placed on record which has been duly acknowledged by the ld. AO in para 5 of the impugned order. Assessee filed its objection on 23.02.2016 pursuant to the direction of Hon’ble Supreme Court mandated in the case of GKN Driveshafts (India) Ltd. v. ITO [2003] 259 ITR 19 (SC) against the notice issued u/s 148, duly acknowledged by the stamp of the office of the ld. AO. In para 11 of this submission, assessee requested very categorically to provide copy of all the documents, information and statement relied upon by the ld. AO to arrive at the reasons to believe so recorded, leading to escapement of income from assessment of Rs.2,00,00,000/-. Assessee also requested to provide opportunity for cross-examination of Shri Bhavarlal Jain and others whose statements have been relied upon by the ld. AO. The objections so filed by the assessee were disposed of by the ld. AO vide order dated 29.02.2016, rejecting the same by stating that independent opinion was formed based on the information made available to him by the DGIT (Investigation), Mumbai resulting from the conduct of search action in the case of Bhavarlal Jain Group.
3.2. In the course of reassessment proceedings, assessee submitted the required documentary evidence to discharge the onus casted u/s 68 of the Act to establish identity and creditworthiness of the lenders and genuineness of the transaction by furnishing –
| (a) | Loan Confirmations |
| (b) | Bank Statements of the parties |
| (c) | Copy of return of income of the lender parties |
| (d) | Loan transactions are done by account payee cheques |
3.3. Ld. AO considered the loan transaction of Rs. 2,00,00,000/- with the said two parties as unexplained cash credit despite all the documentary evidences and explanation furnished by the assessee and added the same to the total income to complete the impugned reassessment. While completing the reassessment, ld. AO did not give any opportunity to the assessee to cross-examination the persons whose statement were relied upon and also did not provide copies of the statements and other material relied upon for the rebuttal by the assessee.
3.4. It is noted that while completing the reassessment, inadvertently ld. AO took amount of loan for each party as Rs.10,00,000/- instead of Rs.1,00,00,000/- and made the addition of Rs.20,00,000/- instead of Rs.2,00,00,000/-. To rectify this, a rectification order was passed u/s 154 dated 22.03.2016 by taking the correct figures at Rs.1,00,00,000/- each for both the parties and thus, making the addition of Rs.2,00,00,000/- instead of Rs.20,00,000/-. Aggrieved, assessee went in appeal before the ld. CIT(A).
4. Before the ld. CIT(A) also, specific request was made by the assessee through its written submission pointing out that ld. AO had failed to provide opportunity for cross-examination and verification of the material relied upon. It was also contended that ld. AO had not conducted any independent inquiry by issuing summons u/s 131 or notice u/s 133(6) on the said two lender parties nor brought on record any other cogent corroborative evidence but made the addition purely on assumption and surmises.
4.1. From para 6.2 of the first appellate order, it is noted that submissions made by the assessee in the course of reassessment proceedings had been acknowledged which include loan confirmations, bank statements of the parties, copy of return of the parties and the fact that these transactions were done through account payee cheques and the loans have been repaid prior to search action. Ld. CIT(A) in para 6.4 observes that finding of the ld. AO are based on investigation conducted by Investigation Directorate and analysis of the transaction which is based on modus operandi adopted by the searched party. According to the ld. CIT(A), the Investigation Directorate had identified number of fake concerns providing accommodation entries and the beneficiaries thereof, assessee being one of such beneficiaries. Further, in para 6.4.1, ld. CIT(A) observes that addition made by the ld. AO is not solely based on surmises but on the detailed report of Investigation Directorate and further analysis of the transaction inquired upon by the ld. AO to arrive at the conclusion reached by the Assessing Officer.
4.2. He then relied upon the decision of Hon’ble High Court of Calcutta in the case of Pr. CIT v. Swati Bajaj 446 ITR 56 (Calcutta) and several other judicial precedents. He categorically notes in para 6.7 that the Investigation Wing had conducted enquires which proved that assessee is one of the beneficiaries of the accommodation entries provided by Shri Bhanwarlal Jain and others through multiple layering of transaction and entries provided. He thus, concluded that the issue of availing accommodation entries for tax evasion is spread across the country and modus operandi is well established and therefore, case of assessee fits into the criteria of availing accommodation entries for tax evasion and thus, sustained the addition so made by ld. AO and dismissed the appeal. Aggrieved, assessee is in appeal before the Tribunal.
5. We have heard both the parties and perused the material on record. We have given our thoughtful consideration to the submissions made before us both, on legal issues and the merits of the case. Factual position of the issue before us is already narrated in the above paragraphs and therefore not reiterated.
5.1. On the legal issue that no valid notice u/s 143(2) has been issued pursuant to filing of return of income in response to notice u/s 148, fact of the matter is that notice u/s 148 was issued on 13.02.2015. Thereafter, notice u/s 143(2) was issued on 07.02.2016. Till this date, assessee had not filed its return of income in response to notice u/s 148 which in effect was filed on 08.02.2016. Thus, the return filed by the assessee is subsequent to the date of issue of notice u/s 143(2). No further notice was issued u/s 143(2) after filing of return of income on 08.02.2016. This factual position is undisputed and remains uncontroverted.
5.2. On this factual position, it is contended before us that failure to issue a notice u/s 143(2), subsequent to filing of return of income by the assessee renders the impugned reassessment proceedings void ab initio. The impugned reassessment has been completed without issuing a notice u/s 143(2) when assessee had filed its return of income in response to notice u/s 148, rendering the said reassessment bad in law, liable to be quashed ab initio. In this regard identical issue had come up before the Co-ordinate Bench of ITAT Mumbai in the case of Sudhir Menon v. ACIT [IT Appeal No. 1744 and 1466 (Mum) of 2016, dated 03.10.2018] wherein assessee had raised an additional ground which is reproduced as under for ready reference as it directly relates to the issue before us:
“1. The reassessment proceedings is bad in law as no notice under section 143(2) of the Income-tax Act, 1961 (‘the Act’) was issued after filing the return of income on 23 May 2013 pursuant to notice issued under section 148 of the act. The notice under section 143(2) of the act on 03. May 2013 is before the filing of the return of income on 23 May 2013 and is therefore illegal and hence the order passed by the assessing officer is bad in law.”
5.3. After considering the facts of the case and by placing reliance on the decision of Hon’ble jurisdictional High of Bombay in the case of Asstt. CIT v. Geno Pharmaceuticals Ltd. (Bombay), the Co-ordinate Bench held that assessment framed without issuing a notice u/s 143(2) when the return was filed by the assessee in response to notice u/s 148 is bad in law. It thus, quashed the said assessment and allowed the additional ground raised by the assessee.
6. Respectfully following the said judicial precedents in the present set of facts before us being identical, we hold that the impugned reassessment made by ld. AO for which no notice u/s 143(2) was issued, subsequent to filing of return of income in response to notice u/s 148, is bad in law and is accordingly, quashed as void ab initio.
6.1. Since we have quashed the impugned reassessment in terms of our above stated findings, other legal contentions raised by the ld. Counsel for the assessee are not dealt with and left open.
7. Even, on the merits of the case, we find that the reasons to believe recorded by the ld. AO mentions about accommodation “bills” issued to the assessee. In para 11 of the impugned reassessment order, in sub-para (i), ld. AO mentions that parties are issuing “bills without delivering any goods and services”. However, in the subsequent sub-paras, ld. AO deals with unsecured loans taken by the assessee for which it is alleged that assessee could not provide any documentary evidences and thus, failed to establish the creditworthiness and genuineness of the lenders. He notes that mere filing of evidences such as copies of bank statement showing payment through amount payee cheque are not sacrosanct.
7.1. From the perusal of the material placed in the paper book containing 48 pages, it is noted that assessee has furnished all the required documentary evidences for which e-response acknowledgments are placed on record. The various evidences furnished by the assessee in respect of the two lenders parties is listed below for ready references, copy of which is placed in the paper book:
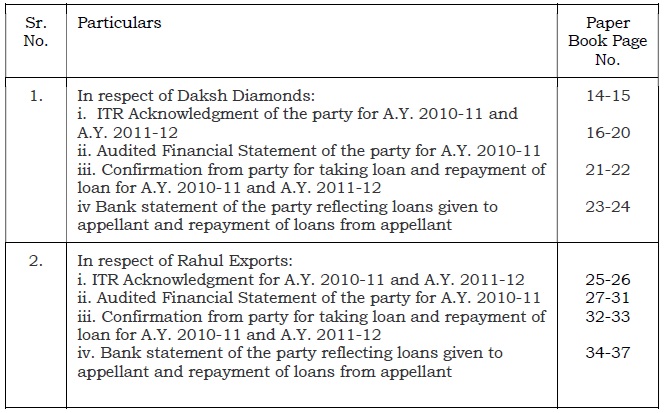
7.2. Through these submissions, assessee established the identity and creditworthiness of the two lender parties and the genuineness of loan transaction undertaken by it. It is evident from the orders of the authorities below that no notices or summons were issued under section 131/133(6) to the lender parties or to the parties covered by the search which lead to the impugned reopening proceedings so as to ascertain the veracity of the allegations made. Ld. AO as well as ld. CIT(A) have solely relied upon the investigation carried out by the Directorate of Investigation, Mumbai.
7.3. It is also a fact on record that assessee has made specific request in writing both, before the ld. AO and ld. CIT(A) to make available material relied upon as well as copies of statements recorded in the case of the unrelated search party for its rebuttal and crossexamination but no such opportunity nor material was provided to it.
7.4. Furthermore, it is also a fact on record as evident from confirmation letters of the two lender parties and their bank statements that these loans have been repaid by the assessee within a short duration of 6 to 7 months in the year 2010 itself which is much prior to the date of search undertaken in the case of Shri Bhanwarlal Jain & Group i.e. on 03.10.2013. Assessee has explained that it had taken these loans for making its business purchases and once the sale undertook and the sale consideration was realized, the loans were repaid to the parties from the sale proceeds.
8. In these given set of facts and circumstances, we find that ld. AO has considered the said loan as accommodation entries merely on the basis of information received from the Directorate Investigation, Mumbai and statements recorded in the case of search of Shri Bhanwarlal Jain Group. Assessee has furnished all the required documentary evidences explaining the details of the transaction discharging its onus casted u/s 68. These loans have also been repaid, fact of which is not in dispute. Ld. AO has not brought on record any cogent corroborative material to evidently established that these loan transactions entered into by the assessee were in fact accommodation entries. There is no evidence on record from the ld. AO to demonstrate that assessee had induced its entire unaccounted money in the garb of unsecured loan through the said two entities.
8.1. Ld. AO has not pointed out any defects or deficiencies in the material placed on record by the assessee to establish that the transactions entered into are sham or bogus. Also, the reliance placed by ld. CIT(A) on the judicial precedents, more particularly in the case of Swati Bajaj and others (supra) are distinguishably on facts as they all dealt with the issue relating to transaction of penny stock and longterm capital gain arising there from. In the present case before us, the transaction is that of unsecured loans taken by the assessee which has been repaid much prior to the date of search of an unrelated party which formed the basis of impugned reassessment proceedings.
8.2. We also take note of the decision of the Co-ordinate Bench of ITAT Mumbai in the case of ACIT v. Vashu Bhagnani [IT Appeal No. 5648 (Mum ) of 2016, dated 30.05.2018] wherein on a similar factual position, the proceedings were undertaken based on the same search carried out in the case of Bhanwarlal Jain Group on 03.10.2013. It was alleged that assessee had obtained accommodation entry from M/s Daksh Diamonds and operated by the said searched group. Co-ordinate Bench after deliberating on the facts and the law held that addition made by the ld. AO is without any documents and is devoid of merit. While deleting this addition, it observed that loan taken by the assessee from M/s Daksh Diamonds was in the year 2006 which was refunded in the year 2010 though the search and seizure action undertaken in the case of Shri Bhanwarlal Jain Group was on 03.10.2013. These facts are identical to the present case before us.
8.3. In the conspectus of the above factual position discussed in detail and considering the fact that assessee had discharged its onus casted under Section 68, we hold that there is no justifiable reason to treat the loan transactions undertaken by the assessee with the two said parties as unexplained cash credit. Ld. AO has made additions purely on conjectures and surmises, by merely relying upon the report of Directorate of Investigation Wing, Mumbai, ignoring cogent evidences placed on record by the assessee. The addition so made is accordingly deleted. Thus, even on merits of the case, assessee succeeds.
9. In the result, appeal of the assessee is allowed.