


Interest on Borrowed Capital and Subsequent Refinancing Eligible for Section 24(b) Deduction Upon Verification
Issue
-
Whether interest paid on borrowed funds—and subsequent refinancing thereof—utilised for the acquisition or construction of a house property is allowable as a deduction under Section 24(b), subject to verifying nexus with the property.
-
Whether disallowance under Section 14A, read with Rule 8D, can be made when no exempt income was earned by the assessee during the relevant assessment year.
Facts
-
Assessee Profile: The assessee-company is engaged in letting out real estate properties and reported rental income for the Assessment Year 2014-15.
-
Interest Claim Disallowance [Section 24(b)]:
-
The assessee claimed deduction under Section 24(b) for interest paid to two lenders on loans borrowed for acquiring/constructing the let-out property.
-
The Assessing Officer (AO) disallowed the entire interest claim due to lack of sale/takeover documentation proving that all borrowed funds were utilised for construction.
-
In preceding assessment years, the AO himself had allowed interest expenditure to the extent attributable to funds utilised for property construction.
-
The assessee established a direct link demonstrating that the subsequent borrowings refinanced the original loan taken for construction.
-
-
Disallowance in Absence of Exempt Income [Section 14A]:
-
The assessee reported income from house property, fixed deposits, and provisions written back, earning no exempt income during the year.
-
The AO nevertheless applied Section 14A read with Rule 8D to compute disallowance.
-
Decision
-
Allowability of Construction Interest: Principally, interest on borrowed funds used for property construction is eligible for deduction under Section 24(b) [Para 16].
-
Eligibility of Refinancing Costs: Interest paid on refinancing loans retains the same deductive character under Section 24(b), provided it is used to repay the principal of the original construction loan and a direct nexus is established [Para 16].
-
Remand for Fact Verification: The matter under Section 24(b) was remanded to the Assessing Officer for verification of corroborative evidence and establishing fund utilisation/nexus, with the onus placed on the assessee [Para 16].
-
No Section 14A Disallowance: Since no exempt income was earned during the assessment year, no disallowance under Section 14A read with Rule 8D was warranted [Para 17].
Key Takeaways
-
Refinanced Loans Qualify: Interest on subsequent loans taken specifically to repay original construction loans remains deductible under Section 24(b), supplied there is an unbroken, verifiable nexus.
-
Burden of Proof on Assessee: The taxpayer bears the burden to submit corroborative evidence proving the exact utilisation of original and replacement borrowings.
-
Absence of Exempt Income Bars Section 14A: Statutory disallowance under Section 14A / Rule 8D cannot be invoked mechanically if the assessee earned zero exempt income during the relevant financial year.
-
Consistency in Assessment: The Revenue must maintain logical consistency across assessment years when a proven nexus between borrowed funds and property construction already exists.
IN THE ITAT MUMBAI BENCH ‘F’
Jindal Combines (P.) Ltd.
v.
Deputy Commissioner of Income-tax
Pawan Singh, Judicial Member
and ARUN KHODPIA, Accountant Member
and ARUN KHODPIA, Accountant Member
IT Appeal No. 2079 (Mum) of 2026
[Assessment year 2014-15]
[Assessment year 2014-15]
SEPTEMBER 7, 2026
Vijay Mehta and Tarang Mehta for the Appellant. Vibhor Badoni, Sr. DR for the Respondent.
ORDER
Arun Khodpia, Accountant Member.- This appeal is preferred by the assessee, directed against the order of the Commissioner of Income Tax Appeals, National Faceless Appeal Centre (NFAC), Delhi [in short, “the Ld. CIT(A)”], dated 05.01.2026 for the Assessment Year (AY) 2014-15,arises from the assessment order under section 143(3) of the Income Tax Act, 1961 [in short, “the Act”] dated 02.12.2016, passed by Income Tax Officer-6(3)(3), Mumbai [in short, “the Ld.AO”].
2. The grounds of appeal raised by the assessee are as under:
| “i | . Disallowance of Interest expenses of Rs. 6,04,13,835/- claimed u/s 24(b) of the Income-tax Act, 1961. |
| i. | The Hon’ble CIT(A) erred in confirming the disallowance of interest expenses of 6,04,13,825/-claimed under section 24(b) of the Income-tax Act, 1961, |
| ii. | The Hon’ble CIT(A) erred in confirming the disallowance of interest expenses of 6,04,13,825/- claimed under section 24(b) of the Act, 1961, against the House Property Income, ignoring binding appellate orders passed in the assessee’s own case for AY 2010-11 to AY 2012-2013, wherein identical disallowance has been deleted. The Disallowance therefore, is disregard of binding order is neither justified nor valid. |
2. The Hon’ble CIT(A) erred in confirming disallowance of Rs. 6,81,077/- under section 14A r.w. rule 8D despite the fact that no exempt income was earned during the year and identical disallowances stood deleted in assessee’s own case for earlier assessment years.
3. The Hon’ble CIT(A) erred in confirming the disallowance of expenses of Rs. 50,92,740/-incurred wholly and exclusively for earning taxable business income.”
3. Brief facts of the case are that the assessee is a company engaged in the business of letting out of properties. On perusal of the return of the assessee, it is observed by the Ld. AO that the assessee had disclosed rental income of Rs.8,81,47,572/- received from M/s. Aegis Limited for letting out the property at JCPL Tower, Gurgaon and have claimeddeduction under section 24(b) amounting to Rs. 6,04,13,825/-. In the course of assessment proceedings, the assessee was requested to furnish the details of borrowed funds taken and utilization for housing loan and copy of the housing loan certificate. In this regard, assessee submitted that the interest of Rs. 5,59,06,976/- has been paid to India Bulls Limited and the remaining amount of Rs. 45,06,849/-was paid to HDFC Bank. In order to inquire further, the Ld. AO issued a letter to the assessee to furnish copy of loan sanction order from India Bulls and also to prove the nexus between borrowed funds and its utilization for construction of the property let out during the year under consideration. In response, the assessee submitted that a term loan was availed from HDFC Bank for acquiring the property. It is also clarified that during the year under consideration, the new management has taken over the company along with assets and liabilities and management had paid the consideration towards the property by its letter dated 23.11.2016. The assessee has further submitted that the loan was taken for funding the construction of property in Gurgaon, Haryana, the income from which has been offered for tax under the head house property.
4. It is submitted that the assessee has appropriated interest of Rs. 6,04,13,825/- towards the building and other integrated facilities and claimed the same as deduction against income from house property under section 24(b) of the act. The submissions of assessee were not found satisfactory by the Ld.AO. He observed that the assessee has not furnished copy of Agreement for taking over the company, the ownership of the property still remains with the assessee company even though the shareholders and directors have been changed. In absence of the agreement for sale of the property by previous management, it cannot be said that the entire borrowed fund utilized for the purpose of building only.
5. The Ld.AO further analyzed the financials of the assessee but was not convinced with the submissions made by the assessee, therefore had disallowed the entire interest expense claimed by the assessee under section 24(b) of the Act. Further the Ld.AO has examined the profit and gains from business of the assessee and noted that expenses incurred under the head repairs to building, insurance, rates and taxes excluding taxes on income and interest on delayed payment of Service Tax are claimed by the assessee.With respect to such expenses, the Ld.AO observed that the assessee has only income from property letting out property apart from interest from FDs and excess provision written back which shows that the assessee is not carrying on any business activity excluding letting out of the properties.
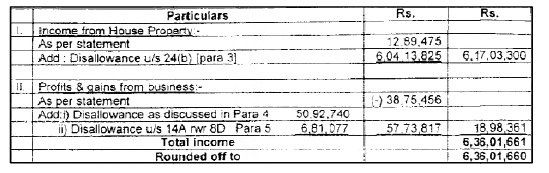
6. After discussions, the Ld.AO disallowed Rs.50,92,740/- from the expense claimed against business income which includes disallowance under section 30 for Rs.80,980/-, disallowance of Rs. 1,15,784/- regarding insurance premium treating the same relates to income from house property, disallowance of interest payment of Service Tax under section 36(1)(3) of the Act and disallowance of Rs. 31,75,200/- paid towards Stamp Duty and leave and license agreement. The Ld.AO further made a disallowance under section 14A read with Rule 8Dfor Rs.6,81,077/- applying provisions of rule 8D(2)(ii)and 8D(3) of the Income Tax Rules and finally the assessment was completed with determination of assessed income of assessee as under:
7. Being aggrieved, the assessee preferred an appeal before the Ld.CIT(A) who was convinced with the findings of the Ld.AO, therefore was not impressed with the contentions and submissions made by the assessee before him. Accordingly, the Ld. CIT(A) had dismissed the appeal of the assessee and sustained the additions/disallowances made by the Ld. AO.
8. Before us, Ld. Counsel of the assessee submitted that as per ground number 1 of the assessee’s appeal, the disallowance of interest expense amounting to Rs. 6,04,13,835/- claimed under section 24(b) of the Act was uncalled, unjustified and invalid. To substantiate the aforesaid contention, Ld.AR submitted certain details regarding interest paid to India Bulls Housing Finance Limited and interest paid to HDFC Limited which is claimed as eligible deduction under section 24(b) of the Act. It is submitted that the interest paid during the year was towards repayment of earlier housing loan which was availed and utilized for the purpose of acquisition of property. It is further submitted that the assessee had only claimed the interest to the extent of its utilization of loan for acquisition of house property. The details of such loans utilized and interest claimed under section 24(b) are furnished before us as a written note which is extracted as under:
“Details of allowable interest
I. Interest paid to Indiabulls Housing Finance Limited
Loan details for the period from 01.04.2013 to 03.03.2014
The principal amount of loan borrowed – Rs. 45.75 cr.
Amount utilized for the purpose of repayment of earlier loan (to the extent of its utilization for acquisition of house property) – Rs. 25 cr.
Percentage of amount utilized for acquisition of house property 55% (as admitted by the A.O. in preceding years).
Amount of interest paid – Rs. 5.59 cr.
Proportionate amount allowable @ 55% – Rs. 3.07 cr. (55% of Rs. 5.59 cr.)
II. Interest paid to HDFC Limited
Loan details for the period from 04.03.2014 to 31.03.2014
The principal amount of loan borrowed – Rs. 47 cr.
Amount utilized for the purpose of repayment of earlier loan (to the extent of its utilization for acquisition of house property) – Rs. 25 cr.
Percentage of amount utilized for acquisition of house property – 53% (Rs. 25 cr. out of Rs. 47 cr.).
Amount of interest paid – Rs. 0.45 cr.
Proportionate amount allowable @ 53% – Rs. 23.85 lacs (53% of Rs. 0.45 cr.)
Therefore, total amount of interest allowable is Rs. 330.85 lacs (Rs. 3.07 cr. + Rs. 23.85 lacs).
The balance amount of interest is towards investment in debentures and bank FD. The same should be allowed to be capitalized/as a deduction based on the verification by the A.O.”
9. It was the submission that since the interest which is claimed under section 24(b) of the Act was only towards the funds borrowed from different financial institutions, which were utilized for repayment of the existing housing loans which originally were utilized for the construction of property, therefore, to the extent such loans were utilized for acquisition of property or for repayment of loans through which the property is acquired shall be allowable under section 24(b) of the Act. Ld. Counsel also furnished a chart showing utilization of borrowed funds and its nexus with subsequent loans utilized to repay the earlier loans. The chart is reproduced as under:
Details of utilization of borrowing and claim of interest expenditure allowed by the Department
| Sr. No. | A.Y. | Particulars | Final position of allowance of claim |
| 1. | 2009-10 | HDFC had sanctioned a loan of Rs. 38 cr. on 07.07.2008 to the assessee. Out of this, Rs. 31.50 cr. has been utilized towards construction of house property and balance Rs. 6.5 cr. has been utilized for making investment (debentures). | The claim of interest has been allowed u/s. 143(1) of the Act. |
| 2. | 2010-11 | The assessee continued to pay the interest to HDFC Limited | 83% of interest expenditure, in the ratio of utilization of borrowed amount (Rs. 31.50 cr. out of Rs. 38 cr.) has been allowed against house property income by the A.O. pursuant to the order of the Hon’ble Tribunal. |
| 3. | 2011-12 | The assessee continued to pay the interest to HDFC Limited | (i) 83% of interest expenditure has been allowed against house property income by the A.O. himself. (ii) Balance 17% of interest, in the ratio of utilization of borrowed amount (Rs. 6.5 cr. out of Rs. 38 cr.) has been allowed to be capitalized to the cost of investment pursuant to the order of the Hon’ble Tribunal. |
| 4. | 2012-13 | The assessee borrowed Rs. 45.75 cr. on 26.09.2011 from Indiabulls Financial Services Ltd. out of which; (i) Rs. 25 cr. has been utilized towards repayment of principal amount of loan taken from HDFC Limited, (ii) Rs. 9 cr. has been invested in ICD, and (iii) balance Rs. 11 cr. has been utilized towards investment |
Pursuant to the order of the A.O. passed u/s. 143(3) r.w.s. 250 r.w.s. 263 of the Act; (i) 83% of interest expenditure for a period up to 25.09.2011 and 55% of interest (in the ratio of Rs. 25 cr. out of Rs. 45.75 cr.) for a period post 25.09.2011 has been allowed against house property income. (ii) 20% of interest paid to Indiabulls Financial Services Ltd. (in the ratio of Rs. 9 cr. out of Rs. 45.75 cr.) has been allowed against interest income on ICD. |
| 5. | 2013-14 | The assessee continued to pay the interest to Indiabulls Financial Services Ltd. | Pursuant to the order of the A.O. passed u/s. 143(3) r.w.s. 250 r.w.s. 263 of the Act; (i) The interest expenditure to the extent of 55% has been allowed against house property income. (ii) 20% of interest paid to Indiabulls Financial Services Ltd. (in the ratio of Rs. 9 cr. out of Rs. 45.75 cr.) has been allowed against interest income on ICD. |
| 6. | 2014-15 | The assessee borrowed Rs. 47 cr. on 04.03.2014 from HDFC Limited and repaid Rs. 43.39 cr. to Indiabulls Financial Services Ltd. | Year under consideration. |
10. Per contra Ld. DR vehemently supported the orders of Revenue Authorities, has referred to para 4.4.1 of the CIT(A)’s order who categorically noted that as per the finding of Ld. AO, the funds were utilized for general corporate purposes of the group, therefore, there was no direct nexus which is required under section 24(b). Mere repayment of loan with another does not automatically transmit the character of construction capital if the original utilization is in doubt, the principle of res judicatadoes not apply to Income Tax proceedings.
11. We have considered the rival submissions, perused the material available on record and examined the explanations furnished by the assessee regarding the nexus between the loan availed by the assessee and its utilization towards construction or acquisition of the underlying property. Admittedly, we find substance in the submissions of the assessee. The property was constructed by the assessee and the first loan was availed from HDFC Bank in AY 2009-10 for an amount of Rs. 38.00 crores, out of which Rs. 31.50 crores were utilized by the assessee towards construction of the house property, while the remaining amount of Rs. 6.50 crores were utilized for making investments in debentures.
12. As per the averments of the assessee, the claim of interest expenditure for AY 2009-10 was allowed to the assessee under intimation issued u/s 143(1) of the Act. Further, in AY 2010-11, the assessee claimed 83% of the interest expenditure against income from house property u/s 24(b) of the Act, corresponding to the portion of the loan utilised towards construction of the house property, i.e., Rs. 31.50 crores out of the total loan of Rs. 38.00 crores. Similar was the position in AY 2011-12, wherein the assessee claimed 83% of the interest expenditure on the loan availed from HDFC Bank in AY 2009-10 against income from house property, while the remaining interest expenditure was capitalised, as the corresponding portion of the loan had been utilised towards investment, pursuant to the order of the Tribunal.In the subsequent AY 2012-13, the assessee availed another loan of Rs. 45.75 crores on 26.09.2011 from Indiabulls Financial Services Ltd., out of which an amount of Rs. 25.00 crores were utilised towards repayment of the principal amount of the loan availed from HDFC Bank. It is further submitted that, for AY 2012-13, an assessment was completed u/s 143(3) r.w.s. 250 r.w.s. 263 of the Act, wherein 83% of the interest expenditure for the period up to 25.09.2011 and 55% of the interest expenditure, being in the ratio of Rs. 25.00 crores to Rs. 45.75 crores, for the period subsequent to 25.09.2011, was allowed against income from house property. The remaining 20% of the interest expenditure paid to Indiabulls Financial Services Ltd., corresponding to Rs. 9.00 crores out of the loan of Rs. 45.75 crores, was allowed against interest income earned on ICDs.
13. During AY 2013-14, the assessee followed the same method for allocation of the interest expenditure paid to Indiabulls Financial Services Ltd. and an order was passed by the Ld. AO u/s 143(3) r.w.s. 250 r.w.s. 263 of the Act, wherein 55% of the interest expenditure was allowed against income from house property and 20% was allowed against interest income earned on ICDs. The year under consideration is AY 2014-15, wherein the Ld. AO has departed from the position consistently adopted in the preceding years and disallowed the interest expenditure claimed by the assessee u/s 24(b) of the Act.
14. In this factual backdrop, once the assessee has demonstrated the nexus between the borrowed funds and their utilisation towards construction of the property, and the Ld. AO himself had, in the preceding assessment years, allowed the interest expenditure to the extent attributable to the funds utilised for construction of the property u/s 24(b) of the Act, the departure from the consistently adopted position in the year under consideration would require examination with reference to the facts and material available on record. In the absence of any material brought on record to establish a change in the nature or utilisation of the borrowed funds, the Revenue, having consistently accepted the aforesaid basis of allocation in the preceding years, could not, without demonstrating any distinguishing feature or change in facts, adopt a contrary position in the year under consideration. Accordingly, the disallowance of interest expenditure u/s 24(b) of the Act, on the facts as emanating from the record, was not warranted.
15. We, prima facie, find substance in the submissions of the assessee and agree with the same, which is also borne out from the orders passed by the Ld. AO in the preceding AYs, wherein the assessee was allowed deduction u/s 24(b) of the Act in respect of the interest expenditure attributable to the funds utilised towards construction of the property. Under these circumstances, we are unable to subscribe to the view adopted by the Revenue Authorities in the present case. However, on perusal of the order of the Ld. CIT(A), a new fact has emerged, namely, that the fundamental character of the original borrowing was for corporate/working capital purposes and not strictly for construction of the property. The Ld. CIT(A) agreed with the contention that refinancing of a loan is permissible; however, the assessee was required to demonstrate that the original borrowing was utilised for construction, as the utilisation of the original borrowing was otherwise in doubt.
16. Principally, we agree with the submissions of the assessee that if the borrowed funds are utilised for construction of a building, the interest expenditure attributable thereto would be eligible for deduction u/s 24(b) of the Act, subject to fulfilment of the conditions prescribed therein. Further, where such borrowing is subsequently refinanced, the interest expenditure relatable to the refinancing of the original borrowing would also partake of the same character, to the extent the refinancing is utilised for repayment of the principal amount of the original borrowing and a direct nexus with the borrowing utilised for construction of the building is established. We, therefore, approve the aforesaid principle, subject, however, for verification of the relevant facts from corroborative evidence to be furnished by the assessee, having onus to satisfy the assessing authority, particularly with regard to the utilisation of the original borrowing and the nexus between the original and subsequent borrowings.
Accordingly, Ground No. 1 of the appeal is allowed for statistical purposes in the above terms.
17. Ground No. 2 pertains to disallowance under section 14A which is made by the Ld. AO for Rs. 6,81,077/- under his conviction that as per CBDT Circular No. 5/2014 Rule 8D comes into play in the present case and therefore the assessee is allowable to pay tax on disallowance under section 14A to the extent of 5% of average investment of the assessee. Ld. AR on this aspect has argued that the assessee has clarified before the Ld. AO that the assessee had not earned any exempt income during the year under consideration. Therefore, disallowance under Section 14A is not applicable in the case of the assessee. The Ld. AO observed that applicability of Rule 8D read with Section 14A would trigger irrespective of the fact whether any such income has been earned during the financial year or not. It relates only to the capability of the investment to earn exempt income and the actual expenditure incurred for earning of the exempt income during the year under consideration. On this aspect, we are of the considered view that the Ld.AO was not right, while contravening the settled principles of law as laid down by Hon’ble Courts including the Hon’ble Bombay High Court in the case of Pr. CIT v. Kohinoor Project Pvt Ltd [2020] 121 425 ITR 700 (Bombay)) following the judgement of Hon’ble Delhi High Court in the case of Cheminvest Ltd. v. CIT 378 ITR 33 (Delhi) has held that in absence of exempt income, no disallowance is warranted u/s 14A of the Actis called for.
We accordingly direct the Ld.AO to delete the addition under section 14A. ground of appeal no 2 is thus allowed.
18. Ground No.3is not pressed by the assessee, therefore,is dismissed as not pressed.
19. The assessee also raised an additional ground regarding borrowed funds and interest thereon, which is utilized for the purpose of investment to be capitalized, which on account of inadvertent omission could not be capitalized by the assessee. Therefore,it is requested to direct the revenue authorities to allow capitalization of such interest expenditure. We, in terms of our observations herein above direct the AO to allow capitalization of interest to the extent borrowed funds are utilized for the purpose of investment, after factual verification of interest expenditure, as directed with regard to ground no 1 of the present appeal. In result the additional ground of assessee is also allowed for statistical purpose.
20. In result the appeal of assessee stands partly allowed, in terms of aforesaid observations.
■