


Ex Parte Demand Orders Remanded as Blind Portal Matching Ignored ITC Reversals and Statutory Formulas
Issue
Whether ex parte adjudication orders confirming demands based purely on portal discrepancies (GSTR-3B vs GSTR-2A, GSTR-9 vs GSTR-9C) and common credit reversals are sustainable without verifying actual books, net ITC reversals, and statutory turnover ratios.
Facts
-
Business Background: The appellant, a bakery products manufacturer, reported largely exempt turnover along with a small portion of taxable supplies taxed at 5% during F.Y. 2018–19.
-
Portal Discrepancies & SCN: Based on scrutiny, the Assessing Officer issued SCNs under Section 73 alleging:
-
Excess ITC claims based on GSTR-3B vs GSTR-2A variances.
-
Short payment of tax based on differences between Table 9 of GSTR-9 and Column 9P of GSTR-9C.
-
Short reversal of common ITC under Rule 42 and Rule 43.
-
-
Ex Parte Orders: The AO passed ex parte Orders-in-Original confirming the entire cumulative demand without verifying primary accounting records.
-
First Appeal Dismissal: The Commissioner (Appeals) dismissed the appeal ex parte and upheld the confirmed tax demands.
-
Omissions in Adjudication:
-
The Department failed to account for self-mitigating ITC reversals disclosed in Tables 4(B)/4(C) of Form GSTR-3B and Table 10 of Form GSTR-9C.
-
The Department treated the entire ITC pool as common credit without segregating specific credits or applying the exempt-to-taxable turnover ratio to the true common credit pool under Rules 42 and 43.
-
Decision
-
Blind Portal Matching Impermissible (Matter Remanded): Automatic or blind portal comparison ignoring self-mitigating reversals disclosed in returns cannot establish actual net tax liability.
-
Failure to Apply Statutory Rules (Matter Remanded): Proportional ITC reversals under Rules 42 and 43 require proper segregation of specific credits before applying turnover ratios to the common pool; treating total ITC as common credit shows non-application of mind.
-
Reconciliation Differences Misinterpreted (Matter Remanded): Variance between GSTR-9 and GSTR-9C represents a balancing reconciliation figure rather than automatic unpaid output tax.
-
Setting Aside & Remand (In Favour of Assessee): Both the Orders-in-Original and Orders-in-Appeal were set aside due to ex parte proceedings and lack of substantive factual verification. The matter was remanded for de novo verification based on sales ledgers, invoices, and primary books of account.
Key Takeaways
-
Primary Books Prevail Over Portal Variances: Portal-based matching tools are initial scrutiny indicators; final tax liability under Section 73 cannot be confirmed without examining primary books of account and underlying invoices.
-
Mandatory Accounting of Reversals: Tax authorities must verify net ITC by deducting reversals disclosed in GSTR-3B and GSTR-9/9C before alleging excess ITC claims.
-
Strict Application of Rule 42 & 43 Mechanics: Reversal of common ITC on exempt supplies requires prior segregation of exclusively taxable and exclusively exempt ITC before applying the statutory formula to common credits.
GOODS AND SERVICE TAX APPELLATE TRIBUNAL , LUCKNOW BENCH
Nitin Bakers (P.) Ltd.
v.
Vijay Singh Visen*
Santosh Kumar Srivastava, Judicial Member
and Arvind Kumar, Technical Member
and Arvind Kumar, Technical Member
APL/108/LCK/2026
OCTOBER 21, 2026
Dinesh Shukla, Adv. for the Appellant. Ashutosh Mishra, AC for the Respondent.
ORDER
1. Brief Facts of the Case
1.1. The present appeal has been filed by M/s Nitin Bakers Private Limited (hereinafter referred as ‘Appellant), having GSTIN 09AABCN6538J1Z4, with its place of business at B-22, Site-5, Udyog Kunj, Panki Industrial Area, Kanpur Nagar, Uttar Pradesh, against the Order-in-Appeal dated 22.02.2025, bearing Form GST APL-04 No. ZD090325038939U dated 05.03.2025, passed by the Additional Commissioner, Grade-II (Appeal)-V, State Tax, Kanpur, whereby the first appeal preferred by the appellant was dismissed and the demand confirmed by the Proper Officer under Section 73 of the CGST/UPGST Act, 2017 (hereinafter referred as ‘Act’), was upheld.
1.2. The appellant is engaged in the business of manufacturing and selling bakery products, including bread, buns and rusk. During the Financial Year 2018-19, the appellant declared a total turnover of Rs 5,96,73,200.70/-, out of which Rs.5,59,06,603.70/- declared as exempted supplies and Rs.37,66,597/- declared as taxable supplies attracting GST at the rate of 5%. The total output tax liability for the relevant financial year was Rs. 1,88,333.88/-, comprising CGST of Rs.94,166.94/- and SGST of Rs.94,166.94/-.
1.3. The proceedings originated from scrutiny of the returns filed by the appellant for the Financial Year 2018-19 under Section 61 of the CGST/UPGST Act, 2017. During such scrutiny, the Proper Officer noticed certain discrepancies relating to Input Tax Credit (ITC), reconciliation of tax liability and reversal of ITC attributable to exempt supplies. Accordingly, a notice in Form GST ASMT-10 dated 21.11.2023, bearing Reference No. ZD091123228671J, was issued to the appellant, pointing out discrepancies under various parameters.
1.4. Subsequently, a show cause notice dated 23.12.2023, bearing Reference No. ZD091223441461N, was issued under Section 73 of the CGST/UPGST Act, 2017. The demand was primarily based on three discrepancies, namely, alleged excess availment of ITC amounting to Rs.2,589.62/- on comparison of GSTR-3B with GSTR-2A, difference of Rs.25,93,217.12/- between the tax figures reflected in GSTR-9 and GSTR-9C, and alleged short reversal of ITC amounting to Rs.51,756.66/- under Rules 42 and 43 of the CGST Rules, 2017.
1.5. Thereafter, the Proper Officer, namely the Deputy Commissioner, State Tax, Sector-27, Kanpur, passed an ex parte Order-in-Original dated 18.04.2024, bearing DRC-07 No. ZD090424237127E, confirming a total demand of Rs.56,24,458.40/-, comprising tax of Rs.26,47,563.40/-, interest of Rs.26,62,217.00 and penalty of Rs.3,14,678/-. The demand was confirmed on the basis of the discrepancies noticed in the statutory returns and the alleged failure of the appellant to furnish satisfactory clarification and supporting evidence.
1.6. Being aggrieved by the aforesaid Order-in-Original, the appellant preferred a first appeal under Section 107 of the CGST/UPGST Act, 2017, on 14.08.2024, vide ARN AD0908240356005, after depositing the prescribed pre-deposit of Rs.2,64,758/-. In the appeal, the appellant challenged the demand mainly on the ground that the alleged discrepancies arose from an incorrect comparison of figures reported in different statutory returns and that the ITC reversal already made by the appellant had not been properly considered.
1.7. The First Appellate Authority, vide Order-in-Appeal dated 22.02.2025, dismissed the appeal ex parte on account of the absence of the appellant and upheld the demand confirmed by the Proper Officer on the following findings.
| • | Regarding the ITC variance of Rs.22,589.62/- between GSTR-3B and GSTR-2A, the claim remained unsubstantiated by any primary documentary evidence. Citing Section 16(2) (c) of the CGST Act, the authority established that input tax credit is legally inadmissible unless the corresponding tax has been actually deposited into the government treasury. |
| • | For the tax liability mismatch of Rs.2,593,217.12/- between Column 9 of GSTR-9 and Column 9P of GSTR-9C, the appellant provided no factual, evidentiary, or legal explanation to justify the discrepancy. |
| • | Regarding ITC reversal of Rs.51,756.67/- under Rules 42 and 43, the appellant failed to produce compliance records. Despite being granted four distinct hearing opportunities at the appellate stage, the appellant neither produced original records nor verified any submitted assertions, making the confirmation of the demand legally mandatory. |
1.8. Aggrieved by the Order-in-Appeal and the consequential confirmation of tax, interest and penalty, the appellant has preferred the present second appeal under Section 112 of the CGST/UPGST Act, 2017, seeking setting aside of the impugned orders and consequential relief in accordance with law.
2. Grounds of Appeal
The appellant has challenged the impugned Order-in-Appeal on the following grounds:
2.1. The appellant has submitted that the impugned Order-in-Appeal is contrary to the facts and circumstances of the case and the provisions of the CGST/UPGST Act, 2017. The First Appellate Authority failed to properly appreciate the statutory returns and reconciliation statements and upheld the demand without examining the actual nature of the discrepancies pointed out by the Proper Officer.
2.2. The appellant has contended that the demand of Rs. 2,589.62 towards alleged excess ITC was raised merely on comparison of GSTR-3B with GSTR-2A, without considering the ITC reversed in GSTR-3B. The appellant has submitted that the Department’s own figures reflect lower availment of ITC under the CGST and SGST heads and that the demand was confirmed without any proper verification of the net ITC position.
2.3. The Appellant further submitted that the major portion of the disputed tax demand, amounting to Rs. 25,93,217.12, arose from an incorrect comparison of Table 9 of GSTR-9 with Table 9P of GSTR-9C. It was explained that the figures appearing in the two tables were different in nature, as one reflected the tax declared and paid through returns, including the effect of ITC reversal, whereas the other reflected the tax payable on outward taxable supplies. It was argued that the difference between these figures could not automatically be treated as unpaid tax. The appellant has contended that the Department incorrectly treated such reversal as unpaid tax without considering the explanation recorded in Table 10 of GSTR-9C.
2.4. The appellant has submitted that the demand of Rs. 51,756.66 towards alleged short reversal of ITC under Rules 42 and 43 is also unsustainable. It has been contended that substantial ITC had already been reversed during the relevant financial year and that the Proper Officer failed to consider the actual reversal made in GSTR-3B while determining the alleged shortfall.
2.5. With regard to the alleged short reversal of ITC under Rules 42 and 43, the learned counsel submitted that the appellant had reversed ITC amounting to Rs. 19,75,422.62 as reflected in GSTR-9, whereas the total reversal appearing in Table 4(B) of GSTR-3B amounted to Rs. 29,48,853.00. It was argued that the reversal already made was substantially higher than the amount alleged to have been short-reversed and that the Department failed to properly reconcile these figures before confirming the demand.
2.6. The appellant has further submitted that the proceedings initiated under Section 73 were not supported by any proper finding establishing that tax had remained unpaid or short-paid or that ITC had been wrongly availed and utilised. It has been contended that the entire demand was based on an incorrect interpretation of figures appearing in different statutory returns.
2.7. The appellant has also challenged the levy of interest amounting to Rs. 26,62,217/- and penalty amounting to Rs.3,14,678.00. It has been submitted that neither the interest nor the penalty was properly quantified in the show cause notice and that the consequential demand could not survive in the absence of any legally sustainable tax liability.
2.8. The appellant has submitted that the Order-in-Original was passed ex parte without proper examination of the statutory records available on the common portal. The First Appellate Authority also failed to independently examine the grounds raised in the appeal and dismissed the matter on account of non-appearance, without recording proper findings on the merits of the dispute.
2.9. The appellant has contended that the impugned orders suffer from non-application of mind and violation of the principles of natural justice. The appellant has accordingly prayed that the Order-in-Appeal dated 22.02.2025 and the Order-in-Original dated 18.04.2024 be set aside and the entire demand of tax, interest and penalty be quashed.
2.10. In support of the above submissions, the appellant placed reliance upon the judgments in Union of India v. Bharti Airtel Ltd. [2021] [2022] 89 GST 1/[2021] 54 GSTL 257 (SC)/(2022) 4 SCC 328, Suncraft Energy (P.) Ltd. v. Asstt. Commissioner, State Tax [2023] 153 99 GST 400/77 GSTL 55 (Calcutta)/MAT 1218 of 2023, Bharat Mint and Allied Chemicals v. Commissioner of Commercial-tax [2022] 136 92 GST 61/59 GSTL 394 (Allahabad)/Writ Tax No. 1029 of 2021, CIT v. S. Chenniappa Mudaliar [1969] 74 ITR 41 (SC)/(1969) 1 SCC 591, St. Antony Trading and Transport (P.) Ltd. v. Joint Commissioner (Appeals) (Kerala)/W.P.(C) No. 14743 of 2025, andHindustan Steel Ltd. v. State of Orissa [1972] 83 ITR 26 (SC)/(1969) 2 SCC 627 , to support the contentions relating to verification of ITC, principles of natural justice, disposal of appeals on merits and imposition of penalty.
2.11. The learned counsel finally submitted that the disputed demand had been raised without properly examining the nature of ITC reversal, the reconciliation of statutory returns and the actual tax liability of the appellant. It was therefore prayed that the impugned Order-in-Appeal dated 22.02.2025 and the Order-in-Original dated 18.04.2024 be set aside, the entire demand of Rs. 56,24,458.40/- be quashed and consequential relief, including refund of the pre-deposit in accordance with law, be granted to the appellant.
3. Submissions of the Revenue:
3.1. The learned representative appearing on behalf of the Revenue defends the impugned orders and submits that the Order-in-Original dated 18.04.2024 passed by the Proper Officer and the Order-in-Appeal dated 22.02.2025 passed by the First Appellate Authority are perfectly legal, correct, and passed in strict accordance with the law. The Revenue places absolute reliance on the findings recorded in both the OIO and OIA.
3.2. The learned representative submits that during the scrutiny of returns under Section 61 of the Act, explicit discrepancies were noticed across multiple parameters, including excess availment of Input Tax Credit (ITC) and a clear short reversal of ITC attributable to exempt supplies under Rules 42 and 43 of the CGST Rules, 2017.
3.3. It is further submitted that despite being granted ample and fair opportunities at both the adjudication and appellate stages including four distinct hearing opportunities before the First Appellate Authority the Appellant chose not to appear and completely failed to file any written explanation or primary documentary evidence to clarify these mismatches.
3.4. Regarding the Rule 42 demand, the learned representative contends that in the absence of any statutory records, bifurcated details, or ledger accounts being produced by the taxpayer to substantiate what constituted ‘specific credit’ versus ‘common credit,’ the Adjudicating Authority had no alternative but to act upon the metrics visible on the common portal. The Appellant cannot now challenge the lack of physical verification when they themselves failed to comply with the statutory notices issued in Form GST ASMT-10 and Form GST DRC-01.
3.5. The learned representative concludes that since the input tax credit is legally inadmissible under Section 16(2)(c) unless the tax has actually reached the government treasury, and since the Appellant failed to produce compliance records or verify their assertions, the demand for tax, interest, and penalty was legally mandatory.
3.6. The learned representative contends that a massive tax liability variance of Rs. 25,93,217.12/- was detected between the tax payable figures declared in Table 9 of Form GSTR-9 and Column 9P of Form GSTR-9C. The Revenue submits that this constitutes a direct, unreconciled shortfall in output tax. The Appellant completely failed to provide any factual, evidentiary, or legal justification before the lower authorities to show how this variance was revenue-neutral or merely an accounting adjustment. Therefore, the Revenue prays that the present appeal filed by the Appellant be dismissed on merits and the confirmed demand be upheld.
4. Discussion and Findings
4.1. We have carefully examined the grounds of appeal, the impugned Order-in-Appeal, the primary Order-in-Original, and the statutory returns filed by the Appellant Forms GSTR-3B, GSTR-2A, GSTR-9, and GSTR-9C for the Financial Year 2018-19. We have also analyzed the judicial precedents relied upon by the Appellant. We find that both the lower authorities adjudicated these issues ex-parte without conducting a physical or substantive reconciliation of the primary accounting records.
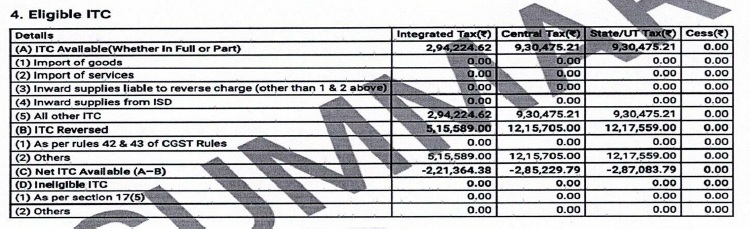
4.2. The Revenue confirmed a demand of Rs. 2,589.62/- towards alleged excess ITC availment in Form GSTR-3B on comparison with Form GSTR-2A. However, Appellant’s submissions reveals that this demand was raised without verifying the net ITC position. The Appellant has contended that the Proper Officer completely ignored the ITC reversals already executed by the Appellant within Form GSTR-3B itself. The Appellant’s primary ledger entries and the Department’s own underlying data reflect a lower net availment of ITC under both the CGST and SGST heads once these self-mitigating reversals are factored in. Details of ITC availed and reversed as per table 4 of GSTR-3B during the FY 2018-2019;
And details of the ITC availed as per para 4 of ASMT-10 issued by the revenue is as under;
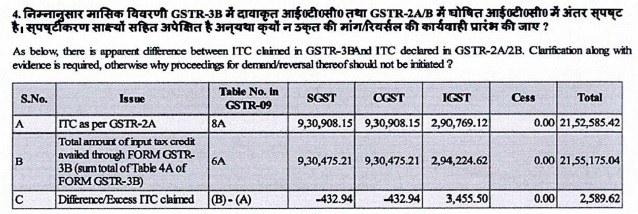
4.3. We find that in the present case, the lower authorities committed a patent factual and legal error by failing to perform a net ITC verification. As per the table 4C of the GSTR-3B placed hereinabove, they failed to analyze whether the alleged excess claim was already neutralized by the Appellant’s ITC reversals.
4.4. We find substantial strength in the Appellant’s contention. The law does not permit the Revenue to look at return figures in total isolation. As established by the Hon’ble Orissa High Court in Manoja Kumar Nayak v. Commissioner GST and Central Excise, Rourkela 115 GST 615 (Orissa)/WP No 12682 of 2025, once an amount has already been accounted for or adjusted through the reversal of ITC within the statutory returns, the Department is legally prohibited from raising a duplicate tax demand on the same transaction without giving due credit for such a reversal. Similarly, the Hon’ble Madras High Court in M/s. Oasys Cybernetics Pvt. Ltd. has mandated that the Adjudicating Authority must determine the net credit position and evaluate whether any actual revenue loss has occurred before confirming a demand. By blindly matching Form GSTR-3B with Form GSTR-2A and ignoring the self-mitigating reversals already executed by the Appellant in Table 4(B) of their returns, the Proper Officer completely failed to determine the true ‘net ITC position,’ rendering the demand fundamentally unsustainable on facts.
4.5. Second and most substantial portion of the confirmed demand, amounting to Rs. 25,93,217.12/-, arises from a discrepancy between Table 9 of Form GSTR-9 (tax paid) and Table 9P of Form GSTR-9C (tax payable). The Appellant has argued that this variance is not an unpaid tax liability. Rather, it represents an accounting and reporting difference because one field reflects output tax on outward supplies, while the other incorporates the cascading effect of ITC reversals already executed through the returns. The Appellant had explicitly disclosed this explanation in Table 10 of Form GSTR-9C. The Proper Officer, however, failed to scrutinize the systemic flow of these entries and erroneously treated a balancing reconciliation figure as actual short-paid tax. Determining a tax liability requires an independent verification of sales ledgers, tax invoices, and financial books, rather than a simplistic comparison of two fields on the portal. In this regard, we are of the view that a thorough re-verification by the Proper Officer is absolutely essential to resolve this issue.
4.6. Furthermore, the Revenue alleged a short reversal of ITC amounting to Rs. 51,756.66/-under the proportional reversal mechanisms of Rules 42 and 43. On the other hand, the Appellant demonstrated via documentary records that they had reversed ITC worth Rs. 19,75,422.62/- in Form GSTR-9, and a total of Rs. 29,48,853.00/- in Table 4(B) of Form GSTR-3B during the relevant financial year.
4.7. We find that the Department has raised the Rule 42 demand by treating the entire Input Tax Credit (ITC) as ‘Common ITC’, completely discarding the mandatory requirement of identifying and segregating the actual common credit. Since the demand has been raised without verifying the nature of the credit, we find that the lower authorities issued the demand without proper verification. A valid determination under Rules 42 and 43 of CGST Rules, 2017 cannot be achieved without first segregating the specific credit from the common credit, and then mapping the exact mathematical ratio of exempt-to-taxable turnover against the actual common input tax pool. This statutory exercise was entirely omitted in the impugned proceedings.
4.8. In light of the above findings, this we are of the view that the impugned order suffer from a total lack of factual verification and non-application of mind. Confirming a demand purely on system-generated discrepancies without conducting a detailed one-to-one financial reconciliation violates the spirit of law and fairness. Because a comprehensive verification of primary invoices, accounting ledgers, and return computations cannot be effectively undertaken at the any stage, it is in the interest of justice that the matter be remanded back to the Adjudicating Authority for a fresh, de novo verification. The Appellant to submit all the documents which is required for proper verification before the Adjudicating Authority.
Order
For the reasons discussed above, the impugned Order-in-Appeal dated 22.02.2025 passed by the Additional Commissioner, Grade-II (Appeal)-V, State Tax, Kanpur, and the primary Order-in-Original dated 18.04.2024 passed by the Deputy Commissioner, State Tax, Sector-27, Kanpur, are hereby set aside.
The entire matter is remanded back to the Adjudicating Authority (Proper Officer) for a fresh, de novo adjudication and proper verification in accordance with the law.
The present Appeal is accordingly allowed by way of remand.