ORDER
1. M/s Chandrakala Universal Private Limited, having registered office at 42/7, Jawaharlal Nehru Road, Prayagraj, Uttar Pradesh, 211002 (hereinafter referred as “the applicant”) having GSTIN-09AAFCC5216Q1Z8, have filed an application for Advance Ruling under Section 97 of the CGST Act, 2017 read with Rule 104 of the CGST Rules, 2017 and Section 97 of UPGST Act, 2017 read with Rule 104 of the UPGST Rules, 2017 in Form GST ARA-01 (the application form for Advance Ruling), discharging the fee of Rs. 5,000/-each under the CGST Act and the UPGST Act.
2. The applicant is engaged in the business of confidential printing of Educational Test papers, which requires team of highly experienced persons and maintenance of secrecy, accuracy and timely delivery of the material is essential part of work and has obtained GST registration in the state of Uttar Pradesh for the purpose.
3. The applicant has sought advance ruling in respect of the following questions:
| 1. |
|
Whether Services of Confidential Printing of Question Papers, OMR sheets, Answer Booklets, Certificates etc. provided by the applicant to Educational Institutions, specifically to various Central / State / Private Universities / Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
| 2. |
|
Whether Information Technology Services like Networking, creating Informative Web-sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Institutions like various Central / State / Private Universities are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
| 3. |
|
Whether Information Technology Services like Networking, creating Informative Web-sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Boards / Commissions like various Central / State / Private Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
| 4. |
|
Whether supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Educational Institutions is exempt. If not, what is the rate of tax applicable thereon along-with HSN/SAC Code. |
| 5. |
|
Whether supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Other than Educational Institutions is exempt. If not, what is the rate of tax applicable thereon along-with HSN/SAC Code. |
4. The question is about applicable GST rate under the provisions of CGST Act and liability to pay GST, hence is admissible under Section 97(2)(a) of the CGST Act 2017. Further, as per declaration given by the applicant in Form ARA-01, the issue raised by the applicant is neither pending nor decided in any proceedings under any of the provisions of the Act, against the applicant.
5. Statement of relevant facts having a bearing on the question(s) raised :
| I. |
|
The applicant is primarily engaged in the following business activities: – |
| a. |
|
Printing of OMR Sheets, Question Papers including Question Booklets of Educational Institutions / Boards, which requires maintenance of secrecy, accuracy and timely delivery of the material; |
| b. |
|
Providing IT Services, Developing IT Infra for the benefit of the Students / Candidates, like Networking, Informative Web Sites of the Institution, or any other IT Services required for Pre/Post Examination Work; |
| C. |
|
Pre-Examination Services – Designing, Developing, and Managing web-based applications and related services for conducting Online/ Offline examinations. Pre-examination services include Registration of candidates (Online/Offline), Generation of Admit Cards, Roll List, Desk Slips and providing other services, as per the requirement of the customers, Installation of CCTV cameras in centers, Frisking services, biometric services, etc.; |
| d. |
|
Post-Examination Services – Services of scanning & processing of Examinations results, Printing of Tabulation Register, Mark Sheets, Degrees, Transcript, Migration, Provisional Degrees, Coding and Decoding of Answer Sheets, Publication of Result in Website or any other media as per the client needs or any other mandatory services for the declaration of the result. |
| II. |
|
The Applicant has been undertaking the job of printing question papers, providing IT Infrastructure, Pre & Post Examination Services for different Universities / Educational Boards including various Central Universities, State Universities, Private Universities, State Government Boards, Central Government Boards, Public Sector Undertakings and Commissions conducting recruitment examinations. Applicant has provided the Sample Copy of Work Orders received by the applicant from different Universities / Educational Institutions. |
| III. |
|
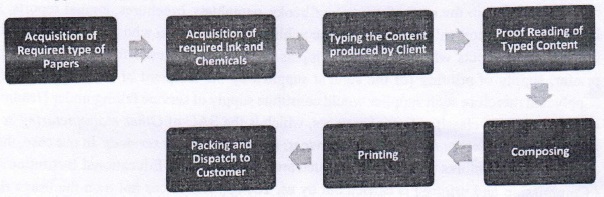
The applicant adopts the following process w.r.t. its printing services: – |
6. The applicant has submitted their interpretation of law as under-
| I. |
|
That the term ‘supply’ has been inclusively defined in the CGST / UPGST Act 2017. The meaning and scope of supply under GST can be understood in terms of following three parameters, which can be adopted to characterize a transaction as supply: – |
| (a) |
|
Supply must be of goods or services. Supply of anything other than goods or services does not attract GST; |
| (b) |
|
Supply should be made for a consideration; |
| (c) |
|
Supply should be made in the course or furtherance of business; |
| II. |
|
The appellant conducts his business by printing the contents provided by the customers on the printing material as required by the customers. The applicant submits that the printing activity in the present case is also combined with security features SO as to prevent misuse by unauthorized persons. The inherent security features are as follows: – |
| • |
|
Invisible Original Mark |
| • |
|
Non-Scan able Student Info |
| • |
|
Watermark of University logo |
| • |
|
Transparent University logo |
| • |
|
Non scan able Data & Time of Printing |
| • |
|
Hidden Security in background layer |
| • |
|
Holographic Gold Color Logo |
| • |
|
Guilloche Pattern, etc. |
| III. |
|
As per the understanding of the applicant, the activity of printing carried out by the applicant is a supply of service. The CBIC in its Para – 4 of Circular No. 11/11/2017-GST dated 20-10-2017 has clarified that in the case of printing of books, pamphlets, brochures, annual reports, and the like, where only content is supplied by the publisher or the person who owns the usage rights to the intangible inputs while the physical inputs including paper used for printing belong to the printer, supply of printing [of the content supplied by the recipient of supply] is the principal supply and therefore such supplies would constitute supply of service falling under Heading 9989 of the scheme of classification of services, which is the SAC of Other manufacturing services; publishing, printing and reproduction services; material recovery services. In our case, the entire content and its features that are to be printed are provided by the Educational Institution / Board / Commission and printing is carried out by us. The applicant does not own the usage rights to the said content and hence our activity is a supply of services. |
| IV. |
|
In terms of Section – 8 of CGST / UPGST Act 2017, the tax liability on a composite or a mixed supply shall be determined in the following manner namely: – |
| (a) |
|
a composite supply comprising two or more supplies one of which is a principal supply, shall be treated as a supply of such principal supply; and |
| (b) |
|
a mixed supply comprising two or more supplies shall be treated as a supply of that particular supply which attracts the highest rate of tax. |
‘Principal Supply’ means the supply of goods or services which constitutes the predominant element of a composite supply and to which any other supply forming part of that composite supply is ancillary . – Section 2(90) of CGST / UPGST Act 2017.
‘Composite Supply’ means a supply made by a taxable person to a recipient comprising of two or more taxable supplies of goods or services or both, or any combination thereof, which are naturally bundled and supplied in conjunction with each other in the ordinary course of business, one of which is a principal supply.
| V. |
|
The applicant further submits that under the GST Law, a different meaning has been accorded, by treating the said activity as supply of service instead of supply of goods in as much as the applicant does not own the goods at any stage in view of the inherent security features, which cannot be supplied to any other person due to fiduciary value. In view of the above, the services rendered in the printing industry, particularly in cases where the design / data is provided by the customer, are recognized to be a service. |
| VI. |
|
The applicant further submits that the aforesaid services of printing pre-examination items, post- examination items and scanning and processing of results provided by the applicant to an educational institution is towards conduct of examination. The services are normally not carried out by the educational institution themselves but has to be outsourced to other service providers due to lack of infrastructure for printing, administrative convenience, confidentiality, volume etc. Accordingly, when such Services are procured by the educational institution, they tantamount to the services relating to conduct of examination, which will aptly fall within the ambit of exemption outlined under Entry No. 66 of the Notification No. 12/2017-Central Tax (Rate) dated 28th June 2017 as amended. Hence, the said exemption notification has to be applied to the applicant’s case. |
| VII. |
|
The services provided by the applicant to the Educational Institutions / Boards by way of printing of marksheets, certificates etc., act as a medium for communication of examination results to students. The said activity acts as a last leg towards completion of the activity of conducting the examination process by the educational institution. Hence, the applicant submits that the aforesaid exemption as outlined in the notification will be applicable to the applicant’s case. Thus, in terms of our understanding, the services provided by the applicant to the educational institutions by way of supply of post-examination materials will not be liable to GST. VIII.Considering the aforesaid, the applicant submits that the services being rendered by it to Educational Institutions are exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 as amended, which is reproduced hereunder for ready reference: – |
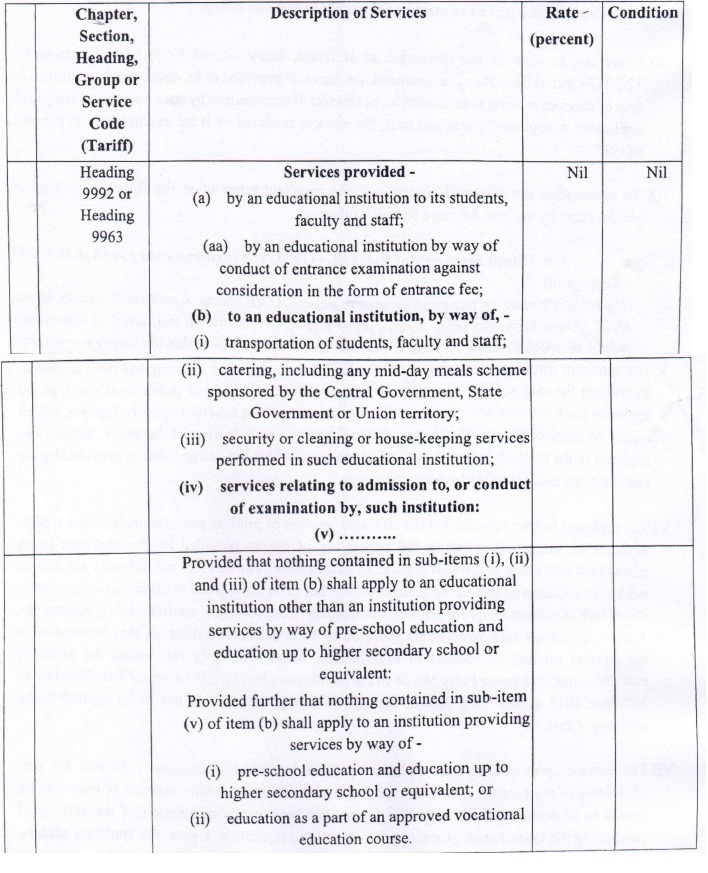
Definitions – For the purposes of this notification, unless the context otherwise requires, –
(y) “educational institution” means an institution providing services by way of,-
(i) pre-school education and education up to higher secondary school or equivalent;
(ii) education as a part of a curriculum for obtaining a qualification recognised by any law for the time being in force;
(iii) education as a part of an approved vocational education course;
| IX. |
|
Therefore, in view of our discussion as aforesaid, Entry No. 66(b)(iv) of Notification No. 12/2017Central Tax (Rate), as amended, i.e. ‘services provided to an educational institution, by way of services relating to admission to, or conduct of examination by such institution’ is squarely applicable in applicant’s case and thus, the services rendered by it are exempted from payment of GST. |
| X. |
|
To substantiate the aforesaid contentions, the appellant relies upon the following rulings on similar issue by various Advance Ruling Authorities: – |
| a. |
|
Y S Hitech Secure Print (P.) Ltd., In re 100 GST 357/78 GSTL 552 (AAR – TELANGANA). |
‘Supply of Printing of test papers/question papers, OMR sheets, Certificates, Marks Memo, MICR cheque books etc. using his own paper and ink to educational institutions is a composite supply, of which Printing services is the principal supply which makes the supply exempt from payment of GST as per Sr. No. 66(b)(iv) of Notification No. 12/2017-CT(R) as detailed supra.’
| b. |
|
V S Hi-Tech Security Forms (P.) Ltd., In re /[2024] 80 GSTL 185 (AAR – TELANGANA). |
“7.27 The applicant claims that he supplies Printing of test papers/question papers, OMR sheets, Certificates, Marks Memo, MICR cheque books etc. using his own paper and ink to educational institutions. This is a composite supply, of which Printing services is the principal supply, as defined under Section 2(90) of the Central Goods and Services Tax Act, which makes HSN classification of the supply to be done on printing services which falls under heading 9989. As it is a service done to educational institutions the exemption under S. No. 66 (b) (iv) of Notification No. 12/2017-CT(R) can be availed by him as the said Notification details the services provided to educational institution which are exempt. The same is clarified by Circular No. 151/07/2021-GST CBIC- 190354/36/2021dated: 17.06.2021 while dealing with the issue of supply of various services by National and State Boards.’
| c. |
|
Universal Print Systems., In re 93 GST 568/ 66 GSTL 245 (AAR – A.P.). |
| “In |
|
the instant case, the educational institutions as referred to by the applicant for whom the supplies of the services of printing of examination related material are made/intended to be made are Andhra University, Visakhapatnam, Satavahana University, Board of Secondary Education, Andhra Pradesh; Krishna University, Board of Higher Secondary Examination, Government of Kerala and Dr. B.R. Ambedkar Open University. All these institutions invariably fall under the category of “educational institution” as they fulfil the criterion of ‘institution providing services by way of, – (ii) education as a part of a curriculum for obtaining a qualification recognised by any law for the time being in force;’ |
Further, with reference to the services provided by the applicant, they are nothing but ‘services relating to admission to, or conduct of examination by, such institution’ falling under Sl. No. 66 of the said exemption Notification No. 12/2017-CGST (Rate), dated 28-6-2017 as amended.”
| d. |
|
Saraswaty Press Ltd., In re (AAR – WEST BENGAL). |
“The services of printing question papers for conduct of examinations to educational institutions, supplied by the applicant will be covered by Sl. No 66 of the Notification No. 12/2017Central tax (Rate) as amended, and therefore shall be treated as exempt supply.”
| e. |
|
Gopson Printers (P.) Ltd., In re (AAR – U.P.). |
“As per the circular, if the activity of printing gives essential character to the printed product, it will be supply of service. If the usage of the product gives essential character, it will be supply of goods. In the case of the applicant, the activity of printing gives essential character to the printed product, hence it can be classified as supply of service.”
| XI. |
|
That based on a reading of the above cited case laws and interpretation of the applicant, it is submitted that, in the present scenario, GST is not payable by the Applicant in the instant case. |
7. The application for advance ruling was forwarded to Assistant Commissioner, Central Tax & Central Excise, Division- Division II Allahabad vide letter dated 21.02.2025 to offer his comments/views/verification report on the matter. The para-wise replies as submitted by concerned office is as under:
Para-I. Gopson Printers (P.) Ltd., (Supra) the authority for Advance Ruling (AAR) in Uttar Pradesh has issued a Comprehensive decision concerning the GST treatment of printing services provided to educational institutions. M/s Gopsons Printers Pvt Ltd, the applicant, sought, clarity on whether their printing activities for educational boards and universities constitute the supply of goods or services under the GST framework. The ruling addresses critical aspects of GST applicability and exemptions for service related to the education.
Para-II. The taxability of IT service under GST depends upon its nature as whether it an intermediary service or direct service. Is the IT service is intermediate service; it is taxable at the rate of eighteen percent.
Para-III. The taxability of IT service under GST depends upon its nature as whether it an intermediary service or direct service. Is the IT service is intermediate service; it is taxable at the rate of eighteen percent.
Para-IV. Printing and Supply of course material book brochures periodicals exempted from GST.
Para-V. Printed books, brochures, and leaflets (HSN-4901) attract a 5% GST Newspapers, Journals and periodicals published at least four times (HSN-4902) are exempted from GST.
Further, it is to submit that no any application is pending or decided under of the provisions of the Act.
8. The applicant was granted personal hearing on 16.04.2025 which was attended by Mr. Rishabh Mishra, CA and Mr. Peeyush Kr. Kesharwani, CA Authorized Representatives during which they reiterated the submissions made in the application of advance ruling.
DISCUSSION AND FINDING
9. At the outset, we would like to make it clear that the provisions of both the CGST Act and the UPGST Act are the same except for certain provisions. Therefore, unless a mention is specifically made to such dissimilar provisions, a reference to the CGST Act would also mean a reference to the same provision under the UPGST Act. Further to the earlier, henceforth for the purposes of this Advance Ruling, a reference to such a similar provision under the CGST Act / UPGST Act would be mentioned as being under the ‘CGST Act’.
10. We have gone through the Form GST ARA-01 filed by the applicant and observed that the applicant has ticked following issues on which advance ruling required-
| a. |
|
Applicability of a notification issued under the provisions of this act; |
| b. |
|
Determination of the liability to pay tax on any goods or services or both. |
11. We have gone through the submissions made by the applicant and have examined the interpretation submitted by them. At the outset, we find that the issue raised in the application is squarely covered under Section 97(2) of the CGST Act 2017 being a matter related to applicability of a notification issued under the provisions of this act and Determination of the liability to pay tax on any goods or services or both. We therefore, admit the application for consideration on merits.
12. It is seen from the records that the applicant is primarily engaged in the following business activities: –
| a. |
|
Printing of OMR Sheets, Question Papers including Question Booklets of Educational Institutions / Boards, which requires maintenance of secrecy, accuracy and timely delivery of the material; |
| b. |
|
Providing IT Services, Developing IT Infra for the benefit of the Students / Candidates, like Networking, Informative Web Sites of the Institution, or any other IT Services required for Pre/Post Examination Work; |
| c. |
|
Pre-Examination Services – Designing, Developing, and Managing web-based applications and related services for conducting Online/ Offline examinations. Pre- examination services include Registration of candidates (Online/Offline), Generation of Admit Cards, Roll List, Desk Slips and providing other services, as per the requirement of the customers, Installation of CCTV cameras in centers, Frisking services, biometric services, etc.; |
| d. |
|
Post-Examination Services – Services of scanning & processing of Examinations results, Printing of Tabulation Register, Mark Sheets, Degrees, Transcript, Migration, Provisional Degrees, Coding and Decoding of Answer Sheets, Publication of Result in Website or any other media as per the client needs or any other mandatory services for the declaration of the result. |
13. The applicant in the present application has sought advance ruling on following question/clarification-
| a. |
|
Whether Services of Confidential Printing of Question Papers, OMR sheets, Answer Booklets, Certificates etc. provided by the applicant to Educational Institutions, specifically to various Central / State / Private Universities / Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
| b. |
|
Whether Information Technology Services like Networking, creating Informative Web- sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Institutions like various Central / State / Private Universities are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
| c. |
|
Whether Information Technology Services like Networking, creating Informative Web- sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Boards / Commissions like various Central / State / Private Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017- Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
| d. |
|
Whether supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Educational Institutions is exempt. If not, what is the rate of tax applicable thereon along-with HSN/SAC Code. |
| e. |
|
Whether supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Other than Educational Institutions is exempt. If not, what is the rate of tax applicable thereon along-with HSN/SAC Code. |
14. Now we take up the issue related to above questions one by one. The applicant has sought clarification regarding the nature of supply whether the aforesaid activity as mentioned in above para 13(a) would be considered as supply of goods or supply or service.
In this regard, clarification has been issued vide circular No 11/11/2017 GST dated 20.10.2017, wherein it has been clarified that :-
“2. In the above context, it is clarified that supply of books, pamphlets, brochures, envelopes, annual reports, leaflets, cartons, boxes etc. printed with logo, design, name, address or other contents supplied by the recipient of such printed goods, are composite supplies and the question, whether such supplies constitute supply of goods or services would be determined on the basis of what constitutes the principal supply.
3. Principal supply has been defined in Section 2(90) of the Central Goods and Services Tax Act as supply of goods or services which constitutes the predominant element of a composite supply and to which any other supply forming part of that composite supply is ancillary.
4. In the case of printing of books, pamphlets, brochures, annual reports, and the like, where only content is supplied by the publisher or the person who owns the usage rights to the intangible inputs while the physical inputs including paper used for printing belong to the printer, supply of printing [of the content supplied by the recipient of supply] is the principal supply and therefore such supplies would constitute supply of service falling under heading 9989 of the scheme of classification of services.”
As per the circular, if the activity of printing gives essential character to the printed product, it will be supply of service. If the usage of the product gives essential character, it will be supply of goods. In this case of the applicant providing “service of confidential printing” has submitted that the contents are provided by the customer on the printing materials as required by the customer, hence the activity of printing gives essential character to the printed product, hence it can be classified as supply of service.
15. The applicant has further sought ruling regarding the applicability of exemption extended vide Sr No 66 of Notification No 12/2017-CT (Rate) as amended vide Notification No 2/2018-CT (Rate) dated 25.01.2018 in respect of services relating to activity of Confidential Printing activity as mentioned in above para 13(a).
In this regard we find that Notification No 12/2017-CT(Rate) provides exemption to services provided:
| (b) |
|
to an educational institution by way of,- |
| (iv) |
|
services relating to admission to, or conduct of examination by, such institution. |
Sr. No 66 of the said Notification as amended vide Notification No 02/2018-CT (Rate) provides as follows:
“66. Heading 9992 Services provided –
| (a) |
|
by an educational institution to its students, faculty and staff; |
| (aa) |
|
by an educational institution by way of conduct of entrance examination against consideration in the form of entrance fee, |
| (b) |
|
to an educational institution, by way of,- |
| (i) |
|
transportation of students, faculty and staff; |
| (ii) |
|
catering, including any mid-day meals scheme sponsored by the Central Government, State Government or Union territory; |
| (iii) |
|
security or cleaning or house-keeping services performed in such educational institution; |
| (iv) |
|
services relating to admission to, or conduct of examination by, such institution; |
| (v) |
|
supply of online educational journals or periodicals; |
Provided that nothing contained in sub-items (i), (ii) and (iii) of item (b) shall apply to an educational institution other than an institution providing services by way of pre-school education and education up to higher secondary school or equivalent.”
Provided further that nothing contained in sub-item (v) of item (b) shall apply to an institution providing services by way of –
| (i) |
|
pre-school education and education upto higher secondary or equivalent; or |
| (ii) |
|
education as a part of an approved vocational education course.” |
Further Educational institution has been defined in at 2(y) of the Notification 12/2017 CT (Rate) as follows :-
| “(y) |
|
“educational institution” means an institution providing services by way of,- |
| (i) |
|
pre-school education and education up to higher secondary school or equivalent; |
| (ii) |
|
education as a part of a curriculum for obtaining a qualification recognised by any law for the time being in force; |
| (iii) |
|
education as a part of an approved vocational education course;” |
As such, there is no restriction of ‘upto higher secondary level’ in respect of exemption covered in entry 66(b)(iv) of the Notification no 12/2017-CT (Rate) dated 28.06.2017.
Hence services relating to activity of Confidential Printing of Question Papers, OMR sheets, Answer Booklets, Certificates required by an educational institution, within the meaning of educational institution as defined under Notification 12/2017-CT (Rate) pertaining to admission to, or conduct of examination by educational institutions is exempted from GST vide Notification 12/2012-CT (Rate). It is to be noted that exemption is given only to services and not to goods in this Notification and the principal supply of the composite supply made by the applicant is printing services.
16. Now we take the second issue i.e. Information Technology Services provided by the applicant specifically to Educational Institutions like various Central / State / Private Universities Which is regarding the applicability of exemption extended vide Sr No 66 of Notification No 12/2017-CT (Rate) as amended vide Notification No 2/2018-CT (Rate) dated 25.01.2018 in respect of services as mentioned in above para 13(b).
In this regard we find that Notification No 12/2017-CT(Rate) provides exemption to services provided:
| (c) |
|
to an educational institution by way of,- |
| (iv) |
|
services relating to admission to, or conduct of examination by, such institution. |
As such, there is no restriction of ‘upto higher secondary level’ in respect of exemption covered in entry 66(b)(iv) of the Notification no 12/2017-CT (Rate) dated 28.06.2017.
Hence, we find that information technology Services like Networking, creating Informative Web-sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Institutions, within the meaning of educational institution as defined under Notification 12/2017-CT (Rate) pertaining to admission to, or conduct of examination by educational institutions is exempted from GST vide Notification 12/2012-CT (Rate).
17. Now we take the third issue i.e Whether Information Technology Services provided by the applicant specifically to Educational Boards / Commissions like various Central / State / Private Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 in respect of services as mentioned in above para 13(c).
18. Sr. No. 22 of Notification No. 11/2017-Central Tax (Rate) as amended reads as follows:
| S1. No. |
Chapter, Section or Heading |
Description of Services |
Rate (per cent.) |
Condition |
| 22(ii) |
Heading 9984 |
(ii) Telecommunications, broadcasting and information supply services. |
9 |
– |
Information Technology Services like Networking, creating Informative Web-sites of Educational Institution, or any other IT Services are taxable at 18% and SAC Code of such services are SAC 9984 subject to conditions and exemptions.
In this connection, it is emphasised that the Central Board of Excise and Customs has issued a Circular No. 151/07/2021-GST, dated 17-6-2021 (F. No. CBIC-190354/36/2021) and clarified that activities falling under Serial No. 66 of Notification No. 12/2017 are exempted. The relevant portion is reproduced below –
“3.1 The following services supplied by an educational institution are exempt from GST vide Sl. No. 66 of the Notification No. 12/2017-Central Tax (Rate), dated 28-6-2017, Services provided –
| (a) |
|
by an educational institution to its students, faculty and staff; |
| (aa) |
|
by an educational institution by way of conduct of entrance examination against consideration in the form of entrance fee; |
3.2 Similarly, services provided to an educational institution, relating to admission to, or conduct of examination is also exempt from GST (Sl. No. 66(b)(iv)-12/2017-C.T. (Rate)).
3.3 Educational institutions are defined at 2(y) of the said notification as follows –
“(y) educational institution” means an institution providing services by way of,
(i) pre-school education and education up to higher secondary school or equivalent;
(ii) education as a part of a curriculum for obtaining a qualification recognized by any law for the time being in force;
(iii) education as a part of an approved vocational education course;”
Further, clause (iv) of Explanation of said notification reads as below:
“(iv) For removal of doubts, it is clarified that the Central and State Educational Boards shall be treated as Educational Institution for the limited purpose of providing services by way of conduct of examination to the students”
4. Taking into account the above, the GST Council has recommended, to clarify as below:
| (i) |
|
GST is exempt on services provided by Central or State Boards (including the boards such as NBE) by way of conduct of examination for the students, including conduct of entrance examination for admission to educational institution [under S. No. 66 (aa) of notif No. 12/2017- CT(R)]. Therefore, GST shall not apply to any fee or any amount charged by such Boards for conduct of such examinations including entrance examinations. |
| (ii) |
|
GST is also exempt on input services relating to admission to, or conduct of examination, such as online testing service, result publication, printing Circular No. 151/07/2021GST of notification for examination, admit card and questions papers etc, when provided to such Boards [under S. No. 66 (b) (iv) of notice f No. 12/2017- CT(R)]. |
| (iii) |
|
GST at the rate of 18% applies to other services provided by such Boards, namely of providing accreditation to an institution or to a professional (accreditation fee or registration fee such as fee for FMGE screening test) so as to authorise them to provide their respective services |
Thus, “Central and State Educational Boards” are treated as Educational Institution for the limited purpose of providing services by way of conduct of examination to the students. Therefore, Educational Boards / Commissions like various Central / State / Private Boards are ‘Educational Institution’ in SO far as it provides services by way of conduct of examination, including any entrance examination, to the students.
Therefore, GST is exempted on Information Technology Services like Networking, creating Informative Web-sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Boards under S. No. 66(b)(iv) of Notification No. 12/2017-CT (Rate). Therefore, the suppliers of these services can avail the benefit of exemption from payment of GST on these services.
However, Boards or Commissions cannot be treated as educational institutions under GST, except when they are providing services related to the conduct of examinations for students. For instance, if a Board or Commission performs functions related to employment or recruitment rather than education, it does not qualify as an educational institution under GST.
As discussed above, the Information Technology Services provided by the applicant specifically various Recruitment Commissions of State and Central Government are not exempted in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 and is taxable at 18% (CGST 9 % + SGST 9% or IGST 18%) under SAC code 9984.
19. Now we take the fourth issue whether the supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Educational Institutions is exempted or not. We examine this issue in the light of entry 66(b)(v) of the Notification no 12/2017-CT (Rate) dated 28.06.2017 as amended by CTR Notification No. 2/2018 dated 25th Jan. 2018 reproduced as under:
“66. Heading 9992 Services provided
……………………………..
(b) to an educational institution, by way of,-
……………………………..
(v) supply of online educational journals or periodicals;
Provided that nothing contained in sub-items (i), (ii) and (iii) of item (b) shall apply to an educational institution other than an institution providing services by way of pre-school education and education up to higher secondary school or equivalent.”
Provided further that nothing contained in sub-item (v) of item (b) shall apply to an institution providing services by way of –
(iii) pre-school education and education upto higher secondary or equivalent; or
(iv) education as a part of an approved vocational education course.”
The Notification No. 2/2017 – Central Tax (Rate), dated 28th June 2017 exempt “Printed books, including Braille books”. Hence, Supply of printed books are ‘nil’ rated, irrespective of the fact as to whom they are supplied. All printed books, whether they are supplies to educational institute or other than educational institute are ‘nil’ rated as per heading 4901. Sr. No. 119 of CTR Notification No. 2/2017
Brochures, Couse Materials and prospectus are taxable at @ 5% (CGST 2.5% + SGST 2.5% or IGST 5%) under HSN code is 4901 10 20 as per Notification no 01/2017-CT (Rate) dated 28.06.2017 as amended whether they are supplied to educational institute or other than educational institute.
Further, Sr. No. 22 of Notification No. 11/2017-Central Tax (Rate) as amended by CTR Notification No. 13 dated 26th July 2018 reads as follows:
| S1. No. |
Chapter, Section or Heading |
Description of Services |
Rate (per cent.) |
Condition |
| 22 |
Heading 9984 |
(i) Supply consisting only of e-book.
Explanation.- For the purposes of this notification, “e-books” means an electronic version of a printed book (falling under tariff item 4901 in the First Schedule to the Customs Tariff Act, 1975 (51 of 1975)) supplied online which can be read on a computer or a hand held device.
|
2.5 |
|
|
|
(ii) Telecommunications, broadcasting and information supply services. |
9 |
– |
Thus we find the e-Books are taxable are taxable at @ 5% from 27th of July, 2018 whether they are supplied to educational institute or other than educational institute.
Further, we find that only supply of Online Education Journals and Periodicals to Supplied to educational institutions providing education as a part of a curriculum for obtaining a qualification recognized by any law for the time being in force are exempted from levy of GST as per entry 66(b)(v).
Thus, Supply of online educational journals and periodicals to educational institutions providing pre-school education and education up to higher secondary school or equivalent, to educational institutions providing approved vocational education course and supplied to any entity, other than an “educational institution” shall be taxable at 18% (CGST 9% + SGST 9% or IGST 18%) under SAC code 9984.
As discussed above, we conclude that the supply of Books to Educational Institutions is exempted from the levy of GST. However, supply of e-Books is taxable at @ 5%. Brochures Further, supply of Course Materials, Brochures and Prospectus to educational institutions is taxable at 5% (CGST 2.5% + SGST 2.5% or IGST 5%) under HSN code 4901 10 20; supply of Online Education Journals and Periodicals to educational institutions providing education as a part of a curriculum for obtaining a qualification recognized by any law is exempted from the levy of GST.
20. Now we take the fifth issue whether the supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to other than the Educational Institutions is exempted or not.
Supply of printed books are ‘exempted from the levy of GST as discussed in above para. However, supply of e-Books are taxable at @ 5%. Brochures, Couse Materials and prospectus are taxable at @ 5% (CGST 2.5% + SGST 2.5% or IGST 5%) under HSN code 4901 10 20 as per Notification no 01/2017-CT (Rate) dated 28.06.2017 as amended whether they are supplies to educational institute or other than educational institute.
Supply of online educational journals and periodicals to other than an “educational institution” shall be taxable at 18% (CGST 9% + SGST 9% or IGST 18%) under SAC code 9984 as discussed in above para.
In the view of the above, we conclude that Supply of Books to other than Educational Institutions is exempted as well from the levy of GST. However, the supply of Course Materials, Brochures and Prospectus to other than educational institute is taxable at 5% (CGST 2.5% + SGST 2.5% or IGST 5%) under HSN code is 4901 10 20; and supply of Online Education Journals and Periodicals to Other than Educational Institutions is taxable at 18 (CGST 9 % + SGST 9 % or IGST 18 %) under HSN code 998431.
21. In view of the above discussions, we, both the members unanimously rule as under;
RULING
| a. |
|
Whether Services of Confidential Printing of Question Papers, OMR sheets, Answer Booklets, Certificates etc. provided by the applicant to Educational Institutions, specifically to various Central / State / Private Universities / Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
Answer: In affirmative for services relating to admission to, or conduct of examination, by an educational institution, within the meaning of educational institution as defined under Notification 12/2017-CT (Rate).
| b. |
|
Whether Information Technology Services like Networking, creating Informative Web- sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Institutions like various Central / State / Private Universities are Exempt in terms of Entry No. 66 of Notification No. 12/2017-Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
Answer: In affirmative for services relating to admission to, or conduct of examination, by an educational institution, within the meaning of educational institution as defined under Notification 12/2017-CT (Rate).
| c. |
|
Whether Information Technology Services like Networking, creating Informative Web- sites of Educational Institution, or any other IT Services required for Pre/Post Examination Work provided by the applicant specifically to Educational Boards / Commissions like various Central / State / Private Boards / various Recruitment Commissions of State and Central Government are Exempt in terms of Entry No. 66 of Notification No. 12/2017- Central Tax (Rate) dated 28-06-2017 (as amended from time to time). If not, what is the applicable Rate of tax and SAC Code of such services. |
Answer: In affirmative for services provided by the applicant to an educational Boards, within the meaning of educational institution as defined under Notification 12/2017-CT (Rate). But Information Technology Services provided by the applicant specifically various Recruitment Commissions of State and Central Government is not exempted and is taxable 18 % (CGST 9 % + SGST 9% or IGST 18 %) under SAC code 9984.
| d. |
|
Whether supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Educational Institutions is exempt. If not, what is the rate of tax applicable thereon along-with HSN/SAC Code. |
Answer: Supply of Printed Books to Educational Institutions is exempted from the levy of GST. However, supply of e-Books is taxable at @ 5%. Further, supply of Course Materials, Brochures and Prospectus to educational institutions is taxable at 5% (CGST 2.5% + SGST 2.5% or IGST 5%) under HSN code 4901 10 20; supply of Online Education Journals and Periodicals to educational institutions providing education as a part of a curriculum for obtaining a qualification recognized by any law is exempted from the levy of GST.
However, Supply of online educational journals and periodicals to educational institutions providing pre-school education and education up to higher secondary school or equivalent and to educational institutions providing approved vocational education course shall be taxable at 18% (CGST 9% + SGST 9% or IGST 18%) under SAC code 9984.
| e. |
|
Whether supply of Course Materials, Books, Brochures, Prospectus, Online Education Journals and Periodicals to Other than Educational Institutions is exempt. If not, what is the rate of tax applicable thereon along-with HSN/SAC Code. |
Answer: Supply of Printed Books to other than Educational Institutions is exempted from the levy of GST. However, supply of e-Books are taxable at @ 5% .Further, the supply of Course Materials, Brochures and Prospectus to other than educational institute is taxable at 5% (CGST 2.5% + SGST 2.5% or IGST 5%) under HSN code is 4901 10 20; and supply of Online Education Journals and Periodicals to Other than Educational Institutions is taxable at 18% (CGST 9 % + SGST 9% or IGST 18 %) under SAC code 9984.
All the above five queries are answered only with reference to the products associated with the conduct of Examinations and the Educational boards/Institutions within the purview of the definition in the Act
22. This ruling is valid only within the jurisdiction of Authority for Advance Ruling Uttar Pradesh and subject to the provisions under Section 103(2) of the CGST Act, 2017 until and unless declared void under Section 104(1) of the Act.