


Reassessment Notice Served By Affixture At Wrong Address Without Following Proper Procedure Is Invalid
Issue
Whether a notice under Section 148 served by affixture at an incorrect address, without adhering to the procedure prescribed under Rules 17 to 20 of Order V of the Code of Civil Procedure (CPC), constitutes valid service to initiate reassessment proceedings under Section 147.
Facts
-
The assessee’s case for Assessment Year 2020-21 was reopened under Section 147 based on information from the Registrar of Stamp Duty regarding a registered property transaction.
-
The registered sale deed clearly recorded the assessee’s correct address as CB-278, 2nd Floor, Ring Road, Naraina, New Delhi-28.
-
The Assessing Officer attempted to serve the notice under Section 148 at a different address, i.e., CB-171, Ring Road, Naraina, New Delhi-28.
-
When the notice could not be delivered at the incorrect address, the Revenue attempted service by affixture and proceeded with the reassessment.
-
The service file lacked documentation of due diligence, and there was no witness verification from locals or neighbors confirming that affixture occurred at the correct property.
-
The Department’s own correspondence failed to clarify or establish which location was treated as the proper or correct address.
Decision
-
Held, yes. Since the due statutory procedure for substituted service of notice by affixture under Rules 17 to 20 of Order V of the CPC was not adhered to, the notice could not be treated as validly served on the assessee.
-
Held, yes. Consequently, the notice under Section 148 was invalidly served, rendering the reassessment proceedings initiated under Section 147 unsustainable in law.
Key Takeaways
-
Strict Compliance with CPC Rules for Substituted Service: Substituted service by affixture is valid only if the mandatory procedures under Order V, Rules 17 to 20 of the CPC (including due diligence, witness verification, and proper reporting) are strictly followed.
-
Service at Correct Address is Mandatory: Sending statutory notices to an incorrect address—especially when the correct address is available on registered public documents—invalidates the service.
-
Jurisdictional Pre-requisite: Proper service of notice under Section 148 is a condition precedent to vesting jurisdiction in the Assessing Officer to initiate and complete reassessment under Section 147.
IN THE ITAT DELHI BENCH ‘SMC’
Poonam Devi
v.
Income-tax Officer
S. Rifaur Rahman, Accountant Member
IT Appeal No. 2472 (Delhi) OF 2026
[Assessment year 2020-21]
[Assessment year 2020-21]
SEPTEMBER 23, 2026
Ramesh Chander, Adv. for the Appellant. Manoj Kumar, Sr. DR for the Respondent.
ORDER
1. This appeal is filed by the assessee against the order of ld. Commissioner of Income-tax (Appeals)/National Faceless Appeal Centre (NFAC), Delhi [“Ld. CIT(A)”, for short] dated 13.01.2026 for the Assessment Year 2020-21 raising following grounds of appeal :-
“1. That, on the facts and in the circumstances of the case, appellate order passed by the Ld. First Appellate Authority in the NFAC is unsustainable in law as being violative of the binding provisions of section 250(2)(a) of the Income Tax Act, 1961 and passing the order without affording the Appellant any facility or opportunity of physical or virtual hearing.
2. That, on the facts and in the circumstances of the case, appellate order passed by the Ld. First Appellate Authority in the NFAC is bad in law in as much that while as per the Intimation dated 09-07-2024 served case was assigned to the Assessment Unit for completion of assessment in faceless manner as prescribed u/s 144B of the Act whereas the assessment is actually seen done in a non-faceless manner by the ITO Ward 50(1), Delhi.
3. That, on the facts and in the circumstances of the case, the Ld. First Appellate Authority in the NFAC has erred in law in dismissing the appeal against the assessment order disregarding that it was unsustainable as its initiation u/s148(b) was on information/material showing the purchase value at 75 lacs whereas the purchase value was just at 25 lacs.
4. That, on the facts and in the circumstances of the case order passed u/s 250 by the Ld. First Appellate Authority in the NFAC, in dismissing the appeal is bad in law as it disregarded that very assessment made u/s 147 r.w.s. 144 dated 2903-2025 was bad in law for having been passed without disclosing as to why provisions of section 144 of the Income Tax Act, 1961 were invoked.
5. That, on the facts and in the circumstances of the case order passed by the Ld. First Appellate Authority in the NFAC is unsustainable in law as having ignored, without just reasons, that action of the Assessing Officer in making addition of Rs.22,10,000/- u/s 56(2)(x)was bad in law for being firstly violative of the principles of natural justice inasmuch as that before invoking section 56(2)(x) no opportunity was given and secondly because provisions of section 56(2)(x) were inapplicable.
6. That, on the facts and in the circumstances of the case the Ld. First AppellateAuthorityintheNFAChaserredinlawinignoringthatassessment order was non est as being not in conformity with CBDT’s own Instruction F. No. System/ITD/Instruction/AST-DIN/2019-20 dt. 25-10-2019 mandating the ‘User to mention system generated DIN in the relevant order and all its annexures including demand notice, computation sheet etc. before dispatching the same to the assessee’ whereas assessment order and its annexures had different DINs.
7. That, on the facts and in the circumstances of the case the Ld. Appellate Authority in the NFAC erred in law in getting gagged by the assessment order and ignoring that there was no justification for not reducing Rs.2 lacs being the part of the sale consideration paid in cash from the total consideration paid to the Seller of Rs.25 lacs.
8. That, on the facts and in the circumstances of the case the Ld. First Appellate Authority in the NFAC erred in law in not holding that Assessing Officer had erred in law while computing the taxable value, in not reducing 10% value being 2,50,000/- as mandated u/s 56(2)(x)(B)(ii) of the Act.
9. That, in the facts and circumstances of the case Ld. Ld. First Appellate Authority in the NFAC erred in law in not holding that assessment order was erroneous in not making reference to the Valuation Officer as required under 3rd proviso to section 56(2)(x)(B) of the Act despite that while disputing the stamp valuation being resorted the Appellant had filed the Valuation Report from the Government authorized Valuer thus disputing the Stamp valuation.
10. That, on the facts and circumstances of the case the Ld. First Appellate Authority in the NFAC erred in law in not holding that the AO was in error while computing the taxable income in not reducing the basic exemption limit up to which no return was required to be filed.
11. That, on the facts and in the circumstances of the case the Ld. Ld. First Appellate Authority in the NFAC erred in law in not holding that AO was not justified in not taking note of the fact that the very valuation declared in the sale/purchase document stands accepted in the hands of the Seller as a result of which in the hands of the Appellant too no action was required to be taken more so when no reopening was permissible on the ‘deemed income’ which could not have been the basis of issuing Notice u/s 148A(b).”
2. At the outset of the hearing, ld. AR for the assessee submitted that assessee has filed admission of the additional grounds of appeal and it is purely legal issue and the same are reproduced below :-
“12. That, in the facts and circumstances of the case, the Ld. Commissioner of Income Tax (Appeals) erred in law in not noticing that the initiation of the proceedings 148/148A was without the compliance of the laid down law in as much as the provisions of section L48A were not applicable in view of the information which stood notified u/s 135A of the Income Tax Act, 1961 and hence assumption, of jurisdiction by the AO by seeking approval of the specified authority was bad in law.
13. That, in the facts and circumstances of the case, the Ld. Commissioner of Income Tax (Appeals) erred in law in not noticing that assumption of jurisdiction by the AO to make assessment was a nullity in view of non-service of the Notices required to be issued to acquire jurisdiction.
I4. That, in the facts and circumstances of the case, the Ld. Commissioner of Income Tax (Appeals) erred in law in not noticing that assumption of jurisdiction by the AO to make assessment was a nullity as the very Notice issued w/s 148 was not in conformity with the provisions laid down u/s 148.”
3. Since the above grounds of appeal are purely legal, do not require fresh facts to be investigated and go to the root of the matter, ld. AR of the assessee prayed that the same may be admitted in view of the judgement of National Thermal Power Co. Ltd. v. CIT 358/229 ITR 383 (SC).
4. On the other hand, ld. DR for the Revenue has no objection of admitting the additional ground of appeal being purely legal issue.
5. In view of the reliance made by the ld. AR for the assessee on the judgment of Hon’ble Supreme Court in the case of National Thermal Power Co. Ltd. (supra) and issue being purely legal, we proceeded to admit the additional ground of appeal being a legal issue.
6. At the time of hearing, ld. AR of the assessee specifically argued on Ground No.13 raised in the additional ground. In this regard, ld. AR of the assessee submitted as under :-
“13. That, in the facts and circumstances of the case, the Ld. Commissioner of Income Tax (Appeals) erred in law in not noticing that assumption of jurisdiction by the AO to make assessment was a nullity in view of non-service of the Notices required to be issued to acquire jurisdiction.”
2.1.1 Notice under section 148 dated 19-03-2024 (APB-6)shows address of the Appellant to be ‘CB-171 Ring Road, Naraina, New Delhi-110 028′. In this connection, kind attention is also invited to Sale Deed (APB-32-45)where Appellant is shown a resident of “CB-278, 2nd Floor, Ring Road, Naraina, New Delhi-110 028″. It was this Sale Deed in reference to which the proceedings u/s 148 or u/s 148A(b) or u/s 148A(d) were undertaken. It is not understood as to why despite there being the latest residential address available with the AO in the Sale Deed still Notice u/s 148 was issued at CB-171 Ring Road, Naraina, New Delhi-110 028. Very clearly, issuance of a Notice containing wrong address cannot be said to be validly issued obviously because by necessary implication Law mandates issuance of the Notices etc. at the correct address. Since, the Notice was issued/sent at the wrong address question of it having been served on the Appellant does not arise.
2.1.2 Fact that the Notices including the Notice u/s 148 were not getting served is also borne out of the information which the Appellant obtained under the Right to Information Act, 2005. Relevant documents to the above effect are narrated below;
| (i) | Exhibit-1/1to the instant submissions shows Notice u/s 142(1) dated 30-12-2024 addressed at CB-171 Ring Road, Naraina, Delhi wherein by hand another address ‘CB-378 2nd Floor, Ring Road, Naraina, Delhi‘ is also mentioned disregarding that correct House No. was not CB-378 but was CB-278. This shows nothing but non- service of Notice. |
| (ii) | Exhibit-1/2 to the instant submissions shows service of assessment order dated 30-03-2025 by Affixture at CB-278, Naraina, New Delhi but strangely neither there are Panchas to this effect nor does it indicate at which specific conspicuous place of the premises this Affixture was done. Affixture does not even mention the floor in the building. Without prejudice to the point that there was, as a matter of fact, no Affixture done still it is clear that at CB-278 Notices sent by Post etc. were not getting served which is why alleged Affixture was resorted to. |
| (iii) | Exhibit-1/3 to the instant submissions shows service of Notice issued u/s 148 and the order passed u/s 148A(d) by Affixture at CB-278, Naraina but again neither there are Panchas to this effect nor does it indicate at which specific conspicuous place of the premises this Affixture was done. Affixture does not even mention the floor in the building. Without prejudice to the point that there was, as a matter of fact, no Affixture done still it is clear that at CB-278 Notices sent by Post etc. were not getting served which is why alleged Affixture was resorted to. |
| (iv) | Exhibit-1/4 to the instant submissions shows service at CB-171 Ring Road, Naraina by one Anant Kumar, Notice Server, of Notice/order u/s 148A(b) dated 27-02-2027. As a matter of fact, this Affixture document was merely created in house which becomes clear from the fact that firstly there are no independent Panchas to this effect and secondly the signatures of Ankit Awasthi, Inspector are different from the signatures what we notice in the Affixture Order dated 21-032024 (Exhibit-1/3). This also shows non-service of the Notice sent by Post etc. maliciously creation of Affixture document. |
| (v) | Further, despite Sale Deed being available with the AO showing the latest address of residence being CB-278 Naraina, New Delhi in the Affixtures dated 28-02-2024 (Exhibit-1/4)& 21-03-2024 (Exhibit-1/3) last known address mentioned is CB-171 Naraina, Delhi. |
2.1.3 Without prejudice to the above argument that the Affixtures are actually not done and that they are maliciously created by the AO in house only, it is submitted that Rule 20 (Order V) of the CPC is for service of summons and not for Orders/Notices. This apart, perusal of these Affixtures, though said to be as per Rule 20 of the CPC, will also show that conditions of Rule 20 are otherwise also not at all satisfied in as much as the Notices are not shown affixed at any ‘conspicuous place/part of the house’. On this ground itself this substituted service by Affixture otherwise also is not valid. All this show nothing but ‘non service of Notice issued u/s 148 or of order passed u/s 144 or order u/s 148A(b) or order u/s 148A(d)’ of the Act. Qua the service by Affixture it is submitted that for the reasons mentioned above it is impossible to belief service by Affixture because there are no independent witnesses to this effect of having actually been done except Revenue’s self-serving and maliciously self-created suspicious documents, as shown earlier.
2.1.4 For the purpose of completeness of the issue in hand it is considered necessary to mention that even on the E-mail also Notices had not been served. Information obtained under the Right to Information Act, 2005 (Ehibit-1/5) being the Taxpayer Master Profile shows address of the Appellant to be CB-171, Ring Road, Naraina and E-mail mentioned is ‘arvind77icb@gmail.com’. Exhibit-1/6shows the delivery status of the E-mail (Show Cause Notice for proceedings u/s 148A of the I.T. Act) addressed to ARVIND771CB@GMAIL.COM as ‘Bounced’. This Exhibit also mentions that there was no other Email ID on the system. Probably because of erroneously writing ‘i’ as ‘1’ or ‘l’ the mail got bounced. But it is clear that by E-mail also notices were not served.
3. Thus, non-service of jurisdictional Notice issued u/s 148 physically or by E-mail stands concluded/proved and in view of this the additional ground deserves to be allowed resulting into the quashing of the very assessment proceedings.
(B) ISSUANCE OF NOTICE U/S 148 BAD IN LAW:
1. Additional Ground Nos. 12 & 14 being inter connected on the issue of Notice u/s 148 are taken up together and they read as under;
“12. That, in the facts and circumstances of the case, the Ld. Commissioner of Income Tax (Appeals) erred in law in not noticing that the initiation of the proceedings 148/148A was without the compliance of the laid down law in as much as the provisions of section 148A were not applicable in view of the information which stood notified u/s 135A of the Income Tax Act, 1961 and hence assumption of jurisdiction by the AO by seeking approval of the specified authority was bad in law.
14. That, in the facts and circumstances of the case, the Ld. Commissioner of Income Tax (Appeals) erred in law in not noticing that assumption of jurisdiction by the AO to make assessment was a nullity as the very Notice issued u/s 148 was not in conformity with the provisions laid down u/s 148.”
2.1.0 Both the additional grounds are inter connected and hence they are taken up together for the purpose of making submissions. Undisputed facts are that in the Appellant’s case an order u/s 148A(d) was passed on 19-03-2024 (APB-3) after taking the approval of the specified authority being the PCIT, Delhi-10 on 15-03-2024 recording the Appellant’s case as a ‘fit case for issuance of notice u/s 148 of the Act’. Thereafter, on 19-03-2024 itself Notice u/s 148 (APB-6) was issued requiring the Appellant to furnish within 120 days a return of income. Notice issued u/s 148A(b) (APB-1) dated 27-02-2024 shows that trigger for issuance of Notice u/s 148 was “information being SFT-012(B)-Purchase by any person of immovable property-Rs.75,00,000” received through Insight Portal as per the Risk Management Strategy (RMS) formulated by the CBDT and the AO at the end of the Notice recorded stated transaction as qualifying the requirement as specified u/s 149(1)(a) of the Income Tax Act, 1961.
2.2.1 In the context of the issue in hand qua the additional ground no.12 & 14 raised above, it is relevant to invite the kind attention to the proviso to section 148A(conducting inquiry, providing opportunity before issue of notice u/s 148)- which read as under;
“Provided that the provisions of this section shall not apply in a case where,–
| (a) | a search is initiated…… |
| (b) | the Assessing Officer is satisfied,.that any money bullion…….seized.u/s 132. |
| (c) | the Assessing Officer is satisfied,…….that any books of accounts ….seized.. |
| (d) | the Assessing Officer has received any information under the scheme notified under section 135A pertaining to income chargeable to tax escaping assessment for any assessment year in the case of the assessee.” |
2.2.2 In short, in view of the proviso the process as provided under clause (a) to (d) of section 148A is not applicable and the Assessing Officer is under an obligation to proceed with the issuance of notice u/s 148 straight away. It is an undisputed fact, as shown above, that the information which formed the ground for issuance of notice u/s 148A or 148 was received by the AO in pursuance of the scheme notified u/s 135A of the Income Tax Act, 1961 and when it was so clearly action on the part of the AO to move proposal seeking Pr. CIT’s approval for passing order u/s 148A(d) or action on the part of the Pr. CIT, Delhi-10 to accord the solicited approval was not in consonance with the mandate of the law as explained in the clause (d) of the Proviso referred above, they, accordingly are to be held as not in the consonance with the bare provisions of section 148A r.w.s. 148 of the Act and hence a nullity.
2.2.3 Above apart, it is also considered necessary to point out that even otherwise without prejudice to the argument of non-service of mandatory/jurisdictional notice allegedly issued u/s 148 of the Act, attention is invited to para 2 of the said Notice (APB-6) where AO is seen requiring the Appellant ‘to furnish, within 120 days from the issue of this notice, a return in the prescribed form’ whereas applicable Law as contained u/s 148 required this period to be ‘within a period 3 months from the end of the month in which such notice is issued’. Very clearly the Notice was not in conformity with the mandate of the law, thus, requiring the entire assessment proceedings to be bad in law.
2.2.4 In support of the argument for quashing the proceedings because of the non-service of Notice issued u/s 148 or on the ground of this Notice not being in conformity with the law, reliance is placed on the Supreme Court judgment in Association of Management of Private Colleges v. All India Council for Tech. Education (DoJ 28-04-2013) where in para 44 relying on earlier judgments in Babu Verghese v. Bar Council of Kerala; Privy Council decision in Taylor v. Taylor (followed by Lord Roche in Nazir Ahmad v. King Emperor) and Rao Shiv Bahadur Singh v. State of UP and Singhara Singh rule was laid down “It is the basic principle of law long settled that if the manner of doing a particular act is prescribed under any statute, the act must be done in that manner or not at all.”
3. Thus, allowing additional ground Nos. 12 & 14 raised, exercise undertaken by the AO culminating in the assessment be held as bad in law.
7. On the other hand, ld. DR of the Revenue submitted that the notices were duly issued and served in the manner prescribed under the provisions of the Act. In particular, the notice issued under section 148 of the Act was duly served by way of affixture in accordance with the prescribed procedure, and the affixture report forms part of the assessment records and is placed on record. He submitted that the assessee also participated in the assessment proceedings and filed submissions without raising any objection regarding the service of notices. He further submitted that accordingly, by virtue of the provisions of section 292BB of the Act, the assessee is precluded from challenging the validity of service of notice at this stage. Therefore, the objection raised by the assessee is devoid of merit and liable to be rejected. He further relied on the findings of the lower authorities. Ld. DR brought to our notice the report of the Notice Server and Inspector Ward 50(1), New Delhi which is reproduced below :-
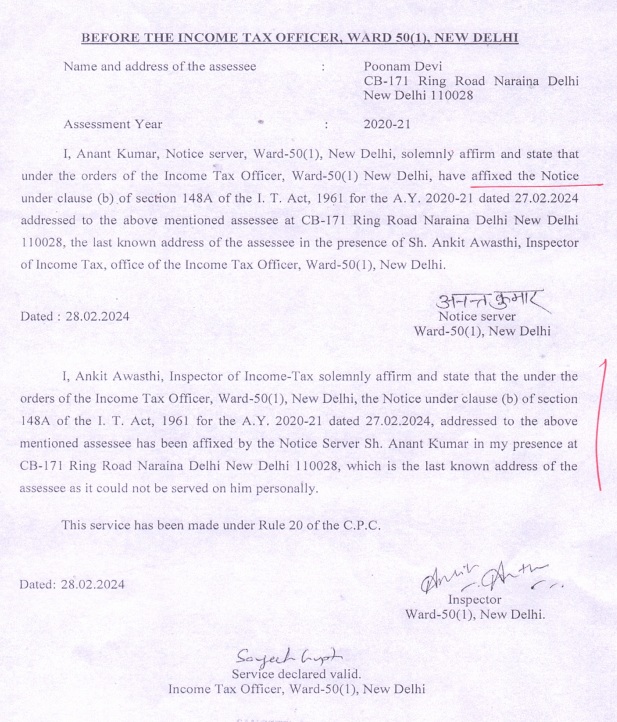
8. Considered the rival submissions and material placed on record. We observed that the case of the assessee was selected for reassessment on the basis of information received from the registrar of stamp duty that the assessee had registered a property residing at CB-278, 2nd floor, Ring Road, Naraina, New Delhi -28 but the AO tried to send the notice u/s 148 in the address CB-171, Ring Road, Naraina, New Delhi -028. Since, the notices were not served on the assessee, the above said notice was served by affixture. In this regard, Ld DR submitted the copy of the notice affixture, which was reproduced in the above paragraphs as part of DR submissions. After careful consideration, we observed that no doubt the AO proceeded to affix the notice in the address, which the assessee was residing nor the AO had brought on record the relevance of the above address, which belongs to the assessee. Why the notice was not served to the assessee as per the address found in the registered sale deed.
9. We observed that no doubt the notice was served by affixture in the wrong address still due procedure for affixture as per rule 17 to 20 for substituted service of notice were not followed. The Ld DR had submitted the copy of service of notice by affixture file but it does not contain the details of due diligence and witness verification from the locals or neighbors, who had witnessed the actual affixture took place at the correct property. In this case, it is not clear from the above letter submitted by the Ld DR, which is the proper or correct address or property. Therefore, it is clear that the due procedure for service of notice by affixture was not followed, the same cannot be treated as validly served on the assessee. Therefore, we are inclined to hold that the notice u/s 148 was not validly served on the assessee to initiate the proceedings u/s 147 of the Act. The submissions of the Ld DR on section 292BB are not accepted. Hence, additional ground no 13 raised by the assessee is allowed.
10. The other substantial grounds and other additional grounds are not adjudicated at this stage, they are kept open at this stage.
11. In the result, the appeal filed by the assessee is allowed.