


Demand Remanded as GSTR Mismatch Does Not Automatically Prove Short Payment Without Detailed Reconciliation
Issue
-
Validity of Ex-Parte Demand on GSTR Mismatch: Whether a numerical discrepancy between GSTR-1 and GSTR-3B automatically proves short payment of tax to justify an ex-parte composite demand under Section 73 without detailed verification and reconciliation.
-
Shifting of Grounds in Appeal: Whether an appellate authority can uphold a tax demand on grounds different from those specified in the original show cause notice or assessment order.
-
Statutory Waiver & Recomputation (Section 128A): Whether interest, penalty, and tax demands can be sustained without verifying claims for statutory waiver under Section 128A, checking for duplicate proceedings, and determining the exact unpaid tax liability.
Facts
-
Period & Notice: For FY 2019–20, the appellant (a registered dealer) was issued a notice regarding numerical differences between outward liability reported in GSTR-1 and tax paid in GSTR-3B.
-
Ex-Parte Assessment: Due to non-appearance/lack of response, the adjudicating authority passed an ex-parte order creating a composite demand comprising tax, interest, and penalty under Section 73.
-
Partial Payment: A small self-assessed tax payment was made by the appellant via Form GST DRC-03.
-
First Appeal Dismissal: The first appellate authority dismissed the appeal ex-parte without evaluating:
-
Rectification claims, return reconciliations, and payment challans submitted by the dealer.
-
Overlapping issues regarding ITC differences (GSTR-2A vs GSTR-3B) and Rule 42/43 proportionate credit reversals.
-
Claims for statutory waiver of interest and penalty under Section 128A.
-
Allegations of duplicate notices/demands issued for the same tax period.
-
Decision
-
GSTR-1 vs GSTR-3B Mismatch: Matter Remanded. Numerical mismatches serve merely as a starting point for inquiry and do not ipso facto establish tax short-payment, as variations can arise from timing shifts, credit notes, amendments, or reporting errors.
-
Improper Shifting of Legal/Factual Basis: Matter Remanded. Tax demands cannot be confirmed on one factual basis in the original order (outward liability mismatch) and sustained on a completely different basis at the appellate stage (ITC reversals).
-
Statutory Waiver & Recomputation: Matter Remanded.
-
The authority erred in failing to decide the appellant’s eligibility for statutory waiver under Section 128A.
-
Interest under Section 50 and penalties under Section 73 cannot be confirmed without first determining the precise tax liability, delay period, and statutory waiver eligibility.
-
-
Verification of Duplicate Demands: Matter Remanded. The appellate authority must examine all notices/orders for the relevant period to eliminate duplicate tax demands.
Key Takeaways
-
GSTR Mismatch Is Not Conclusive Tax Evasion: A difference between GSTR-1 and GSTR-3B returns requires factual verification against liability registers, annual returns, and challans before confirming short-payment.
-
Strict Segregation of Notice Grounds: Departmental authorities cannot change the fundamental grounds of a demand during appellate proceedings without issuing proper notices.
-
Mandatory Evaluation of Statutory Waiver: Appellate authorities must explicitly examine and record findings on a taxpayer’s claim for interest and penalty waiver under Section 128A before upholding penal demands for eligible non-fraud periods (FY 2017–18 to 2019–20).
GOODS AND SERVICE TAX APPELLATE TRIBUNAL , LUCKNOW BENCH
Om Traders
v.
Commissioner State Goods and Services Tax
Santosh Kumar Srivastava, Judicial Member
and Arvind Kumar, Technical Member
and Arvind Kumar, Technical Member
APL/74/LCK/2026
SEPTEMBER 29, 2026
Dr. Swayambhav Manu, Adv. for the Appellant. Ashutosh Mishra, Asstt. Commissioner for the Respondent.
ORDER
Brief Facts of the Case.
1.1 The present appeal has been filed against Order-in-Appeal No. ZD090625035510J dated 20.08.2025 passed by the Additional Commissioner, Grade-II (Appeal)-5, State Tax, Kanpur, whereby tax amounting to Rs. 1,92,902.00, penalty of Rs. 40,000.00 and interest of Rs. 1,73,426.00, aggregating to a demand of Rs. 4,06,328.00 determined by the proper officer Section 73 of the State Goods and Services Tax Act, 2017 was upheld.
1.2 M/s OM Traders (hereinafter referred to as the “appellant”) having it principal place of business at A-4, Rampur Garden, Bareilly. The appellant is a registered dealer with GST registration number GSTIN 09AHSPG5583H1ZR.
1.3 During verification of returns furnished by the appellant for the relevant period, a discrepancy was noticed by the proper officer between the tax liability declared in GSTR-3B and GSTR-1. Subsequently, a notice was issued to the appellant by the Proper Officer under the provisions of Section 73 of the GST Act. However, the appellant did not furnish any written reply to the said notice. Consequently, the Proper Officer proceeded to adjudicate the matter ex-parte and passed the order dated 22.08.2024, determining tax of Rs. 1,92,902/-, penalty of Rs. 40,000/- and interest of Rs. 1,73,426/-, amounting to Rs. 4,06,328/-.
1.4 Aggrieved by the aforesaid adjudication order, the appellant preferred an appeal before the First Appellate Authority.
1.5 During the appellate proceedings, notices for hearing were issued to the appellant fixing the dates of hearing. Despite repeated opportunities, neither the appellant nor any authorized representative appeared for the hearing. No application seeking adjournment was also submitted. Accordingly, the appeal was taken up for ex-parte disposal on the basis of the material available on record and the grounds of appeal filed by the appellant.
1.6 The appellant challenged the proper officer’s order on several grounds. It was contended that the notice and order were unsigned and, therefore, legally invalid. The appellant further alleged procedural irregularity in uploading FORM GST ASMT-10 and DRC-01 on the GST portal, stating that the documents were uploaded under the “View Additional Notices and Orders” section instead of the “View Notice and Order” section, which allegedly prevented the appellant from becoming aware of the proceedings in time and deprived it of an effective opportunity to respond.
1.7 The appellant also contended that multiple orders had been issued for the same tax period under different provisions, including Sections 73 and 74 of the GST Act, and that a consolidated order ought to have been passed. It was further submitted that the discrepancies between GSTR-3B and GSTR-1 were merely calculation errors and that the appellant had subsequently rectified such discrepancies and deposited the corresponding tax along with applicable interest.
1.8 The appellant also relied upon the provisions of Section 128A of the CGST Act, contending that the provision provides for conditional waiver of interest and penalty in respect of eligible demands arising under Section 73 for the specified financial years. On this basis, the appellant claimed waiver of the interest and penalty imposed in the present case.
1.9 It was further pleaded that the penalty and interest were disproportionate to the nature of the discrepancies and that the discrepancies had been corrected promptly. The appellant also alleged violation of the principles of natural justice and contended that its objections, replies and documents had not been duly considered. It was also submitted that the impugned order was not a proper speaking order as it did not sufficiently record the reasons and considerations leading to determination of the tax, interest and penalty.
1.10 Consequently, the First Appellate Authority passed an order dated 20.08.2025 by rejecting appellant’s appeal on ex-parte basis and upheld the order passed by the Proper Officer under Section 73 of the GST Act.
2. Grounds of appeal
2.1 The appellant has challenged the Order-in-Appeal dated 20.08.2025, contending that the appeal was dismissed primarily on procedural grounds, namely non-appearance and non-submission of supporting evidence, without examination of the substantive merits of the ITC claim.
2.2 The appellant contended that, under Section 107(8) of the CGST Act, 2017, an effective opportunity of hearing was required to be afforded before disposal of the appeal. It is alleged that the appellate authority failed to properly consider the appellant’s circumstances and contentions.
2.3 The appellant contended that the impugned appellate order does not properly identify the points for determination, examine the ITC claim, or record adequate reasons for rejecting the appeal. The appellant therefore alleges violation of Section 107(12), which requires a reasoned and speaking appellate order.
2.4 The appellant has relied upon decisions including Mukesh Kumar Singh, Sanjeet Kumar Bhagat, ITI Ltd. and R.A. Metal Finishers, to contend that tax authorities should not reject proceedings merely on procedural or technical grounds where substantive issues remain to be examined and relevant documents require consideration.
2.5 The appellant contended that the First Appellate Authority did not examine whether the ITC was actually eligible, whether the underlying purchases were genuine, whether the conditions of Section 16(2) were fulfilled, or whether the alleged mismatch was attributable to supplier-side reporting errors, delayed filing of GSTR-1 or technical issues.
2.6 The appellant contended that the Order-in-Original dated 22.08.2024 allegedly disallowed ITC of Rs. 1,92,902/- on account of mismatch between GSTR-3B and GSTR-2A and alleged non-reversal under Rules 42 and 43. The appellant submits that its reply was rejected without adequate examination of the supporting documents and legal submissions.
2.7 The appellant asserts that ITC eligibility is required to be examined with reference to the statutory conditions under Section 16(2), including possession of tax invoices, receipt of goods/services, payment of tax to the Government and filing of the prescribed return. It is contended that a GSTR-3B/GSTR-2A mismatch alone does not conclusively establish wrongful availment of ITC.
2.8 The appellant states that the mismatch could have arisen because of non-filing or delayed filing of GSTR-1 by suppliers, reporting in a different tax period, incorrect B2C reporting, wrong GSTIN or technical errors on the GST portal. The appellant alleges that the authorities did not determine the specific reason for the mismatch in the present case.
2.9 The appellant disputes the alleged non-reversal of ITC under Rules 42 and 43 and relies upon the proposition that these provisions concern common inputs/input services requiring proportionate attribution. The appellant also refers to the decision in Solid & Correct Engineering Works in support of its contention.
2.10 The appellant states that it possesses original purchase invoices, bills, payment proofs, ledger extracts and other documents establishing the genuineness of the transactions and seeks an opportunity to produce the same along with reconciliation statements and, where applicable, CA/CMA or supplier certificates.
2.11 The appellant relies upon Hemraj Rice Mill, Masany Construction Equipment and Raiganj Jeevan Rekha Diagnostic to contend that factual disputes concerning ITC mismatch and reversal should be verified through relevant records and reconciliation rather than being disposed of summarily.
2.12 The appellant therefore seeks an opportunity to produce supporting documents and reconciliation statements and requests fresh adjudication through a reasoned and speaking order and matter be remanded to the Proper Officer/Adjudicating Authority for fresh consideration, with clear directions.
3. Submission of Respondent
3.1 During the verification of return filed by the appellant following discrepancy were observed:-
| i. | a difference of Rs. 13,138.02 between the Input Tax Credit (ITC) claimed by the taxpayer in the monthly return GSTR-3B and the ITC reflected in GSTR-2A/2B. |
| ii. | the taxpayer had not reversed the ITC in accordance with Rules 42 and 43. |
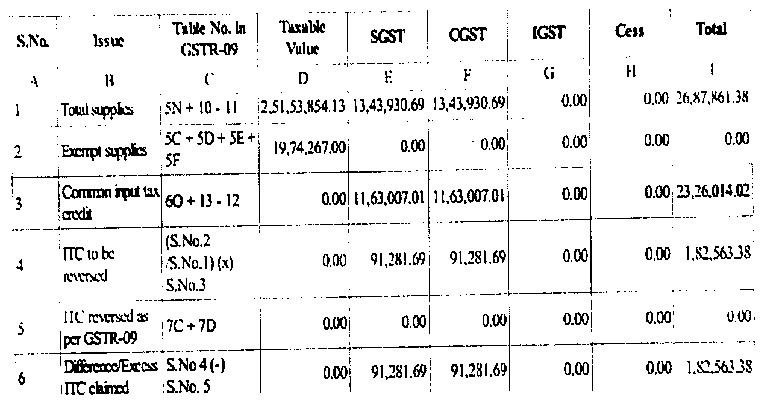
3.2 The appellant was required to furnish an explanation along with supporting evidence, failing which proceedings for demand/reversal of the said amount were proposed to be initiated.
3.3 It was observed that the appellant had not reversed the ITC in accordance with Rules 42 and 43. Accordingly, the appellant was required to furnish an explanation as to why proceedings for reversal of the said ITC should not be initiated.
3.4 In compliance with the aforesaid notice, the appellant did not initially file any online reply/explanation. Thereafter, FORM GST DRC-01 dated 24.06.2024 was issued to the taxpayer in respect of the aforesaid points. As the appellant did not file any reply thereto, a reminder notice dated 20.08.2024 was issued, in response to which the appellant filed an online reply on the portal.
3.5 On examination of the reply filed by the appellant, it was found that, in respect of Point No. (i), the appellant had deposited tax amounting to Rs. 2,798.00 vide DRC-03 ARN No. AD090624050989E dated 24.06.2024, comprising CGST Rs. 1,399.00 and SGST Rs. 1,399.00, through the electronic credit ledger. However, the remaining tax amount had not been deposited.
3.6 On verification of the electronic credit ledger, it was found that the appellant’s ITC chain had been broken during the relevant year. Therefore, the appellant was required to deposit the applicable interest and penalty. However, the appellant did not deposit the interest and penalty. Accordingly, after allowing the benefit of the tax amount of Rs. 2,798.00 already deposited by the taxpayer, the remaining tax, along with applicable interest and penalty, was created as demand in the order.
3.7 In respect of Point No.(ii) of the notice, the appellant did not furnish any documentary evidence. Since the appellant failed to substantiate the said point through the relevant records and documentary evidence, the tax liability involved under the said point was determined and demand was created.
3.8 Accordingly, vide FORM GST DRC-07 dated 22.08.2024, a total demand of Rs. 4,06,328.00 was created, comprising tax of Rs. 1,92,902.00, interest of Rs. 1,73,426.00 and penalty of Rs. 40,000.00.
3.9 Therefore, the appellant failed to comply with the statutory provisions under Sections 16 and of the CGST Act, 2017 read with Rules 42 and 43 of the CGST Rules, 2017, and similarly, failed to comply with the statutory provisions 50 of the CGST Act, 2017. The taxpayer failed to discharge the statutory burden of establishing the admissibility of the disputed ITC under Section 155 of the CGST Act, 2017.
4. Findings and Discussion
4.1 We have carefully examined the impugned Order-in-Appeal dated 20.08.2025, the grounds raised in the present appeal, the order dated 22.08.2024 passed by the Proper Officer, and the judicial precedents relied upon by the appellant and the material available on record.
4.2 Upon examination of the appeal memorandum, the grounds raised by the appellant and the order passed by the First Appellate Authority, We find that the central issue involved in the proceedings was the difference in tax liability between GSTR-3B and GSTR-1 for the relevant period.
4.3 We find that the appellant lost opportunity to place any documentary evidence before appellate authority substantiate its contention regarding the said difference and to produce any supporting evidence or documentary proof explaining or reconciling the discrepancy between the tax liabilities reported in GSTR-3B and GSTR-1.
4.4 A difference between GSTR-1 and GSTR-3B cannot, in every circumstance, be equated with actual short-payment of tax. GSTR-1 contains details of outward supplies reported by the registered person, whereas GSTR-3B contains the summary of outward supplies and tax liability declared and discharged by the taxpayer. A difference between the two returns may arise on account of various reasons, including inadvertent reporting or calculation errors, reporting of a transaction in a different tax period, amendment of invoices, duplication, credit notes or other accounting/reporting discrepancies.
4.5 We rely upon the decision of Hon’ble Gauhati High Court in the case of M/s ITI Ltd. v. Union of India & Ors, wherein court held that where the taxpayer claims that the mismatch resulted from a bona fide mistake, the taxpayer should be given an opportunity to explain the mismatch with supporting material before liability is finally determined.
4.6 The said principle is relevant to the present matter. The existence of a numerical difference between two returns is the starting point of an inquiry; it is not, by itself, the conclusion regarding actual tax liability. The authority is required to determine the nature and reason of the difference and whether it represents tax which has actually remained unpaid.
4.7 Therefore, before confirming tax of Rs. 1,92,902/-, it was necessary to ascertain whether the alleged difference represented an actual short-payment or merely a reporting/calculation discrepancy.
4.8 The appellant has specifically pleaded that the discrepancy between GSTR-1 and GSTR-3B was attributable to a calculation/reporting error and that the same was subsequently rectified. It has further been pleaded that the corresponding tax and applicable interest were deposited.
4.9 This explanation cannot be accepted merely on the basis of assertion. At the same time, it also cannot be rejected without verification where the alleged discrepancy is capable of being objectively reconciled from the GST returns, electronic liability records, challans, annual return and other relevant documents.
4.10 We rely upon the decision of Hon’ble Gujarat High Court in the case of Shreeji Developers v. State of Gujarat considered a case involving differences between GSTR-1 and GSTR-3B, wherein court held that the mere numerical difference between GSTR-1 and GSTR-3B does not, by itself, establish actual short-payment; the authority must examine the taxpayer’s explanation and reconciliation.
4.11 Similarly, the decision of Hon’ble Kerala High Court in Masany Construction Equipment (P.) Ltd. v. State Tax Officer [2025] 172 109 GST 296/97 GSTL 120 (Kerala)/WP (C) No. 33646 of 2024, dated 11.03.2025 is distinguishable on facts, as in the said case the specific explanation furnished by the petitioner regarding the data-entry error was discarded merely by stating that it was ‘not convincing and non-explanatory’, whereas in the present case the liability is required to be examined on the basis of the discrepancies noticed in the returns, the partial payment made by the appellant, and the absence of complete documentary reconciliation or supporting evidence.”.
4.12 The ratio emerging from these decisions is that a return mismatch has to be examined factually and on the basis of reconciliation, and cannot be converted into a tax demand merely by adopting the differential figure without determining the reason for the difference.
4.13 The appellant has pleaded that the discrepancy was subsequently corrected and that the differential tax along with applicable interest was deposited. This contention has direct bearing upon the sustainability of the demand. If the disputed amount has already been discharged, the authority is required to ascertain the exact amount, date and manner of payment and determine whether any tax remained outstanding thereafter.
Accordingly, the following aspects require verification:
| (i) | the amount of outward tax liability declared in GSTR-1; |
| (ii) | the tax liability declared and discharged through GSTR-3B; |
| (iii) | the actual amount of tax, if any, subsequently deposited by the appellant; |
| (iv) | the date and manner of such payment; |
| (v) | the interest, if any, actually payable and discharged; and |
| (vi) | whether any balance tax liability remained outstanding after taking into account the subsequent payment/rectification. |
4.14 Without such exercise, confirmation of the entire differential amount merely on the basis of comparison of two return figures would not constitute a complete determination of the actual tax liability.
4.15 The appellant has also challenged the impugned appellate order on the ground that the material grounds raised in the appeal were not properly examined. In this regard, the judgment of the Hon’ble Jharkhand High Court in Mukesh Kumar Singh v. Commissioner is relevant. The Court emphasised the statutory requirement under Section 107(12) that an appellate order should identify the points for determination, record the decision thereon and provide reasons for such decision.
4.16 In the present case, we find that the first appellate authority did provide several opportunities of hearing to the appellant on 07.03.2025, 07.04.2025, 22.04.2025, 25.07.2025, 30.07.2025 and 19.08.2025. Therefore, the appellant cannot legitimately contend that no opportunity of hearing whatsoever was granted. However, grant of opportunity of hearing and proper adjudication of the issues arising from the appeal are two distinct requirements. The appellant’s failure to avail the opportunities may justify proceeding ex-parte, but it does not dispense with the statutory obligation to pass a reasoned order dealing with the material grounds which arise for determination.
4.17 Thus, the question is not merely whether the appellant appeared before the first appellate authority, but whether the appellate order adequately determined the legality and correctness of the demand arising from the alleged mismatch.
4.18 The appellant had raised specific grounds concerning the alleged reporting/calculation error, subsequent rectification and payment, procedural irregularities concerning ASMT-10 and DRC-01, multiple proceedings, interest and penalty, and applicability of Section 128A.
4.19 The impugned appellate order, however, principally proceeds on the basis that the appellant did not appear and did not furnish documentary evidence reconciling the difference between GSTR-1 and GSTR-3B.
4.20 In our considered view, such reasoning is not sufficient to finally determine all the material issues arising in the appeal. Particularly, where the appellant has pleaded that the differential tax was subsequently paid and the discrepancy was corrected, the authority is required to verify whether any tax actually remained unpaid. The absence of the appellant at the appellate hearing may affect the evidentiary weight of its unsubstantiated assertions, but it cannot convert an unverified return mismatch into an automatically established tax liability.
4.21 The appellant has also invoked Section 128A of the CGST Act, 2017, claiming waiver of interest and penalty in respect of the Section 73 demand pertaining to FY 2019-20. The statutory scheme under Section 128A specifically covers eligible demands under Section 73 pertaining to FY 2017-18, FY 2018-19 and FY 2019-20, subject to fulfilment of the conditions prescribed therein and under Rule 164. Since the present demand pertains to FY 2019-20 and has been stated to arise under Section 73, the appellant’s claim under Section 128A is a material statutory issue requiring examination.
4.22 It is clarified that the mere fact that the demand pertains to FY 2019-20 does not automatically confer the benefit of Section 128A. The conditions prescribed under the statutory scheme must be fulfilled. Nevertheless, the claim is required to be considered and decided by the first appellate authority.
4.23 The first appellate authority has not recorded a specific finding determining whether the appellant satisfies the statutory requirements of Section 128A. The omission assumes significance because the provision came into force before the passing of the impugned appellate order.
4.24 Accordingly, the appellant’s claim under Section 128A requires fresh examination in accordance with the law applicable to the relevant period and the conditions prescribed under the Act and Rules.
4.25 The impugned demand includes interest of Rs. 1,73,426/-. Since interest is consequential upon the tax liability and the period for which the tax remained unpaid, the amount of interest also requires verification.
4.26 If, upon reconciliation, it is found that the tax was already discharged or was discharged subsequently, the appellate authority must determine the precise period and amount on which interest is legally payable. Further, if the appellant is found eligible for the benefit of Section 128A, the claim for waiver of interest has also to be considered in accordance with the statutory conditions. Therefore, we find that the interest demand cannot be finally sustained without first determining the actual outstanding tax liability and the period of delay, if any.
4.27 We find that the Proper Officer imposed penalty of Rs. 40,000/-. The sustainability of penalty requires separate examination from the mere existence of a return mismatch. The authority is required to determine whether there was an actual short-payment, whether the same was subsequently discharged, the circumstances in which the discrepancy occurred, and whether the statutory conditions for imposition of penalty were satisfied.
4.28 Further, in view of the specific claim under Section 128A, the eligibility of the appellant for waiver of penalty also requires examination. Thus, the penalty cannot be conclusively sustained without determining the factual and statutory issues referred to above.
4.29 The appellant has also alleged that FORM GST ASMT-10 and DRC-01 were uploaded in the “View Additional Notices and Orders” section rather than the “View Notice and Order” section and that this resulted in the appellant not becoming aware of the proceedings in time. This contention also requires factual verification from the GST portal record. However, the mere allegation of improper uploading would not by itself invalidate the demand unless the appellant establishes that the manner of communication resulted in denial of the statutory opportunity or caused actual prejudice.
4.30 The appropriate authority should therefore verify the mode and date of service/communication of the relevant notice and determine whether the statutory requirements relating to service of notice were complied with.
4.31 The appellant has further alleged that multiple orders were issued for the same tax period under Sections 73 and 74 and that a consolidated order ought to have been passed. This contention cannot be accepted or rejected merely on the basis of assertion. The relevant notices and orders are required to be examined to determine:
| • | whether they relate to the same tax period; |
| • | whether they concern the same tax liability; |
| • | whether the provisions of Section 73 or Section 74 were invoked; |
| • | whether there is duplication of demand; and |
| • | whether any prejudice has been caused to the appellant. |
4.32 If the same liability has been subjected to multiple proceedings or duplicated demand, the same would necessarily require appropriate correction.
4.33 We find that the original demand, as recorded in the proceedings, principally relates to the difference between GSTR-1 and GSTR-3B, whereas certain grounds raised in appeal refer to GSTR-2A/GSTR-3B mismatch and Rules 42 and 43. These are distinct factual and legal issues.
4.34 Therefore, before finally determining the liability, the authority must clearly identify the precise basis on which Rs. 1,92,902/- was determined. If the demand is based upon outward tax liability reflected in GSTR-1 vis-à-vis GSTR-3B, the reconciliation must be undertaken accordingly. If any part of the demand relates to ITC reversal or Rules 42 and 43, the statutory basis and computation thereof must separately be established.
4.35 We find that a demand cannot be sustained on one factual basis in the original order and justified on an altogether different basis at the appellate stage without proper determination. On a cumulative consideration of the facts and the judicial principles discussed above, we find that the impugned Order-in-Appeal dated 20.08.2025 cannot be sustained.
Accordingly, in the interest of a proper and legally sustainable determination, the matter deserves to be remanded for fresh consideration rather than the demand being confirmed merely on the basis of the un-reconciled difference and the appellant’s non-appearance.
Order
| i. | In view of the foregoing discussion and findings, Order-in-Appeal No. ZD0906250355I0J dated 20.08.2025 passed by the Additional Commissioner, Grade-II (Appeal)-5, State Tax, Kanpur is hereby set aside and the matter is remanded back to the First Appellate Authority for fresh Order in accordance with the law. |