


Reassessment quashed as Assessing Officer failed to pass mandatory separate speaking order disposing objections.
Issue
Whether a reassessment order passed under Section 147 read with Section 144B is legally valid when the Assessing Officer fails to pass a separate speaking order disposing of the assessee’s objections before proceeding with the reassessment.
Facts
-
Background & Reopening: For AY 2015-16, the assessee (a trader in electronic goods) filed its return declaring income. Based on Investigation Wing information regarding alleged accommodation entries via a co-operative urban credit society, the Assessing Officer (AO) issued a notice under Section 148.
-
Objections Filed: The assessee filed formal objections against the reopening, explicitly stating that it had no transactions with the mentioned credit society.
-
Procedure Followed by AO: Without issuing a separate speaking order to dispose of the filed objections, the AO proceeded with statutory notices under Sections 143(2)/142(1), issued a show-cause notice, and finalized the reassessment under Section 147 read with Section 144B, adding the alleged transactions as bogus cash credits under Section 68.
-
Non-Compliance: The assessee’s objections remained on record, but no separate speaking order disposing of them was passed or produced by the Revenue.
Decision
-
In Favor of Assessee: The law requires the AO to pass a separate speaking order disposing of objections prior to proceeding with reassessment.
-
In Favor of Assessee: Mere reference to or informal consideration of objections during subsequent assessment proceedings does not satisfy mandatory procedural requirements.
-
In Favor of Assessee: Since the mandatory procedure was violated, the reassessment order passed under Section 147 read with Section 144B was quashed.
Key Takeaways
-
Mandatory Speaking Order: Upon receiving objections to a Section 148 reopening notice, the AO is legally bound to dispose of them via a separate speaking order before taking further reassessment steps.
-
Procedural Compliance is Absolute: Discussing objections casually in the final assessment order or subsequent show-cause notices cannot cure the failure to issue a dedicated disposal order.
-
Fatal Defect Leads to Quashing: Non-compliance with the established procedure for disposing of objections renders the entire reassessment proceedings invalid and liable to be quashed.
IN THE ITAT MUMBAI BENCH ‘A’
Libra Natural Resources (P.) Ltd.
v.
Income-tax Officer
ANIKESH BANERJEE, Judicial Member
and Om Prakash Kant, Accountant Member
and Om Prakash Kant, Accountant Member
IT Appeal No. 6695 (MUM) of 2025
[Assessment Year 2015-16]
[Assessment Year 2015-16]
SEPTEMBER 18, 2026
Ajay Singh and Akshay Pawar, Advs. for the Appellant. Manoj Kumar, CIT DR for the Respondent.
ORDER
Anikesh Banerjee, Judicial Member.- The instant appeal of the assessee filed against the order of NFAC, Delhi [for brevity “Ld. CIT(A)”], order passed under Section 250 of the Income Tax Act, 1961 (for brevity ‘the Act’), for Assessment Year 2015-16, date of order 25.08.2025. The impugned order emanated from the order of the National Faceless Assessment Center, Delhi (for brevity ‘Ld. AO’), order passed under Section 147 r.w.s. 144B of the Act, date of order 30.03.2022.
2. The assessee filed the original return by declaring total income Rs. 29,29,433/-. The case was reopened u/s. 147 and accordingly a notice was issued u/s. 148 of the Act on 31.03.2021 based on the information received from the Investigation Wing of the Department that the assessee had taken accommodation entry made by way of unexplained transaction amount to Rs. 3,20,97,440/- with Mr. Ashish Panchal, proprietor of M/s Nine Impex, and Rs. 8,33,00,000/- with M/s. Zara Trading Private Limited through Shri Renukamata Multi State Cooperative Urban Credit Society Limited, which comes total amount to Rs. 11,53,97,440/- during the impugned assessment year. As the total transaction of Rs. 11,53,97,440/- was not reflected in the ITR, the Ld. AO had initiated proceedings u/s. 147 of the Act. In response to the notice u/s 148, the assessee filed the return on 28.07.2021. The assessee engaged in business of importing electronic goods like batteries, torch, etc. and selling on local market on wholesale trading basis. In response to the notice, the assessee filed the written submission and informed that the assessee had no transaction with the Renukamata Multi State Cooperative Urban Credit Society Limited. But finally, the Ld. AO treated the entire transaction as a bogus transactions and the addition was confirmed total amount to Rs. 11,53,97,440/- with the total income of the assessee. The aggrieved assessee filed an appeal before the Ld. CIT(A), but the Ld. CIT(A) had rejected the appeal of the assessee. Being aggrieved, the assessee filed an appeal before us.
3. The Ld. AR challenged the jurisdiction of Ld. AO related issuance of notice u/s. 148 and completion of assessment u/s. 147 without disposing the objection filed by the assessee during the proceedings through the Additional Ground. The Additional Ground taken by the assessee is duly reproduced as below:
“I. Reopening is bad in law:
1. The reopening of the assessment vide notice u/s 148 of the Act dated 31/03/2021 is bad in law as the same is based on borrowed satisfaction the impugned notice is issued merely on information received that the Assessee has undertaken an unexplained transaction with M/s Renukamata Multi State Cooperative Urban Credit Society Ltd during the year, without appreciating the fact that there was no such transaction undertaken by the assessee with the said credit society and therefore the reopening is bad in law.
2. The learned CIT (A) failed to appreciate that the details of the alleged transactions with M/s Renukamata Multi State Co-operative Urban Credit Society Limited had not been provided to the assessee and therefore the assessment has been completed based on assumptions and presumptive basis.
3. The Ld. CIT(A) failed to appreciate that notices were issued u/s. 142(1) of the Act and reassessment order was passed without disposing off the objections raised by the assessee, therefore the same was in violation of the procedure as laid down by the Hon’ble Supreme Court in the case of GKN Drive Shaft reported in 259 ITR 19 and hence the entire proceedings are void-ab-initio.
The assessee craves leave to add, alter modify or delete one or more ground before or at the time of hearing of Appeal.”
4. The Ld. AR filed paper books comprising pages 1 to 587, which have been placed on record. The Ld. AR submitted a detail of the reassessment proceedings initiated by Ld. AO. Ld. AR submitted the list of dates & events which are as follows:-
| Sl. No. | Particulars | Date | APB Page |
| 1. | Reasons recorded | 31.03.2021 | 45 |
| 2. | Notice u/s. 148 | 08.07.2021 | 36 |
| 3. | Return of RY filed u/s. 148 | 28.07.2021 | 35 |
| 4. | Notice u/s. 143(2) issued | 07.12.2021 | 39-40 |
| 5. | Notice u/s. 142(1) | 09.12.2021 and 22.12.2021 | 49-50 |
| 6 | Objection filed by the assessee | 28.12.2021 | 51-54 |
| 7 | Notice u/s 142(1) | 24.01.2022 | 55-56 |
| 8 | Showcause Notice | 21.03.2022 | 90-98 |
5. The Ld. AR invited our attention in recorded reasons duly noted by the Ld. AO. The said recorded reason was supplied to the assessee, which is enclosed in APB page 45 to 46. The relevant part of the observations of the ld. AO is reproduced as below:
“A search operation was carried out at the offices (head and branch) of M/s. Renukamata including head office at Ahmednagar and branch offices at Mumbai, Ahmedabad, Chennai, Hyderabad, Ulhasnagar by the Investigation Wing, Mumbai on 26.05.2017. During the field enquiries at the premises of account holders in Mumbai, it was found that most of such account holders are persons of low means and their financial profiling do not correspond to the high volume of cash deposits in their accounts with the society.
It is further noticed that the assessee has involved in the transactions made with credit society during the F.Y.2014-15 as unexplained credit of Rs.3,20,97,440/- and other transactions totaling to Rs.8,33,00,000/-, In total the assessee has unexplained transactions of Rs. 11,53,97,440/- during the F.Y.2014-15, which was not reflected in its return of income for A.Y.2015-16.
In this case a return of income was filed for the year under consideration but no scrutiny assessment u/s. 143(3) of the Act was made. Accordingly, in this case, the only requirement to initiate proceeding u/s. 147 is reason to believe which has been recorded above.
It is pertinent to mention here that in this case the assessee has filed return of income for the year under consideration but no assessment as stipulated u/s. 2(40) of the Act was made and the return of income was only processed u/s. 143(1) of the Act. In view of the above, the provisions of clause (b) of Explanation 2 to section 147 are applicable to facts of this caseand the assessment year under consideration is deemed to be a case where income chargeable to tax has escaped assessment.
Thus, on the basis of material available on record, I have reason to believe that there is failure on the part of the Assessee to disclose fully and truly all the material facts necessary for its assessment for the year under consideration. Therefore, I have reason to believe that the income chargeable to tax amounting Rs. 11,53,97,440/-has escaped assessment coming within the meaning of section 147 of the Income Tax Act, 1961.”
6. The Ld. AR contended that, upon receipt of the reasons recorded for reopening the assessment, the assessee duly filed objections thereto. However, without disposing of the said objections, the Ld. AO proceeded to frame the impugned reassessment order. Accordingly, the Ld. AR submitted that the reassessment order passed under section 147 of the Act is bad in law.
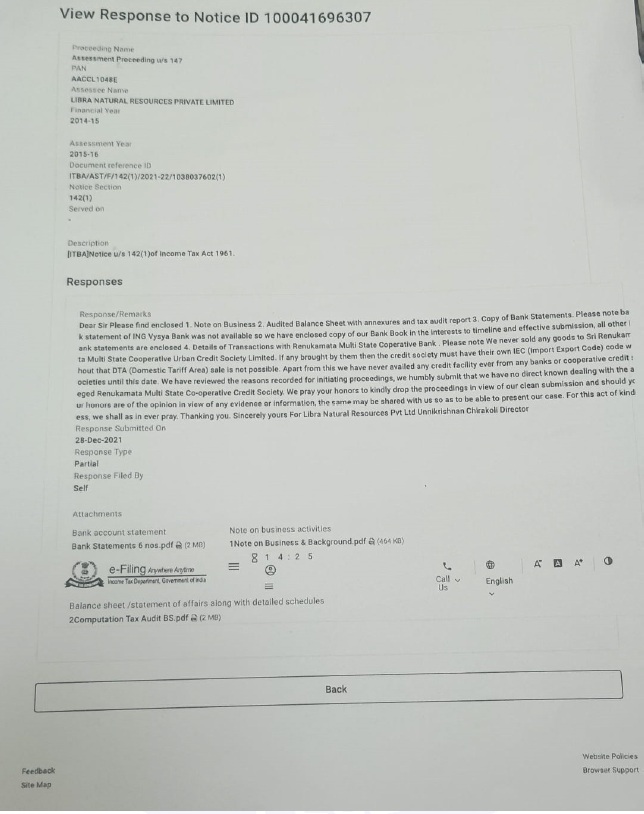
The Ld. AR further placed on record the response sheet evidencing the assessee’s compliance with the notice issued under section 142(1) of the Act. The said response sheet dated 28.12.2021 contains the objections raised by the assessee, inter alia, stating that the assessee had not entered into any transaction with the concerned co-operative society. The relevant submission is reproduced as under:
7. The Ld. DR argued and relied on the order of revenue authorities. The Ld. DR filed a written submission comprising pages 1 to 52 on dated 03.09.2026, which has been placed on record. The relevant part of the DR’s submission is reproduced as below:
“AO’s Comments on Additional Grounds
Ground No. 1: Reopening under Section 148 is bad in law
The contention of the assessee is not acceptable. The notice under section 148 dated 31.03.2021 was issued after recording reasons to believe based on credible information received through the Insight/verification mechanism regarding financial transactions linked to the assessee. The Assessing Officer applied independent mind to the information before recording reasons and obtaining the requisite statutory approval under section 151. The validity of reopening has already been upheld during the assessment proceedings. The reassessment proceedings were initiated in accordance with the provisions of the Income-tax Act, and therefore the reopening is valid in law.
Ground No. 2: Details of alleged transactions were not provided
The assessee’s contention is denied. During the reassessment proceedings, notices under sections 148 and 142(1) were duly issued, providing sufficient opportunity to the assessee to explain the transactions. The assessee was informed of the basis of reopening and was given adequate opportunity to furnish evidence. The assessment was completed after considering the material available on record and the submissions made by the assessee. Hence, the assessment cannot be said to have been completed merely on assumptions or presumptions.
Ground No. 3: Objections were not disposed of before passing the reassessment order
As per ITBA System, it is seen that notice u/s.142(1) of the Act on dated 08.07.2021 & 22.12.2021 and 24.01.2022 were issued to the assessee with the specific questioner has been issued to the assessee. It is pertinent to mention that there are no any specific objection has been raised except general objection i.e. request for personal hearing and sufficient time to provide the Submission.
It is submitted that adequate opportunities were provided to the assessee during the reassessment proceedings. The objections raised by the assessee were duly considered during the course of assessment. The reassessment order was passed only after considering the facts, material available on record, and the assessee’s submissions. Therefore, there is no violation of the prescribed procedure, and the reassessment order is legally sustainable.
In view of the above, the additional grounds raised by the assessee are devoid of merit and deserve to be rejected. The order passed under section 147 read with section 143(3) is in accordance with the provisions of the Income-tax Act and may kindly be upheld.”
8. We have heard the rival submissions and perused the material available on record. The additional grounds raised by the assessee go to the root of the validity of the reassessment proceedings and arise from the facts already available on record. Accordingly, the additional grounds are admitted for adjudication. The undisputed chronology of events shows that the assessee, after obtaining the reasons recorded for reopening, filed its objections on 28.12.2021. Thereafter, the Ld. AO proceeded with the reassessment and issued the final show-cause notice dated 21.03.2022. However, no separate speaking order disposing of the objections was passed before completion of the reassessment proceedings. The revenue, despite relying upon the factual report, has also not brought on record any separate speaking order disposing of such objections.
9. The contention of the Ld. DR that the objections were considered during the reassessment proceedings does not cure the above defect. The procedure laid down by the Hon’ble Supreme Court in GKN Driveshafts (India) Ltd. v. ITO [2003] 259 ITR 19 (SC) requires the Assessing Officer, upon receipt of objections to the notice for reopening, to dispose of the same by passing a speaking order before proceeding with the reassessment. Consideration of the objections in the course of reassessment cannot substitute the requirement of their disposal in the manner prescribed.
10. We further find that the Hon’ble Bombay High Court in KSS Petron (P.) Ltd. v. ACIT [ITA No. 224 of 2014, dated 03-10-2016], as relied upon in the present proceedings, has held that failure to follow the procedure prescribed in GKN Driveshafts (India) Ltd. (supra) goes to the jurisdiction of the reassessment proceedings and such defect cannot be cured by restoring the matter to the Assessing Officer. The same principle has also been referred to in Jayanthi Natarajan v. ACIT 401 ITR 215 (Madras).
11. In the present case, the assessee’s objections dated 28.12.2021 were admittedly on record, whereas no separate speaking order disposing of those objections has been produced before us. Mere reference to or consideration of the objections in the subsequent proceedings cannot be equated with compliance with the mandatory procedure laid down in GKN Driveshafts (India) Ltd. (supra).
12. Accordingly, respectfully following the aforesaid judicial precedents, Additional Ground Nos. 1 to 3 are allowed and the reassessment order passed under section 147 read with section 144B of the Act is quashed. Consequently, the original grounds raised on merits have become academic and are, therefore, left open and not adjudicated.
13. In the result, the appeal of the assessee bearing ITA No. 6695/Mum/2025 is allowed.
■