


Most Merchants will pay a fee on UPI payments above Rs 2,000
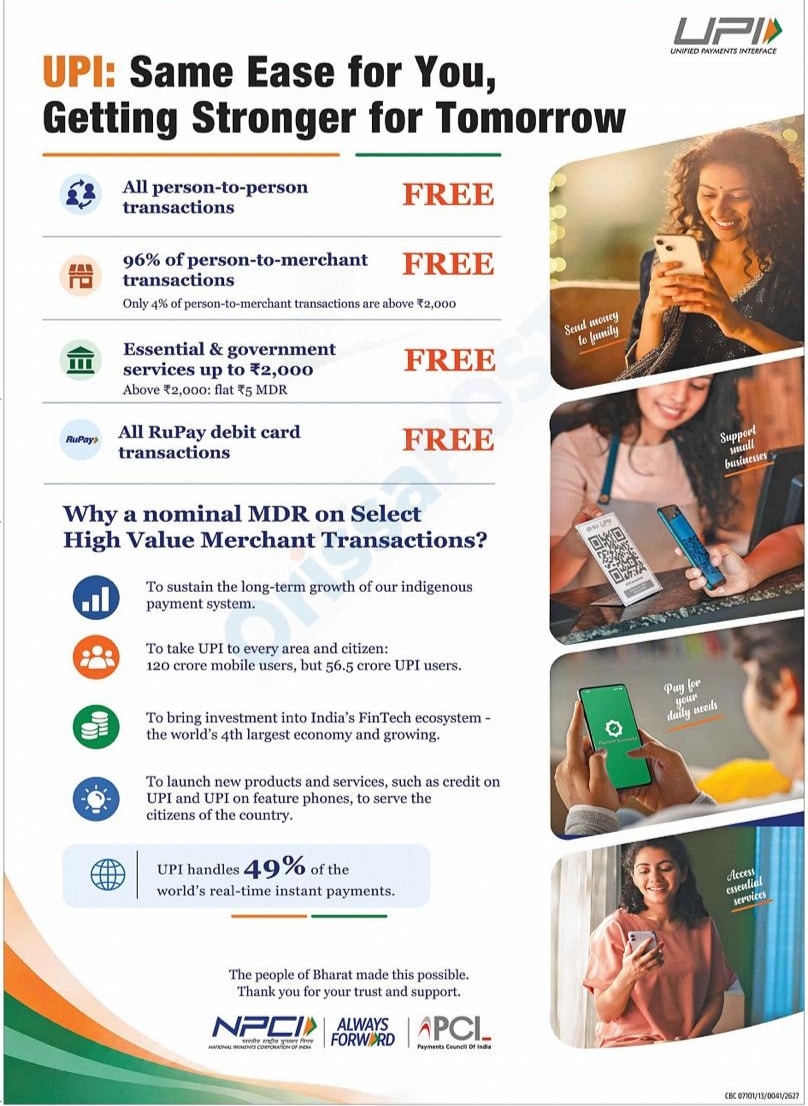
UPI: Same Ease for You, Getting Stronger for Tomorrow
Most Merchants will pay a fee on UPI payments above Rs 2,000
From October 15, most shops will pay 0.4 per cent on bigger UPI payments, capped at Rs 300. Customers and small merchants pay nothing.
A shop that is paid Rs 2,001 by the Unified Payments Interface (UPI) can keep less than one that’s paid Rs 2,000 when a new merchant fee starts on October 15, India Today’s calculation from the operator’s published rates shows.
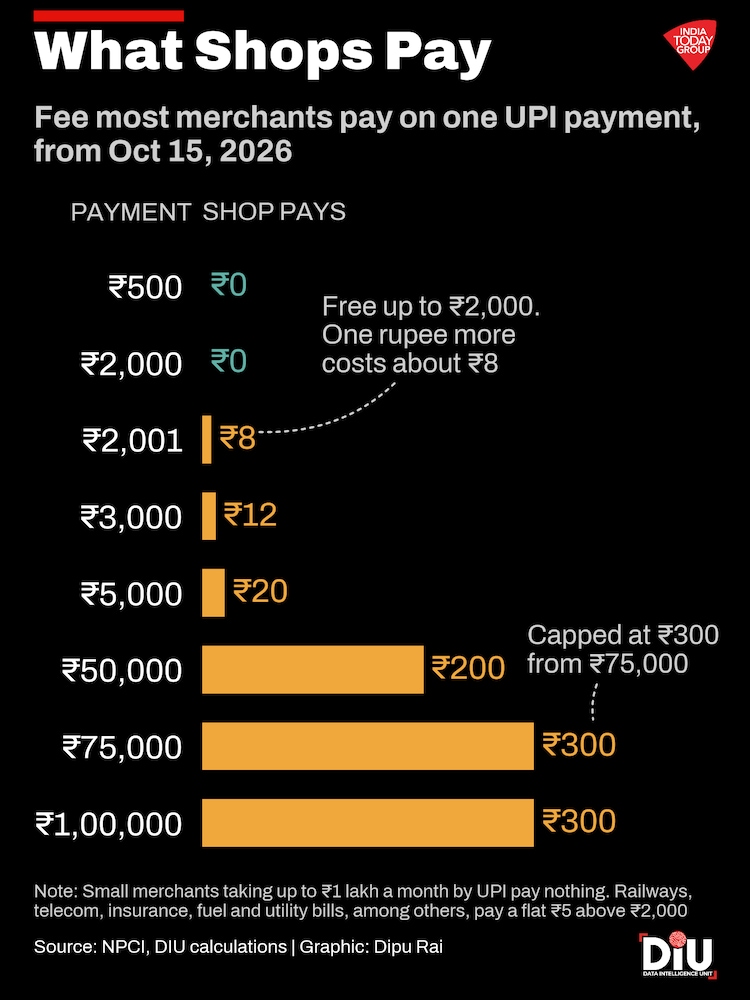
The fee, known as the merchant discount rate (MDR), is what a shop pays its bank on a payment. In answers to frequently asked questions from the National Payments Corporation of India (NPCI) dated September 15, most merchants will pay 0.4 per cent on payments above Rs 2,000 and nothing up to that line. On a Rs 2,001 payment, that comes to about Rs 8, leaving the shop about Rs 1,993.
The Rs 2,001 case is the edge, not the rule. Payments of up to Rs 2,000 make up more than 95 per cent of payments to merchants by number, according to the NPCI, which does not specify the period. Above that line, the fee is capped at Rs 300. Customers, the public sector company said, will not be charged, and payments between people, including transfers to family and between a person’s own accounts, will stay free.
WHAT A SHOP PAYS
On a Rs 3,000 payment, a merchant pays its bank Rs 12, and on Rs 50,000 it pays Rs 200, according to worked examples in NPCI’s answers. The fee stops rising at Rs 300, which a shop reaches on a payment of Rs 75,000, so on a Rs 1 lakh payment it pays Rs 300, not the Rs 400 that 0.4 per cent would come to, the NPCI said.
By our calculation, every payment from Rs 2,001 to Rs 2,008 leaves a shop with less than a Rs 2,000 payment would.
Per the corporation, merchants cannot pass the fee on to customers, and UPI apps may not add a platform fee of their own.
WHO PAYS LESS, OR NOTHING
Vendors who receive up to Rs 1 lakh a month through UPI QR codes directly into their accounts, a category called P2PM (person-to-person merchant), will continue with zero MDR. A vendor taking more than Rs 1 lakh a month for three months in a row moves into the paying category, according to the NPCI.
Some sectors pay a flat Rs 5 on payments above Rs 2,000 instead of a percentage. The corporation names railways, telecom, insurance, and fuel in the “among others” tier, and separately lists insurance premiums, fuel at petrol pumps, and utility bills such as electricity, water and piped gas.
Payments to stockbrokers, securities dealers, and mutual funds carry a lower rate of 0.02 per cent, also capped at Rs 300. Recurring payments set up as UPI mandates, such as monthly bills, streaming subscriptions, and regular investments, carry no prescribed MDR. The FAQs do not say which rule applies to a mutual fund investment paid by mandate.
The MDR “is distributed only amongst the UPI ecosystem, to further invest in infrastructure resiliency, innovation, cybersecurity” and customer service, according to the NPCI’s answers. The corporation also said it plans a fund to support small merchants, with the details to be settled with the Reserve Bank of India (RBI).
HOW BIG THE CHANGE IS
UPI carried about 1,551 crore payments to merchants in August 2026, worth Rs 8.95 lakh crore. Those payments made up 63.3 per cent of all UPI payments by number but 30 per cent by value.
The average payment to a shop that month was Rs 577, a DIU calculation from NPCI data shows, against Rs 2,319 for a transfer between people. An average cannot show how many shop payments cross Rs 2,000.
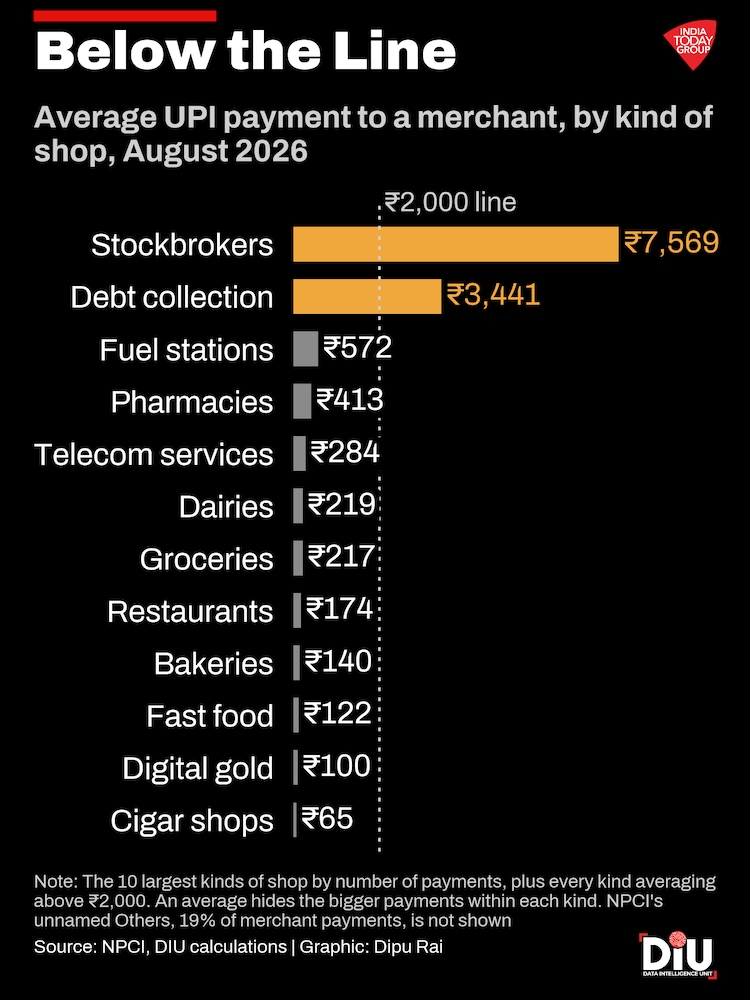
Of the 29 named kinds of shop in NPCI’s merchant data, only two averaged above Rs 2,000 in August 2026: stockbrokers, at Rs 7,569, and debt collection agencies, at Rs 3,441, according to our analysis. Groceries averaged Rs 217 and fast food Rs 122, by the same analysis.
The two above the line made up 1.9 per cent of merchant payments by number and 15.4 per cent by value. Another 19.2 per cent of merchant payments fall in a category the NPCI does not name.
WHERE THE 4 PER CENT CAME FROM
A figure that has appeared in coverage of the fee — that only four per cent of merchant payments are above Rs 2,000 — does not appear in the Finance Ministry’s statement of August 8. The ministry said the “vast majority of the transactions will remain free of charge for merchants on UPI”, without giving a share.
The figure appeared in a report on August 4, which said such payments were “just four per cent of the transaction volume” in a passage on brokerage estimates, without naming a source for it. The NPCI’s own figure, that more than 95 per cent of merchant payments are Rs 2,000 or less, puts the share above the line at less than five per cent.
WHAT THE ANSWERS LEAVE OPEN
The NPCI’s answers don’t word the Rs 2,000 line the same way. One says small-value payments “up to Rs 2,000” are unaffected. Another says “any transaction under Rs 2,000 incurs no MDR”. It is silent on a payment of exactly Rs 2,000. NPCI’s own worked example charges nothing on a Rs 2,000 payment, which is the reading this story uses.
School and college fees are not given a figure. Payments above Rs 2,000 “benefit from flat-fee structures or capped processing rates”, the FAQ says, without saying which or how much.
The answers also cite no circular number, and describe the fee as “discussed in this amendment”, without naming the document being amended.
The FAQ’s figure for August also differs from NPCI’s own statistics. The FAQ says UPI processed payments “valued at Rs 29.9 lakh crore in August 2026”; NPCI’s monthly statistics put the figure at Rs 29.82 lakh crore.
The fee starts on October 15. Until the NPCI says more, what a school pays and whether a Rs 2,000 payment is free rest on its answers to frequently asked questions.
Data note: NPCI’s answers to frequently asked questions on MDR, dated September 15, 2026; NPCI UPI statistics for August 2026, taken September 17, 2026. Fees on sample payments and average payment sizes are DIU calculations; averages don’t show how many payments exceed Rs 2,000.
Key Highlights of the New Rule
- Completely Free for Consumers: Customers will pay ₹0 extra. The government has strictly instructed banks to ensure that merchants do not pass this MDR on to customers, and UPI apps cannot charge platform fees for it. [4, 5, 6]
- Person-to-Person (P2P) Exempted: All personal transfers (sending money to friends, family, or between your own accounts) remain 100% free regardless of the amount. [1, 2]
- Transactions Under ₹2,000 Exempted: Any merchant payment up to ₹2,000 attracts zero MDR. According to the Ministry of Finance, this shields roughly 96% of all everyday merchant transaction volume. [4]
- Small Vendors Protected: Street vendors and small shops earning under ₹1 lakh per month through UPI QR codes are fully exempt from paying the fee. [4, 5]
- Fee Cap: For general commercial transactions above ₹2,000, the 0.4% fee is capped at ₹300 per transaction (effectively capping the fee for any transaction amount of ₹75,000 or more). [4, 7]
Sector-Specific Concessions
| Sector Category | New Fee Structure (Above ₹2,000) |
|---|---|
| General Commercial Merchants (Retail, Electronic stores, etc.) | 0.4% (Capped at ₹300) |
| Utilities & Essentials (Railways, Telecom, Insurance, Fuel, Utilities) | ₹5 flat fee per transaction |
| Capital Markets (Mutual funds, Broker stock payments) | 0.02% (Capped at ₹300) |
| Auto-SIPs & RuPay Debit Cards | ₹0 (Completely Free) |
New UPI charges from October 15: What it means for you
The new Merchant Discount Rate framework will impose a 0.4% charge on direct UPI payments to merchants above Rs 2,000. The charge will be paid by the merchant to its acquiring bank and will be capped at Rs 300 for transactions of Rs 75,000 and above.
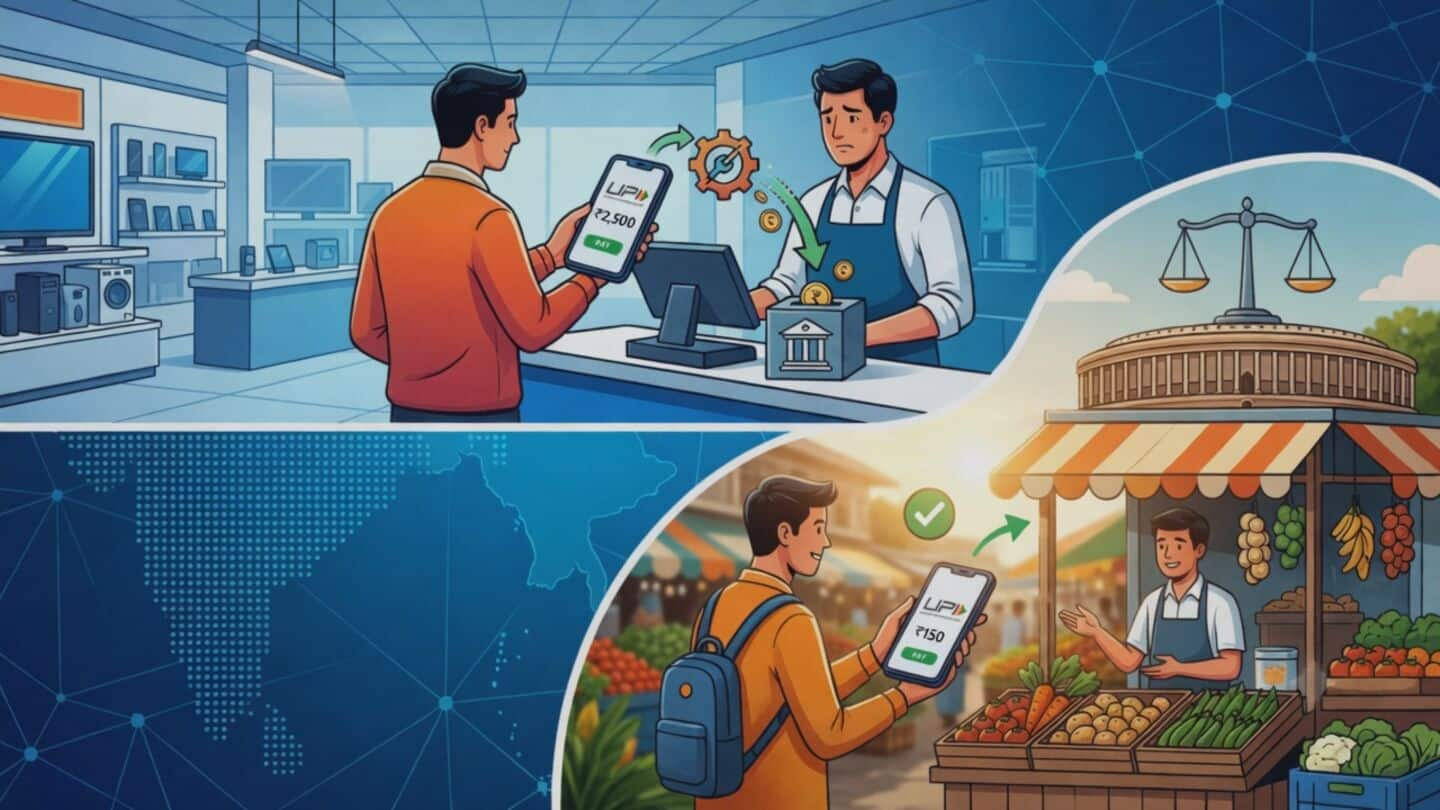
A new charge will apply to some UPI payments from October 15, but consumers will not have to pay it.
Under the new Merchant Discount Rate framework, merchants will be charged 0.4% on direct UPI payments above Rs 2,000. The fee will be paid by the merchant to its acquiring bank and capped at Rs 300 for transactions of Rs 75,000 and above.
So what changes for you?
If you pay Rs 1,500 through UPI at a shop, nothing changes. If you pay Rs 3,000, the merchant will pay Rs 12 in MDR, but you will still pay Rs 3,000.
And that is where the more interesting question begins. If the customer does not pay the fee directly, who ultimately bears the cost?
WHAT HAPPENS WHEN YOU PAY MORE THAN RS 2,000?
The simplest way to understand the new system is through the numbers.
A Rs 3,000 UPI payment will attract an MDR of Rs 12.
A Rs 50,000 payment will attract Rs 200.
A Rs 75,000 payment would work out to Rs 300, and that becomes the maximum charge. So even a Rs 1 lakh UPI payment will attract Rs 300 rather than Rs 400.
The charge applies to Person-to-Merchant, or P2M, transactions.
It does not mean your bank account will suddenly be debited for an extra Rs 12 when you buy something worth Rs 3,000.
The merchant bears the MDR.
YOU WILL NOT SEE A SEPARATE UPI FEE
The framework is explicit on this point. Merchants cannot pass the MDR on to customers while accepting UPI payments.
So if your bill is Rs 3,000, a merchant cannot simply say that UPI costs Rs 12 extra and collect Rs 3,012 from you. The framework says merchants cannot pass the MDR on to buyers while accepting payments through UPI. Consumers are expected to pay the posted price.
UPI app providers also cannot impose a platform fee or any other charge on UPI payments.
For consumers, therefore, the transaction remains free.
There is also no charge for sending money to another person. Person-to-person transfers, whether to a friend, family member or another account belonging to you, remain free regardless of the amount transferred.
MOST EVERYDAY UPI PAYMENTS WILL NOT BE AFFECTED
The new MDR does not apply to standard P2M UPI transactions of Rs 2,000 or less.
According to the FAQ, these transactions account for more than 95% of P2M UPI transaction volume.
So a Rs 100 payment at a tea stall, a Rs 700 grocery bill or a Rs 1,500 purchase will continue as before.
There is no MDR on these transactions.
The change becomes relevant when you make a direct UPI payment to a merchant above Rs 2,000.
WHAT DOES THE CHARGE LOOK LIKE IN REAL LIFE?
Consider a restaurant bill of Rs 2,500.
If you pay by direct account-to-merchant UPI, the restaurant would incur an MDR of Rs 10.
You still pay Rs 2,500.
Now consider a Rs 10,000 purchase. The merchant would pay Rs 40 in MDR.
At Rs 50,000, the charge rises to Rs 200.
The cap becomes important for larger purchases. At Rs 75,000, the 0.4% calculation reaches Rs 300, and that becomes the ceiling. A Rs 1 lakh transaction therefore attracts Rs 300 rather than Rs 400.
The government says the rate is still considerably lower than charges associated with traditional card payments. The FAQ puts typical credit card MDRs at 1.5% to 2.5% and debit card MDRs at up to 0.90%.

SMALL SHOPKEEPERS HAVE A SEPARATE EXEMPTION
The Rs 2,000 threshold is not the only protection for small merchants.
Vendors classified under the P2PM framework and receiving up to Rs 1 lakh a month through UPI QR codes directly into their accounts will continue to enjoy zero MDR.
This means a small vendor does not automatically start paying MDR simply because one customer makes a payment of more than Rs 2,000.
For example, if a qualifying small vendor receives Rs 2,500 from a customer, that payment itself does not make the vendor liable for MDR.
The framework says eligibility depends on the merchant’s classification and monthly inward-payment threshold.
If a P2PM merchant receives more than Rs 1 lakh through UPI for three consecutive months, it will transition into the P2M category.
Existing QR codes will continue to work. Small merchants do not need to replace or re-register them because of the new MDR framework.
SOME PAYMENTS WILL ATTRACT ONLY RS 5
The standard 0.4% MDR does not apply to every type of merchant payment.
Certain categories, including railways, telecom services, insurance and fuel, will have a flat MDR of Rs 5 for transactions above Rs 2,000.
That makes a big difference for larger payments.
A Rs 50,000 payment at a regular merchant would attract Rs 200.
A qualifying Rs 50,000 insurance payment would attract just Rs 5.
The same Rs 5 flat rate applies to qualifying fuel payments above Rs 2,000. Payments below Rs 2,000 remain at zero MDR.
Electricity, water and piped natural gas payments above Rs 2,000 will also attract a flat Rs 5 MDR rather than the standard 0.4% rate. Payments below that threshold will remain at zero MDR.
Capital-market payments have yet another rate. Payments involving mutual funds, securities, stockbrokers, dealers and investment platforms will attract an MDR of 0.02%, capped at Rs 300.
WHAT ABOUT CREDIT CARDS ON UPI?
The new MDR framework is specifically for direct account-to-merchant UPI payments.
Credit-linked UPI transactions, such as RuPay credit cards linked to UPI and pre-sanctioned credit lines, are governed by separate credit-product rules.
So the new 0.4% framework should not be read as a new charge applicable to every transaction made through a UPI app.
CAN MERCHANTS RAISE PRICES BECAUSE OF THIS?
This is where the answer is less straightforward.
The rules prevent a merchant from directly passing the MDR on to a customer as a UPI fee.
But that is different from saying that a business can never change its prices.
Consider a Rs 3,000 product.
One merchant could absorb the Rs 12 MDR and continue selling it for Rs 3,000.
Another could decide that its overall costs have increased and raise the general price of the product to Rs 3,012 for everyone, regardless of how they pay.
That would not be the same as adding a separate UPI surcharge.
The FAQ argues that merchants have little economic incentive to inflate prices because digital payments can generate higher footfall, larger average transaction values and lower cash-handling risks. It says consumers will continue to pay the listed price.
But that is an economic argument, not a blanket legal guarantee that businesses can never change their prices.
Whether merchants absorb the cost, accept a slightly lower margin or adjust their broader pricing will depend on the individual business and the competitive environment.
So while you will not be charged the MDR directly, it is too simplistic to say that consumers can never feel the economic impact of the new cost.
WHY IS THE GOVERNMENT INTRODUCING MDR NOW?
The government’s argument is that UPI has become too large to rely indefinitely on government subsidies to fund its infrastructure.
The FAQ estimates that payment operations, server bandwidth, fraud prevention systems and bank technology support cost the industry around Rs 20,000 crore a year.
UPI processed 2,451 crore transactions worth Rs 29.9 lakh crore in August 2026 alone, according to the FAQ.
The government says MDR revenue will remain within the UPI ecosystem and be used for infrastructure resilience, innovation, cybersecurity and customer service.
It has also proposed a dedicated fund to support digital-payment infrastructure and merchant onboarding in smaller towns and rural areas. The detailed framework for that fund is to be finalised in consultation with the Reserve Bank of India within three months.
The broader objective is therefore to move UPI towards a commercial model that can fund its own infrastructure rather than depend entirely on government support.
SO WHAT DOES THIS MEAN FOR YOU?
For most people, the immediate answer is simple. Not much changes.
If you use UPI to make everyday payments below Rs 2,000, the new MDR does not affect you.
If you transfer money to another person, there is still no charge.
If you make a larger purchase, the merchant, not you, pays the MDR.
You also cannot be charged a separate UPI fee by the merchant under the new framework, and UPI apps cannot impose their own platform fee.
But there is a broader economic question that the new rules cannot completely settle.
The framework determines who pays the payment-processing fee directly. It does not determine how every business will respond to having that additional cost.
A merchant may absorb it. Another may accept a slightly lower margin. Another may find ways to cut costs. Some businesses could potentially adjust their general prices.
That does not mean prices will rise because of MDR. The FAQ itself argues that merchants have little economic incentive to do so.
But it is important to distinguish between a direct UPI charge, which the framework prohibits merchants from passing on, and the broader question of how businesses manage their costs.
So the most accurate way to look at the change is this.
UPI remains free for you at the point of payment. But the cost of processing some larger merchant transactions has now shifted into the merchant side of the ecosystem.
The new regime begins on October 15.
The merchant pays first.
Who ultimately bears that cost will depend on what merchants do next.
UPI payments above Rs 2,000 may attract charges. Can you split a Rs 10,000 payment into five transactions?
If UPI transactions above Rs 2,000 eventually attract a customer-facing charge, users may look at debit cards as an alternative, particularly for larger purchases
UPI users may have to pay a charge on certain transactions above Rs 2,000, following the government’s latest notification. However, the exact charge is yet to be decided, and the proposed change will apply only to select merchant transactions, not peer-to-peer (P2P) transfers.
As per the Gazette notification, UPI transactions up to Rs 2,000 are exempt from any charges by banks or system providers. All RuPay debit card transactions are fully exempt.
“This essentially means that any UPI transact…
Read more
. Google Gemini Back to School 2026
. Make AI Max work for your business with new testing and planning tools.
. Doubled cell limits in Google Sheets now generally available
. Manage external sharing for Gemini Notebook in the Admin console
. Inside the Gemmaverse: Celebrating one billion Gemma downloads
. Personalize the content you see on Search, Discover, and News
. Gemini in Google Sheets is now available on Android devices
. The Gemini desktop app is now available for Windows
. macOS 27 Golden Gate is INCREDIBLE! – First 15 Things
. Take an interactive journey through America’s national parks
. Seamlessly import your team and data from Microsoft to Google Workspace during setup
. Google Workspace Weekly Recap – September 11, 2026
. Set up sharing boundaries for Google Drive with unified data protection rules
. GPT-Live-1 is now in the API
. New and improved: GitHub Copilot harness, agent skills, and richer context
. Tap to pay with Google Pay is coming to Walmart
for more refer Gemini website click here
for more refer Artificial Intelligence website click here